Home Blog

Broadcom CEO Casino Warning Just Sent Korea’s Market Plunging — Is the AI Boom Cracking?

0

Broadcom CEO Casino Warning Just Sent Korea’s Market Plunging — Is the AI Boom Cracking?

One of the biggest winners of the AI boom just compared a chunk of the AI investing crowd to casino gamblers, and markets reacted within hours. The Broadcom CEO casino warning, delivered at an event in Singapore on Monday, helped set off a chip-stock selloff that rolled through Asia on Tuesday, pushing South Korea’s benchmark index down as much as 7% in a single session. It’s the second time in about a month that executives’ own words have rattled the AI trade, after the AI leaders’ slowdown call that hit chip stocks in September. Here’s exactly what was said, why it landed so hard, and what it does and doesn’t mean for your money.

The Broadcom CEO Casino Warning: What Hock Tan Actually Said

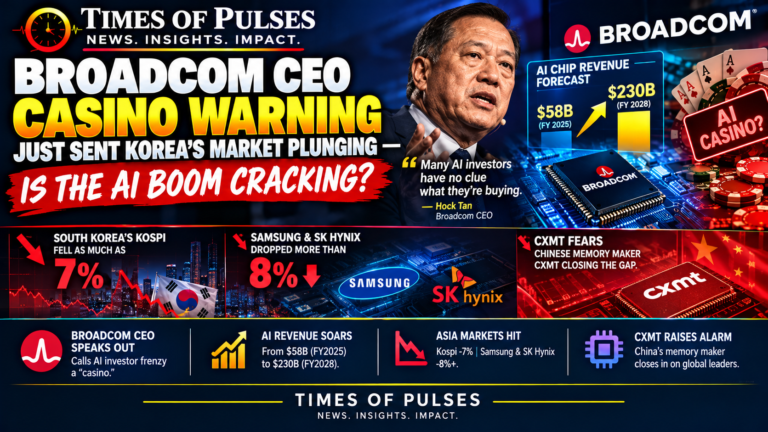
Broadcom CEO Hock Tan told the audience in Singapore that many investors piling into AI “have no clue what they are investing in,” according to Bloomberg’s report, carried by Yahoo Finance. He said those investors set extremely high expectations and then discover the experience feels a lot like gambling in a casino.

He didn’t stop there. Tan argued that AI model developers need customers who can earn real returns from the technology, rather than companies burning budgets on tokens while they experiment, likening it to a kid who spends a handful of arcade tokens in minutes and learns nothing. He also said OpenAI reaching $50 billion in annualized revenue in September shows a viable business model but says little about long-term profitability, and he warned that financing, not chip supply, could become the industry’s biggest constraint.

Korea Pays the Price for the Broadcom CEO Casino Warning

South Korea took the hardest hit because its market leans so heavily on chipmakers. The Kospi fell more than 6%, and by as much as 7% at its worst. Samsung Electronics and SK Hynix each dropped more than 8% and were both heading for a fifth straight losing session, and Seoul’s exchange briefly paused automated program trading. Japan’s Nikkei slid nearly 3%, Kioxia Holdings shed more than 12%, and MSCI’s Asia Pacific gauge was on track for its weakest close since August. Foreign investors have now sold more than $6 billion of Kospi shares on a net basis in October alone.

Back in the US, Monday’s session looked calmer on the surface. The Dow rose 0.38% to 51,850.55, while the S&P 500 slipped 0.06% to 7,807.24 and the Nasdaq fell 0.44% to 27,245.90, with chipmakers weighing on the tech-heavy indexes just ahead of a busy earnings week.

The Second Trigger: A Chinese Rival Closes In

The Broadcom CEO casino warning wasn’t acting alone. The selloff deepened after Chinese memory maker CXMT announced progress on a next-generation DRAM design known as 4F², which packs more storage into less space, with plans for a server DDR5 product built on it by the end of 2026. Samsung, SK Hynix, and Micron together control roughly 90% of the global DRAM market, so any credible challenger gets attention fast. Even Samsung’s record preliminary third-quarter profit last week barely lifted the sector, a sign that fear of future competition and doubts about AI spending are currently outweighing strong earnings today.

The Twist: The Man Sounding the Alarm Is Betting Big on AI

Here’s what makes this story more interesting than a simple “bubble” headline: Tan’s own company forecasts AI chip revenue rising roughly fourfold, from about $58 billion this fiscal year to $230 billion in fiscal 2028. His message isn’t that AI is fake. It’s that proven returns and speculative expectations are very different things, and many investors are treating them as the same.

The same panel offered a counterpoint. Intel CEO Lip-Bu Tan, a different executive from Broadcom’s Hock Tan, said the rapid AI buildout means hardware will stay in short supply for the next two to three years, the same scarcity theme we covered when chip stocks erased an entire week’s selloff in just three days. Real demand and real speculation can exist at the same time, which is exactly why this corner of the market is so jumpy.

Why the Broadcom CEO Casino Warning Matters Beyond Chip Stocks

The sharpest part of Tan’s message may be the financing point. It shifts the spotlight from whether enough chips can be built to whether the money to pay for them will keep flowing, putting AI-linked debt deals and the balance sheets of capital-hungry model developers under closer scrutiny. That’s worth reading alongside Treasury yields sitting near multi-year highs, because a buildout that depends on borrowed money gets harder to fund as borrowing costs rise. That connection is our own reading, not something Tan said.

It also fits a pattern we flagged when AMD crossed $1 trillion: rallies led by a handful of AI names can look stronger than the market underneath them, which means one comment can move far more than one sector. And it isn’t even the first chip scare of 2026. In late July, a similar selloff wiped more than $1 trillion from the biggest chip stocks before they recovered.

What This Means for Your Own Money

  1. A Broadcom CEO casino warning is a sentiment shock, not a change in earnings. It can still move prices for days, so don’t ignore it, but one rough session isn’t proof the AI buildout is over.
  2. Check how much chip and AI exposure you already hold. Broad index funds now carry heavy AI weight, so you can feel days like this even if you never bought a chip stock. If you’ve been following Micron or SanDisk from our October stocks to watch list, treat this as a reminder of how volatile that corner can be.
  3. Separate proven returns from big expectations. Tan’s own test is worth borrowing: for any AI-linked stock you own, ask what real revenue supports the valuation.
  4. Watch financing and yields, not just headlines. If credit gets tighter or yields climb further, the companies most dependent on borrowing tend to feel it first.

Bottom Line

The Broadcom CEO casino warning doesn’t say AI is a fad. It says the market may be paying for expectations faster than companies can prove returns, and when that message comes from someone who sells the chips powering the boom, investors listen. Add a rising Chinese challenger in memory chips and a Korean market that’s heavily tied to two stocks, and you get a selloff that feels bigger than any single headline. Whether this fades like July’s scare or becomes a longer reset will likely depend on earnings, financing conditions, and whether CXMT’s progress turns into real products.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.
Stocks to Watch October 2026: 5 Names Tied to This Month’s Biggest Stories

Stocks to Watch October 2026: 5 Names Tied to This Month’s Biggest Stories

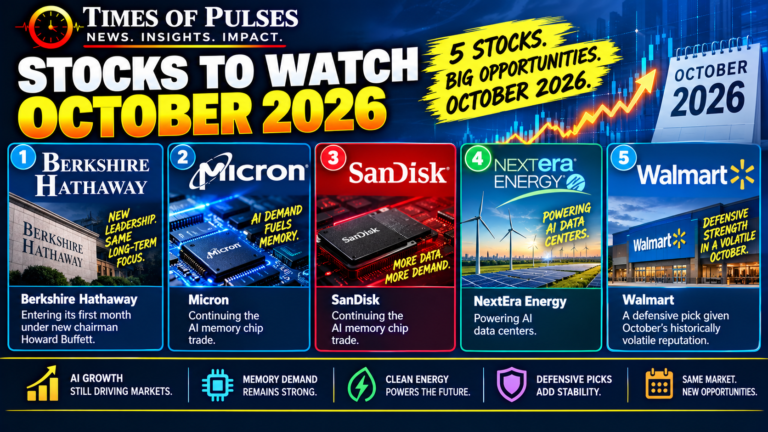
October has a reputation on Wall Street, and not a flattering one. Historically, it’s been one of the stock market’s more volatile months. That makes stocks to watch October 2026 worth choosing carefully this time around, with names tied to real, current stories rather than hype. Here are five companies sitting directly inside the biggest threads we’ve been tracking heading into the new month.

Stocks to Watch October 2026: Why October Deserves Extra Caution

Before getting into specific names, it’s worth noting what several market analysts have already flagged this month: October has historically been one of the stock market’s most dangerous months for volatility, even though it’s also produced some of the biggest rebounds. That history doesn’t mean avoid the market entirely, but it’s a reasonable backdrop for why stocks to watch October 2026 should lean toward companies with real catalysts behind them, not just momentum.

1. Berkshire Hathaway (BRK.B) — The Post-Buffett Era Begins

Berkshire Hathaway tops this list of stocks to watch October 2026 for an obvious reason: it’s entering its first full month under new leadership. We covered how Warren Buffett stepped down as chairman after 56 years, handing the role to his son Howard while Greg Abel continues running daily operations. With the company sitting on close to $397 billion in cash and having trailed the S&P 500 for much of 2026, October is an early test of how markets view Berkshire now that its most famous decision-maker has stepped back from the chairman’s seat.

2. Micron Technology (MU) — Still Riding the AI Memory Wave

Micron remains one of the clearest ways to track the ongoing AI infrastructure buildout. We’ve followed this stock closely through the wild memory chip shortage swings earlier this year, and current analyst coverage continues to flag Micron’s data center memory and storage products as directly tied to how fast hyperscale AI infrastructure keeps expanding. For investors tracking the AI trade specifically through chip demand rather than software, Micron remains one of the more direct plays available.

3. SanDisk (SNDK) — Wall Street Still Bullish

SanDisk earns its spot among stocks to watch October 2026 for similar reasons to Micron, continued strength in the memory chip space, with current analyst sentiment described as still bullish heading into the month. This name has been genuinely volatile over the past several months, making it a useful one to watch for anyone trying to understand how quickly sentiment in the memory chip sector can shift in either direction.

4. NextEra Energy (NEE) — The Power Behind the AI Boom

NextEra Energy represents a different layer of the same AI story: electricity. As data centers scale up to meet AI demand, utilities capable of expanding power generation become an increasingly important piece of the puzzle, and NextEra has been flagged among October’s notable picks in the utilities and consumer-defensive sectors that several analysts say have lagged and now look more attractively valued. With Treasury yields sitting near a 2004 high, dividend-paying utility stocks like NextEra also become more relevant for investors seeking steady income alongside growth exposure.

5. Walmart (WMT) — The Defensive Pick for a Shaky Month

Rounding out this list of stocks to watch October 2026 is Walmart, included specifically as a defensive counterweight to the more volatile AI and chip names above. Walmart has pulled back meaningfully from its 2026 high despite raising its full-year sales and profit outlook, creating what some analysts consider an attractive entry point for a company that sells the kind of everyday essentials people buy regardless of economic conditions. In a month with October’s reputation for turbulence, having at least one genuinely defensive name on the list is a reasonable hedge.

What Ties This List Together

Four distinct threads run through these stocks to watch October 2026: the post-Buffett transition at Berkshire, the ongoing AI memory chip trade through Micron and SanDisk, the power-demand side of AI infrastructure through NextEra, and defensive positioning through Walmart given October’s volatile track record. That’s a deliberate spread, not a bet on any single narrative continuing uninterrupted.

What This Means for Your Own Portfolio

  1. Don’t chase a name just because it’s on a list, including this one. Research each company’s current valuation and your own risk tolerance before acting on any single pick.
  2. Consider balancing growth and defensive names, as this list does. Pairing higher-volatility chip stocks with something like Walmart is a reasonable way to manage October’s historical choppiness.
  3. Watch how rates affect each of these differently. Elevated Treasury yields tend to pressure growth-oriented names like Micron and SanDisk more than dividend payers like NextEra and Walmart.
  4. Keep an eye on Berkshire specifically this month. The market’s reaction to the post-Buffett leadership era, positive, negative, or indifferent, will say a lot about how much of Berkshire’s premium was tied to one person.

Bottom Line

Motley Fool’s October coverage summed up the month’s reputation well: historically turbulent, but also historically a source of buying opportunities for investors who stay selective. These five stocks to watch October 2026, Berkshire Hathaway, Micron, SanDisk, NextEra Energy, and Walmart, each connect to a real, ongoing story rather than speculation, which is exactly the kind of grounding worth having heading into one of the market’s more unpredictable months.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.
Agent Orchestration Wall Street: The Skill Nobody Had Heard of a Year Ago Now Pays $190,000

0

Agent Orchestration Wall Street: The Skill Nobody Had Heard of a Year Ago Now Pays $190,000

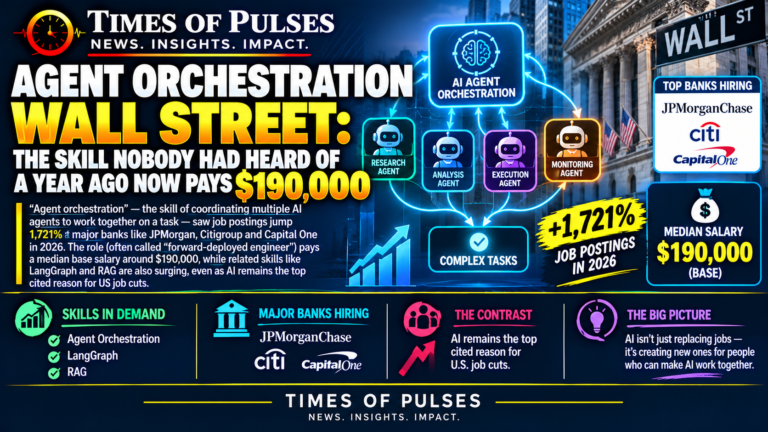
Picture this: a skill barely existed on Wall Street’s radar a year ago. Today, it’s being called “arguably the hottest skill on Wall Street,” job postings mentioning it have exploded by a jaw-dropping 1,721%, and the people who have it are commanding salaries north of $190,000. If that sounds like clickbait, it isn’t, this is a real, verified hiring trend sweeping through the biggest banks in America right now.

Agent Orchestration Wall Street: What Is This Skill, Exactly?

The skill is called agent orchestration, and once you understand what it actually means, the hype makes a lot more sense. It’s the ability to design a system where multiple AI agents work together on one task, each handling a different piece and passing results along to the next. Picture a loan application: one AI agent verifies the input data, a second analyzes the supporting documents, and a third checks everything against banking regulations before a human ever sees it. That’s agent orchestration Wall Street banks are racing to hire for, moving past simple chatbots into coordinated teams of specialized AI.

The Eye-Popping Growth Numbers

According to hiring data firm Draup, job postings mentioning agent orchestration jumped 1,721% in 2026 compared to the year before. Worth noting honestly: that growth started from a genuinely small base, references climbed from just 108 mentions in 2025 to 1,967 this year, so the percentage looks more dramatic than the raw numbers alone. Still, that doesn’t make it any less real. Overall AI-related job postings at major banks including JPMorgan Chase, Citigroup, and Capital One reached 139,819 listings, a 49% jump from 2025. Draup CEO Vijay Swaminathan didn’t mince words about where this agent orchestration Wall Street trend stands relative to everything else: “this is arguably the hottest skill on Wall Street.”

Why Agent Orchestration Wall Street Demand Grew So Badly, So Fast

Banks have spent the last couple of years hiring data scientists to build individual AI models. What’s changed is that a single AI model handling one task in isolation isn’t enough anymore, banks need entire workflows where several specialized agents hand tasks off to each other reliably, securely, and in compliance with financial regulations. That’s created a new role entirely: the “forward-deployed engineer,” someone who figures out which agents are needed for a given business process, what each one should do, and how they should communicate, then actually builds and embeds that system directly into trading desks, compliance units, and back-office operations.

What It Actually Pays

Here’s the number that makes this agent orchestration Wall Street story worth paying attention to beyond the headline growth stat: generative AI managers, the kind of role overseeing this work, earn a median base salary of roughly $190,000, according to Draup’s data. That’s a genuinely strong income for a skill set that, for most people, didn’t even exist as a formal job category two years ago.

The Skills Riding Along With It

Agent orchestration isn’t growing in isolation, it’s pulling a whole ecosystem of related skills up with it. Mentions of LangGraph, a framework for building multistep AI workflows, rose 679% to 5,300 references. Retrieval-augmented generation, commonly known as RAG, a technique for grounding AI responses in real company data, climbed 259%. And prompt engineering, despite not growing as fast percentage-wise, still leads in raw volume with 11,368 mentions, a reminder that the most explosive growth rate and the most total demand aren’t always the same skill.

Oversight roles are expanding right alongside the builders too. Mentions of responsible and safe AI use jumped 657%, AI governance and policy references rose 394%, and risk-management-related postings climbed 359%. Banks aren’t just hiring people to build these agent systems, they’re hiring just as aggressively to make sure someone’s watching them.

The Twist: AI Is Also Cutting Jobs

Here’s the irony worth sitting with: even as agent orchestration Wall Street demand explodes, AI remains the single most commonly cited reason for job cuts across the US this year. The same technology creating this new, highly paid career path is simultaneously eliminating other roles, often the exact kind of repetitive analytical work that AI agents are now being built to automate. It’s a genuinely two-sided story, AI isn’t just taking jobs or just creating them, it’s doing both, often within the same industry and sometimes the same company, at the same time.

What This Means for Your Own Career

  1. If you’re in finance, tech, or analytics, this is worth a real look. A skill growing this fast with salaries this strong is a legitimate signal, not hype, even accounting for the small starting base.
  2. You don’t need to become an AI researcher to benefit. Forward-deployed engineer roles value people who understand both the business process and how to coordinate the tools, not just raw technical depth.
  3. Think of this as part of your broader career and financial planning, not an isolated gamble. Upskilling toward an in-demand area fits the same long-term thinking we’ve covered in year-round financial planning, deliberate moves made before you’re forced into them.
  4. Watch how this connects to the AI infrastructure trade more broadly. The same AI buildout driving chip stock volatility and swings in AI-linked stocks is the underlying force creating this hiring surge, it’s one connected story playing out across markets and the job market simultaneously.

Bottom Line

CNBC’s reporting on this trend captured something genuinely rare: a brand-new, highly specific, highly paid skill category emerging almost overnight inside one of the most competitive job markets in the world. Agent orchestration Wall Street demand went from a rounding error to “arguably the hottest skill” in the industry within a single year. Whether or not it’s the right career pivot for you personally, it’s a useful real-time example of how quickly the value of a specific skill can shift when an entire industry decides it needs it, and a reminder to keep watching where that kind of demand shows up next.


This article is for informational purposes only and does not constitute financial or career advice. Consult a licensed career counselor or financial advisor for guidance specific to your situation.

Treasury Yields 2004 High: Why an $11 Billion Company Just Delayed Its IPO

0

Treasury Yields 2004 High: Why an $11 Billion Company Just Delayed Its IPO

Rising interest rates usually show up in your life as bigger numbers on a mortgage statement or a credit card bill. This week, they showed up somewhere more dramatic: they just talked an $11 billion company out of going public. Treasury yields 2004 high territory isn’t just a headline for bond traders anymore, it’s actively reshaping real business decisions in real time.

Treasury Yields 2004 High: The Numbers Behind the Headline

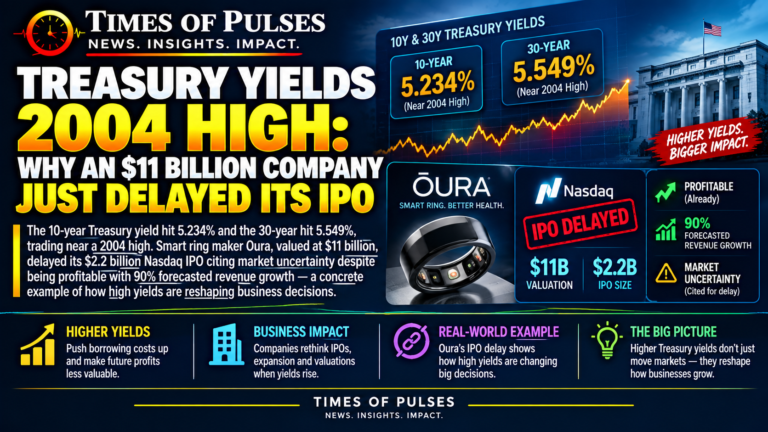
The move has been sharp and sustained. The 10-year Treasury yield sat at 5.234% this week, while the 30-year Treasury yield hit 5.549%, trading around levels not seen since 2004. This continues the climb we tracked when the Fed’s rate hike pushed yields back above 5% just weeks ago, except this Treasury yields 2004 high move has pushed meaningfully further than that initial test of the 5% level.

Why This Specific Level Matters So Much

Treasury yields function as the baseline cost of money for the entire economy. When the 30-year yield sits near a two-decade high, it doesn’t just affect bond traders, it raises the cost of every kind of long-term borrowing that gets priced off it, corporate bonds, mortgages, and crucially, the calculus companies use when deciding whether now is a good time to raise money by going public. A Treasury yields 2004 high environment makes every other form of borrowing more expensive by comparison, which is exactly the mechanism that turned this into an IPO story rather than just a bond market story.

The Real-World Casualty: Oura’s Delayed IPO

Smart ring maker Oura provided the clearest example of what a Treasury yields 2004 high environment actually does to real companies. The company had planned to sell 50 million shares priced between $40 and $44, aiming to raise up to $2.2 billion at a fully diluted valuation of $15.62 billion, a huge step up from its roughly $11 billion valuation in last year’s late-stage funding round. On Tuesday, Oura announced it was postponing the offering, citing market uncertainty, despite what the company described as strong investor demand and continued business strength.

What makes this notable is that Oura wasn’t struggling. The company said it’s profitable and forecasting 90% revenue growth for fiscal 2026. CEO Tom Hale framed the delay as a matter of timing rather than necessity, saying the company has “the luxury of choosing our moment.” That’s a telling detail: even a fundamentally strong, high-demand company is choosing to wait out this Treasury yields 2004 high environment rather than push through it.

Oura Isn’t Alone

This wasn’t an isolated decision. Earlier this month, nuclear services company Holtec suspended its own planned US IPO amid increased scrutiny of capital being poured into AI-related sectors. Together, these delays paint a picture of what’s typically one of the strongest windows of the year, the fall IPO season, getting off to an unusually tepid start. Investors are simultaneously digesting the Fed’s rate hike, ongoing geopolitical turmoil, and volatility in AI stocks, a combination that’s making companies and their bankers more cautious about pricing new offerings into a market this unsettled.

What’s Driving Yields This High

The climb behind this Treasury yields 2004 high move traces back to the same forces we’ve been tracking for weeks: persistent inflation concerns, the Federal Reserve’s rate hike, and renewed Middle East tensions keeping oil prices elevated and unpredictable. Stocks fell to start the week as this combination pushed yields higher, with the market still working through how much further borrowing costs might climb before the current tightening cycle runs its course.

What This Means for Your Own Money

  1. If you’re planning a major purchase requiring financing, rates aren’t easing anytime soon based on current signals. A Treasury yields 2004 high environment feeds directly into everything from mortgage rates to auto loans, exactly the tradeoff we discussed when weighing whether to save or pay down debt.
  2. Watch which companies actually go public over the next few months. A wave of delayed IPOs, even from strong, profitable companies like Oura, is a real signal about market conditions that’s worth paying attention to beyond just stock prices.
  3. Elevated yields tend to pressure stocks broadly, not just IPO candidates. This connects to the same volatility pattern we’ve tracked through multiple sessions of market declines this year, higher yields have repeatedly weighed on risk assets across the board.
  4. A company choosing patience over urgency is a reasonable model for your own financial decisions too. Oura’s decision to wait for better conditions rather than force a deal through reflects the same discipline worth applying to your own major financial moves right now.

Bottom Line

CNBC’s coverage of Oura’s decision captured the moment precisely: a genuinely strong, profitable company chose to wait rather than go public into a market shaped by a Treasury yields 2004 high environment. That’s a concrete, real-world reminder that when bond yields make headlines, the effects ripple far beyond Wall Street trading desks, into boardroom decisions worth billions of dollars. Whether yields ease from here or climb further likely depends on the same inflation and geopolitical questions that have been driving markets all year.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.
Warren Buffett Steps Down: 56 Years, $397 Billion in Cash, and One Brutal Truth He Left Behind

Warren Buffett Steps Down: 56 Years, $397 Billion in Cash, and One Brutal Truth He Left Behind

Some retirements are routine. This one isn’t. Warren Buffett steps down as chairman of Berkshire Hathaway after 56 years in the role, closing out one of the longest and most successful runs in American business history. But the real story here isn’t just the handoff, it’s what Buffett’s final moves and parting words actually mean for anyone trying to invest wisely today.

Warren Buffett Steps Down: What Actually Happened

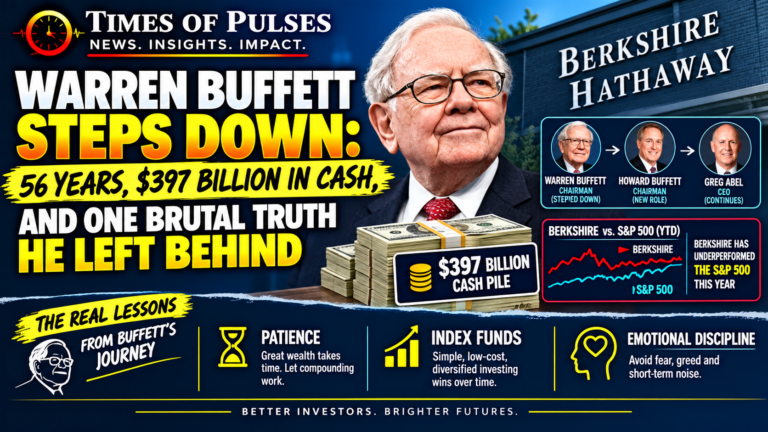
On September 18, 2026, Berkshire Hathaway announced that Warren Buffett, 96, would step down as chairman, a role he’d held since 1970. His son Howard Buffett, a Berkshire board member since 1993, was elected as the new chairman. Warren will remain on the board as Chairman Emeritus, a largely advisory position, while Greg Abel, who took over as CEO at the start of 2026, continues running the company’s day-to-day operations. This Warren Buffett steps down announcement is the third major step in a multi-year succession plan Buffett has carefully executed to make sure Berkshire doesn’t lose its identity once he’s fully gone.

Buffett explained the timing simply in his letter to shareholders: “Father Time always wins.” He described the arrangement plainly, noting that Abel runs the company while Howard protects its culture and values.

Why Buffett’s $397 Billion Cash Pile Matters Right Now

One detail makes the Warren Buffett steps down story more than just a leadership change: Berkshire is currently sitting on roughly $397 billion in cash, an enormous reserve that Buffett built up gradually rather than deploying into acquisitions during a period when he judged most assets overpriced. That’s not indecision, it’s the same discipline that’s defined his entire career: waiting patiently for genuinely attractive opportunities rather than feeling pressured to constantly deploy capital. Nobody, including Buffett himself, has said what specific conditions would trigger that cash finally getting put to work.

The Uncomfortable Truth Warren Buffett Steps Down News Is Glossing Over

Here’s a detail many headlines about Warren Buffett steps down news are glossing over: Berkshire’s stock has actually underperformed this year, rising just 1% compared to roughly 12% for the S&P 500. If that gap holds through year-end, it would mark the fifth time in the last ten years Berkshire has trailed the index. Rising oil prices have been cited as one factor weighing on the company’s recent performance, a dynamic we’ve tracked closely in our own coverage of oil price volatility and how to actually invest around it.

It’s worth keeping this in perspective, though: since 1965, Berkshire has still beaten the S&P 500 by nearly 10 percentage points annually on average, an extraordinary long-term record that a rough recent decade doesn’t erase.

The Real Lesson Behind “Father Time Always Wins”

Buffett’s core investing philosophy has always centered less on picking hot stocks and more on managing your own psychology as an investor, especially when markets get frightening. He’s repeated a version of the same message throughout his career: current market swings, however unsettling they feel in the moment, are minor compared to the actual crashes he’s lived through and invested through over seven decades. That perspective, treating short-term volatility as background noise rather than a crisis, is arguably more valuable to an everyday investor than any specific stock he’s ever picked.

Buffett’s Most Practical Advice for Everyday Investors

Despite being one of history’s greatest individual stock pickers, Buffett has spent decades publicly recommending that most people simply buy a low-cost S&P 500 index fund rather than try to pick winners themselves. In 2007, he famously bet that an S&P 500 index fund would outperform a handpicked group of hedge funds over the following decade, and he won convincingly. That’s a genuinely useful, evidence-backed piece of advice worth remembering: the investor most associated with beating the market has spent years telling ordinary people not to try.

What This Means for Your Own Portfolio

  1. Cash isn’t a wasted asset while you wait for opportunity. Berkshire’s $397 billion cash pile reflects patience, not fear, a reminder that holding cash during uncertain periods is a legitimate strategy, not a failure to invest.
  2. A rough year doesn’t erase a strong long-term record, or the reverse. Berkshire’s recent underperformance is real, but so is its 60-year track record; judge any investment, including your own portfolio, on the right time horizon.
  3. Simple, boring advice often beats sophisticated strategy. If you’re deciding how to build a portfolio from scratch, Buffett’s own preferred answer for most people remains a low-cost index fund, not stock picking.
  4. Managing your emotions matters more than managing your trades. The single habit Buffett has emphasized most consistently, staying calm through volatility, is free, available to every investor, and arguably harder to master than any specific investment strategy, a theme worth revisiting alongside broader year-round financial planning.

Bottom Line

NPR’s coverage of the transition captured the moment plainly: after more than 50 years in the role, Warren Buffett steps down as chairman, handing the position to his son while remaining involved as an advisor. The succession itself was carefully planned and long telegraphed, but the timing offers a genuine moment to revisit the investing principles that built Berkshire in the first place: patience, discipline, comfort with cash, and the humility to recommend index funds to people who don’t have his decades of experience. Those lessons don’t retire, even as the man who taught them steps back from the chairman’s seat.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.
FICO Score 10T Explained: The New Mortgage Model That Grades Your Credit Trend, Not Just Your Score

0

FICO Score 10T Explained: The New Mortgage Model That Grades Your Credit Trend, Not Just Your Score

Just weeks after we covered VantageScore breaking FICO’s mortgage monopoly, FICO itself is rolling out a genuinely different kind of credit score. FICO Score 10T isn’t just an updated version of the same old formula, it changes what lenders are actually measuring, and the FHA just set a firm date for when it takes full effect.

What Is FICO Score 10T, Exactly?

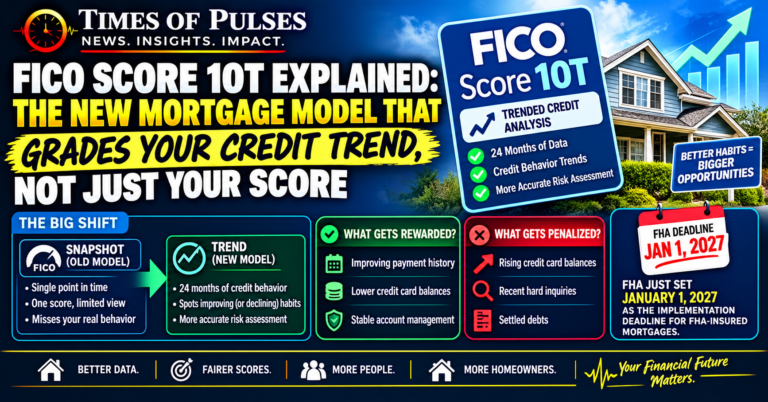
The “T” in FICO Score 10T stands for trended data, and that single word represents the biggest change to mortgage credit scoring in over two decades. Classic FICO evaluates your credit at a single point in time, a snapshot of where your balances and payment history stand the moment your score is pulled. FICO Score 10T instead analyzes your credit behavior over the past 24 months, looking for patterns rather than just a current number.

That means a borrower who carried high balances 18 months ago but has been steadily paying them down will score differently under FICO Score 10T than they would under Classic FICO, typically higher, because the model recognizes the improving trend rather than just where the balance happens to sit today.

Who FICO Score 10T Actually Helps

If you’ve been genuinely improving your financial habits, this is good news. FICO Score 10T rewards consistent, positive behavior over time: steadily declining balances, a track record of on-time payments, and generally improving credit management. People who’ve been quietly doing the right things for the past year or two, without necessarily seeing their Classic FICO score reflect that progress yet, stand to benefit the most from this shift.

Who FICO Score 10T Could Hurt

The flip side matters just as much. FICO Score 10T is notably stricter in several areas than Classic FICO:

  • Chronic minimum payments are read as a sign of financial strain and scored more harshly, even if you’re technically never late.
  • Rising balances over time, even with on-time payments, get flagged as a stress signal since the model can see the trend Classic FICO couldn’t.
  • Recent hard inquiries and newly opened accounts carry more weight, so anyone who’s applied for multiple credit cards or loans in the past 6-12 months will feel that more under this model.
  • Settled debts or recent delinquencies are judged more harshly and don’t fade from consideration as quickly as they did under older scoring approaches.

The Timeline: When This Actually Takes Effect

Here’s the news that makes this worth covering right now: the FHA has officially set January 1, 2027, as the implementation date for adding both VantageScore 4.0 and FICO Score 10T as eligible credit score models for FHA-insured mortgage underwriting, following an FHA announcement from earlier this year. On the Fannie Mae and Freddie Mac side, FICO Score 10T historical data was already published July 1, 2026, with the FHFA having validated the model back in April 2026, meaning the rollout has been happening gradually rather than all at once, and is now approaching a hard deadline for FHA loans specifically.

How FICO Score 10T Differs From VantageScore 4.0

It’s worth being clear about the distinction between these two new models, since they’re often mentioned together but work differently. VantageScore 4.0’s headline feature is including alternative data like rent, utility, and telecom payments, which is why it can score millions of people with thin credit files who were previously invisible to the system. FICO Score 10T’s headline feature is trended data, analyzing your behavior pattern over 24 months rather than including new data sources. Both push mortgage lending toward a more complete financial picture, but they get there through different mechanisms, and depending on your specific credit history, one could genuinely score you better than the other.

What This Means for Your Own Credit

  1. If you’re planning to buy a home in the next year, your recent credit behavior matters more than ever. New credit applications, rising balances, or a pattern of minimum payments over the past 24 months could weigh against you more under FICO Score 10T than they would have under the current system.
  2. Consistency now pays off later. If you’ve been managing your credit utilization carefully, that sustained good habit is exactly what FICO Score 10T is designed to reward, more so than a single strong score at one moment.
  3. Watch how any BNPL or split pay activity fits into this picture. As split pay credit reporting continues evolving, keep in mind that trended-data models like FICO Score 10T are built to catch exactly the kind of overlapping payment patterns that split pay users sometimes lose track of.
  4. Ask your lender which model they’re using, and when. With the January 1, 2027 FHA deadline approaching and Fannie/Freddie already accepting FICO Score 10T data, the model your mortgage gets evaluated under may depend on exact timing as much as which lender you choose.

Bottom Line

The FHA’s own announcement confirms this isn’t a distant, hypothetical change, it’s a scoring model with a real deadline now attached to it. FICO Score 10T represents a genuine philosophical shift in how mortgage lenders read your credit: not just where you stand today, but where you’ve been heading for the past two years. Combined with VantageScore’s expanded reach into rent and alternative data, mortgage credit scoring is undergoing its biggest transformation in decades, and understanding both models now, well before you actually apply, is worth the time.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed mortgage professional or financial advisor for guidance specific to your situation.

Split Pay Credit Score: What Changed in 2026 (And Which Apps Actually Report)

0

Split Pay Credit Score: What Changed in 2026 (And Which Apps Actually Report)

You split a $200 purchase into four payments through Klarna or Affirm, paid every installment on time, and assumed it had nothing to do with your credit score. For years, that assumption was correct. Split pay credit score reporting has quietly changed in 2026, and the honest answer to “does this affect my credit” now depends entirely on which app you used, a split pay credit score question with a genuinely different answer for each major provider.

What Is Split Pay, Exactly?

Split pay, more formally known as Buy Now, Pay Later or BNPL, lets you break a purchase into smaller installments, typically four payments spread over six weeks, often with no interest if you pay on time. It’s exploded in popularity: an estimated 91.5 million Americans now use BNPL services, and nearly two-thirds of consumers report being offered a split pay option within the past year. The US BNPL market hit roughly $70 billion in 2025 alone, according to Richmond Fed data, with global transaction volume reaching $560.1 billion.

Split Pay Credit Score: Why 2026 Changed Everything

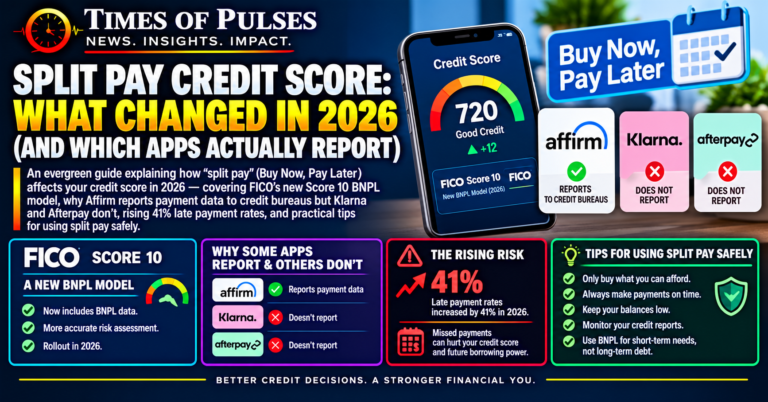
Here’s the core split pay credit score shift: FICO began incorporating BNPL payment data into a new scoring model, FICO Score 10 BNPL, starting in fall 2025. Before this model existed, split pay activity mostly stayed invisible to standard credit scores, meaning on-time payments didn’t help you and, in many cases, missed payments didn’t directly hurt you either. That blind spot is closing, but unevenly, which is exactly what makes this more complicated than a simple yes-or-no answer.

Not Every App Reports the Same Way

This is the detail that trips up most people researching split pay credit score questions: the major BNPL providers handle credit reporting completely differently.

  • Affirm began reporting customer repayment data to Experian and TransUnion in early 2025, meaning Affirm loans can now factor into the new FICO Score 10 BNPL calculation, for better or worse depending on your payment history.
  • Klarna and Afterpay do not currently report payment data to the three nationwide credit bureaus. Afterpay has stated publicly it won’t start reporting until it sees evidence that doing so helps rather than hurts its users.

In practice, this means the exact same split pay habit, four on-time payments for a $200 purchase, could be quietly building your credit history through one app and remaining completely invisible through another.

The Real Split Pay Credit Score Risk Hiding in the Data

While the split pay credit score story sounds relatively low-stakes on the surface, the underlying usage data tells a more concerning story. Late payment rates on BNPL loans climbed to 41% of users in the past year, up from 34% the year before, according to research compiled by DontPayFull. That’s a significant jump, and it matters more now than it used to: once a delinquent split pay account gets sent to collections, it can show up on your credit report and drag your score down regardless of which app you used, since collections agencies report independently of whether the original BNPL provider does.

Deep-subprime borrowers, those with credit scores below 580, are disproportionately exposed here: this group defaulted at a 3.5% rate while making up 45% of all BNPL originations in recent data, suggesting split pay usage skews heavily toward borrowers who can least afford a ding to their credit.

Adding to the risk, the Consumer Financial Protection Bureau rescinded its BNPL consumer protection rule in May 2025, removing dispute rights that had been roughly equivalent to what credit card users receive. That means fewer built-in safety nets if something goes wrong with a split pay purchase.

When Split Pay Actually Makes Sense

None of this means split pay is inherently bad. Used deliberately, for a planned purchase you could pay for outright but prefer to spread across a few weeks, with zero risk of missing a payment, split pay can be a genuinely interest-free way to manage cash flow. The risk profile changes dramatically once you’re juggling multiple overlapping split pay plans across different apps, which is exactly the pattern that correlates with the rising late-payment rates in the data.

What This Means for Your Own Credit

  1. Know which app you’re using before you assume anything about your score. If you’re using Affirm, treat it more like a traditional installment loan for credit purposes; if you’re using Klarna or Afterpay, assume it currently won’t help your score, but a missed payment sent to collections still can hurt it.
  2. Don’t stack multiple split pay plans at once. Losing track of overlapping payment schedules across different apps is the single biggest driver of the missed-payment risk in this data.
  3. This connects directly to broader credit management. The same discipline that matters for managing your credit utilization applies here: predictable, on-time payments protect your score regardless of which specific credit product you’re using.
  4. If you’re still building credit from scratch, split pay isn’t a shortcut. Unlike strategies focused on establishing credit history from zero, most split pay activity still won’t help build your score under current reporting practices, so don’t rely on it as a credit-building tool.
  5. This is part of a bigger shift in how credit scoring itself works. Just as VantageScore’s entry into mortgage lending changed how homebuyers get evaluated, FICO’s new BNPL-aware scoring model is part of a broader modernization of credit scoring that’s still actively evolving.

Bottom Line

Money Under 30’s coverage of this shift captured it precisely: split pay credit score reporting is no longer a settled, ignorable question, it depends entirely on which app you’re using and how disciplined you are about tracking multiple plans. With late payment rates climbing and reduced consumer protections following the CFPB’s rule rescission, the smartest approach is treating every split pay purchase with the same seriousness as a credit card charge, not as a casual checkout feature that exists outside the credit system. Because for a growing number of users, it no longer does.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor or credit counselor for guidance specific to your situation.

AMD Hits $1 Trillion Market Cap: The Milestone That’s Hiding a Warning Sign

0

AMD Hits $1 Trillion Market Cap: The Milestone That’s Hiding a Warning Sign

Advanced Micro Devices just joined one of the most exclusive clubs in the stock market. AMD hits $1 trillion market cap territory for the first time in the company’s history, a milestone that capped off a broader Monday rally, but a closer look beneath the headline number reveals a market that isn’t quite as healthy as the record closes suggest.

AMD Hits $1 Trillion: How It Got There

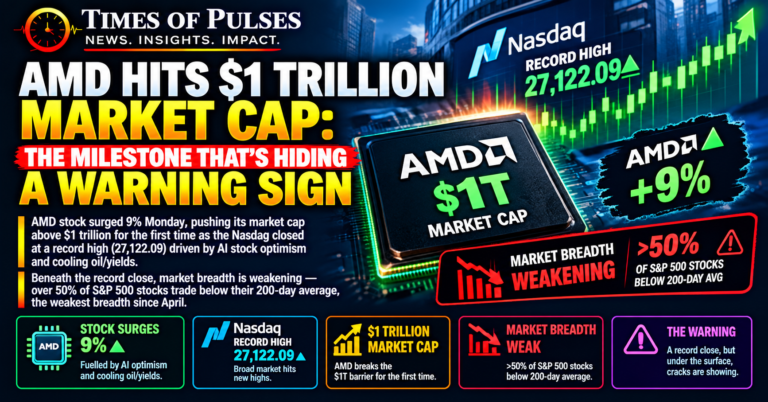
AMD shares surged 9% on Monday, pushing the stock to a record high and pushing the company’s market capitalization above $1 trillion for the first time ever. The move wasn’t isolated, it came as part of a broader rally that saw the Nasdaq Composite jump 2.26% to a record close of 27,122.09, its first record close since June. The S&P 500 climbed 1.49% to 7,764.70, its best single day since early August, while the Dow Jones Industrial Average added 366 points, or 0.71%, to 52,048.83.

The Cooling Oil and Yields Behind the Rally

AMD hits $1 trillion status arrived alongside two macro tailwinds working in the market’s favor simultaneously: oil prices and Treasury yields both cooled off during Monday’s session, easing two of the pressures that had weighed on markets in recent weeks. This continues the pattern we tracked when chip stocks fully erased their AI-slowdown selloff just days earlier, semiconductor names have now gone from recovering lost ground to setting fresh records, all within the same short stretch.

Why AI Stocks Are Leading the Charge Again

Part of what drove Monday’s rally, and AMD hits $1 trillion specifically, was renewed optimism around AI-driven chip demand. Reports pointed to viral popularity around Meta’s new “Muse” AI agent as sparking fresh bets that AI adoption, and the chip demand that comes with it, has real staying power. That optimism rippled beyond US markets too, with AI-linked names like Samsung Electronics rising overseas on the same wave of sentiment. It’s a notable turnaround from where this exact narrative stood just weeks earlier, when AI industry leaders themselves warned the pace of development needed to slow down, triggering a sharp selloff in these same stocks. AMD hitting a trillion-dollar valuation now shows just how quickly sentiment around the AI trade can swing from caution back to enthusiasm.

The Warning Sign Hiding Beneath the Rally

Here’s the part of the AMD hits $1 trillion story that’s easy to miss if you only look at the index-level numbers: market breadth is quietly deteriorating even as headline indexes hit records. More than 50% of S&P 500 stocks are now trading below their 200-day moving average, according to Barchart data, the weakest breadth reading since early April. At the same time, downside volume on the New York Stock Exchange, as a share of total trading volume, has surged to 54%, near its highs for the year.

In plain terms, that means Monday’s rally, including AMD hits $1 trillion headlines, was driven by a relatively small group of large, AI-linked winners, while a majority of individual stocks in the broader market are actually trending weaker underneath the surface. This is exactly the kind of divergence analysts watch closely, because narrow, concentrated rallies have historically proven less durable than broad-based ones.

What This Means for Your Own Portfolio

  1. A record index close doesn’t mean every stock is participating. If your portfolio isn’t concentrated in the same handful of AI-linked mega-caps driving days like this one, don’t assume your own holdings are performing similarly.
  2. Check what’s actually inside your index funds. AMD hits $1 trillion territory partly because AI infrastructure names now carry outsized weight in major indexes, meaning broad market funds have more concentrated exposure to this single narrative than many investors realize.
  3. Weakening breadth is worth tracking, not panicking over. A rising percentage of stocks below their 200-day average is a signal to watch, similar to how we’ve flagged other underlying risk indicators worth monitoring beyond the headline number, not an automatic reason to sell.
  4. Milestone numbers make good headlines, not investment theses. AMD crossing $1 trillion is a genuine achievement, but the decision to hold, buy, or trim any single stock should rest on your own research and risk tolerance, not a round-number milestone alone.

Bottom Line

CNBC’s live coverage of Monday’s session captured both sides of this story clearly: a genuinely record-setting day for major indexes and for AMD specifically, alongside real signs that the rally’s foundation is narrower than the headline numbers suggest. AMD hits $1 trillion is a legitimate milestone reflecting real AI-driven demand, but the deteriorating breadth beneath Monday’s gains is a reminder that even record closes deserve a second look before assuming the broader market is as strong as its headline number.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.
Greenland Stocks Surge 150% Overnight: What’s Really Behind the Rare Earth Rally

Greenland Stocks Surge 150% Overnight: What’s Really Behind the Rare Earth Rally

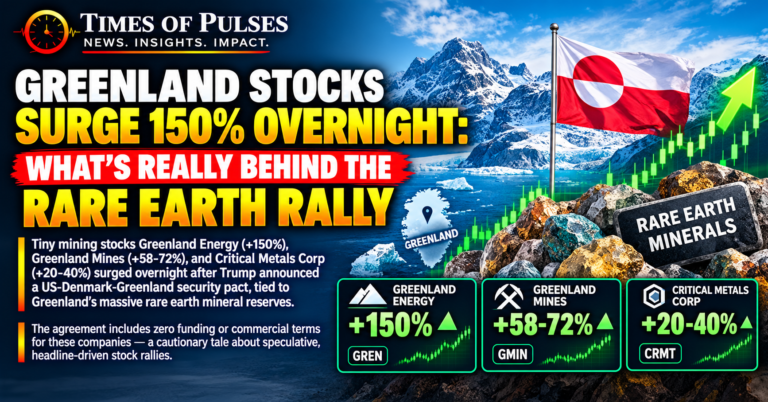
A handful of tiny, little-known mining stocks just did something that stops most investors mid-scroll: they surged well over 100% in a single overnight session. Greenland stocks surge headlines took over trading screens this week after President Trump announced a sweeping US-Denmark security agreement over the Arctic territory, and the story behind the rally is as much about rare earth minerals as it is about geopolitics.

Greenland Stocks Surge: The Numbers That Stopped People Scrolling

The moves were genuinely extreme. Greenland Energy (GLND) soared as much as 150% in overnight and premarket trading, Greenland Mines (GRML) jumped between 58% and 72%, and Critical Metals Corp (CRML) rose anywhere from 20% to 40% depending on the exact moment measured. For context, moves of this size in a single session are typically reserved for tiny biotech stocks on drug trial results, not mining companies reacting to a diplomatic announcement, which is exactly what makes this Greenland stocks surge story worth understanding rather than just watching.

What Actually Triggered the Greenland Stocks Surge

The catalyst was a security pact between the US, Denmark, and Greenland, announced by President Trump via social media on a Friday night. Trump said the agreement would give the US the “complete ability to do what is necessary in Greenland” to secure and defend the territory, adding that Washington would begin developing “a large Military presence” there, at no cost to the US. The deal is expected to be formally signed this week during the United Nations General Assembly, though full details haven’t yet been made public.

This follows months of Trump publicly floating the idea of the US acquiring or even annexing Greenland outright, a self-governing Danish territory. The actual agreement falls well short of that, Danish Prime Minister Mette Frederiksen said the arrangement “respects the sovereignty and territorial integrity” of Denmark, but the Greenland stocks surge reaction shows markets read even a security-only deal as a meaningful signal about US involvement in the region’s resources.

Why Rare Earth Minerals Are the Real Story

Here’s what connects a military security pact to mining stock prices: Greenland holds an estimated 1.5 million tonnes of rare earth reserves, the eighth-largest deposit globally. Rare earth elements are essential inputs for electric vehicles, renewable energy systems, advanced electronics, and defense equipment, and China currently dominates global rare earth processing. Critical Metals Corp, one of the biggest movers in this Greenland stocks surge, holds a 92.5% stake in the Tanbreez rare earth project in southern Greenland, positioning it directly in the path of any US push to diversify rare earth supply away from China.

This ties into a broader theme we’ve been tracking around supply chain and chip-adjacent policy risk, including semiconductor tariff moves aimed at reshoring production. Rare earths and semiconductors sit in the same strategic category for policymakers right now: materials the US wants more control over, and the market for both.

The Important Catch Most Headlines Skip

Before assuming this Greenland stocks surge reflects real business progress, it’s worth being direct about what the agreement actually includes: nothing. No funding, no licenses, no commercial arrangements for any of these three companies were disclosed alongside the security deal. The rally reflects investors betting on future political support, infrastructure investment, and financing opportunities that could follow, not anything that’s actually happened yet. Critical Metals’ own drilling at its flagship site was delayed until winter 2027 amid ongoing regulatory review, a detail that got far less attention than the overnight stock chart.

It’s also worth noting the starting point: heading into this news, GLND and GRML were down roughly 79-88% and 80% respectively for the year, meaning even after this surge, both stocks remain well below where they started 2026. A 150% overnight jump sounds dramatic, but on a stock that had already lost most of its value, it can still leave shares far from a full recovery.

What This Means for Your Own Money

  1. A geopolitical headline moving a stock 100%+ overnight is a volatility signal, not a value signal. These moves reflect speculation about what might happen, not confirmed revenue, contracts, or production.
  2. Check what’s actually been agreed to, not just the stock chart. In this case, zero funding or commercial terms were disclosed, the entire rally is investors pricing in possibilities.
  3. Retail trader enthusiasm isn’t a substitute for due diligence. Online sentiment around these stocks has been described as “extremely bullish,” with talk of short squeezes, exactly the kind of momentum that can reverse as quickly as it built.
  4. If you’re drawn to this kind of speculative story, size the position accordingly. This fits the same category of high-risk, headline-driven trades we discussed when covering oil price volatility investing, appropriate for a small, deliberate allocation, not a core portfolio holding.

Bottom Line

CNBC’s coverage of the deal captured the essential tension in this story well: a real geopolitical agreement triggered a very real stock rally, but the underlying commercial fundamentals, funding, mining permits, actual rare earth production, haven’t changed at all yet. The Greenland stocks surge is a genuine case study in how quickly speculative capital moves on political headlines alone, useful to understand even if you have no plans to buy any of these specific stocks, because the same pattern shows up across markets whenever geopolitics and scarce resources intersect.


This article is for informational purposes only and does not constitute financial or investment advice. Highly speculative stocks carry significant risk of loss. Consult a licensed financial advisor before making changes to your investment portfolio.
Chip Stocks Erase Selloff: How Semiconductors Wiped Out an Entire Week’s Losses in 3 Days

Chip Stocks Erase Selloff: How Semiconductors Wiped Out an Entire Week’s Losses in 3 Days

Just days after top AI executives warned their own industry needed to slow down, sending semiconductor stocks into a sharp selloff, those same stocks have done something remarkable: chip stocks erase selloff territory now describes the entire week, with Thursday’s rally wiping out essentially all of Monday’s losses in a single session.

Chip Stocks Erase Selloff: The Numbers Behind the Comeback

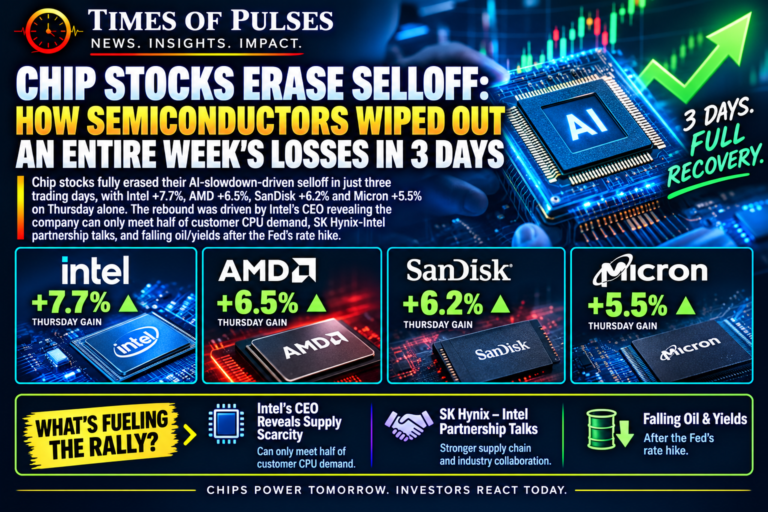
Thursday’s rebound was broad and sharp. Intel jumped 7.7%, AMD rose about 6.5%, SanDisk advanced 6.2%, and Micron climbed 5.5% to close at $975.26, a level that effectively erased the stock’s net loss from Monday’s AI-slowdown shock. The iShares Semiconductor ETF (SOXX) rose roughly 3.4% on the day, with Nvidia gaining 2.5% and Arm jumping 8.6%. For a sector that had been reeling just three trading sessions earlier, this chip stocks erase selloff move represents one of the fastest full reversals we’ve tracked this year.

Why Investors Suddenly Looked Past the AI Slowdown Fears

The chip stocks erase selloff story isn’t really about investors deciding the AI pacing concerns don’t matter, it’s about a different, more immediate story taking over: supply, not demand. Intel CEO Lip-Bu Tan told an AI infrastructure conference that his company can currently meet only about half of customer CPU demand, a striking admission of just how tight chip supply has become across the industry. That kind of scarcity signal tends to be bullish for chipmakers regardless of what’s happening with broader AI safety debates, tight supply generally means pricing power and strong near-term revenue, whatever the longer-term pace of AI development looks like.

This connects directly to the memory shortage dynamic we covered when Sandisk and Micron shares swung wildly on DRAM and NAND scarcity earlier this year, that underlying supply tightness never actually went away, it just got temporarily overshadowed by the AI-slowdown headlines.

A Surprise Partnership Rumor Added Fuel

Adding to the chip stocks erase selloff momentum, Reuters reported that SK Hynix is in exploratory talks with Intel to manufacture memory chips in the United States for the first time. While SK Hynix confirmed only preliminary discussions with no agreement finalized, the possibility alone was enough to send Intel shares higher earlier in the week and extend that momentum into Thursday’s broader rally. A US-based memory manufacturing partnership would be a meaningful shift for an industry that’s been almost entirely concentrated in Asia.

The Macro Backdrop Helped Too

Chip stocks didn’t rally in isolation. Falling oil prices and Treasury yields following the Federal Reserve’s rate hike decision eased broader market anxiety, giving risk assets across the board, not just semiconductors, room to recover. Since data center construction and AI infrastructure spending are notably sensitive to borrowing costs, easing yields directly supports the same chip names that had been under pressure from both the AI-slowdown story and elevated rates simultaneously.

What This Reversal Actually Tells Us

The speed of this chip stocks erase selloff move is itself a useful data point. When a sector can fully recover from a values-based, industry-leadership-driven selloff in just three trading sessions, it suggests the underlying fundamentals, chip demand, supply constraints, and AI infrastructure spending commitments, remain stronger than the initial safety-focused headlines implied. That’s consistent with what we noted when covering Nvidia’s own earnings beat: the AI infrastructure buildout has repeatedly proven more resilient to single news cycles than initial market reactions suggest.

What This Means for Your Own Portfolio

  1. Don’t assume a values-driven selloff means demand is falling. This week showed that AI safety concerns and chip demand fundamentals are genuinely separate stories, a warning about pacing development doesn’t mean fewer chips are actually being ordered.
  2. Supply constraints are often more predictive of near-term stock moves than sentiment. Intel’s admission it can only meet half of CPU demand is the kind of concrete operational detail that tends to matter more than a week of mixed headlines.
  3. Watch how sensitive this sector remains to yields and Fed policy. Chip stocks erase selloff momentum got real help from falling yields this week, a reminder that semiconductor valuations remain tied to macro conditions as much as company-specific news.
  4. Volatility this sharp in both directions argues for position sizing discipline. A sector that can lose and then fully regain double-digit percentages within a week isn’t one to bet the majority of a portfolio on, regardless of which direction the latest headline points.

Bottom Line

Coverage of Thursday’s rally captured the shift clearly: what started the week as an AI-safety-driven selloff ended it as a supply-and-macro-driven rally, with chip stocks erase selloff conditions fully intact by Thursday’s close. The underlying lesson isn’t that the AI slowdown conversation doesn’t matter, lawmakers and industry leaders are still actively debating it, it’s that markets ultimately price chip stocks on demand, supply, and interest rates first, and safety headlines second, at least in the short term.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.