Home Blog Page 3

Stocks to Watch September 2026: 5 Names Sitting at the Center of This Month’s Biggest Stories

Stocks to Watch September 2026: 5 Names Sitting at the Center of This Month’s Biggest Stories

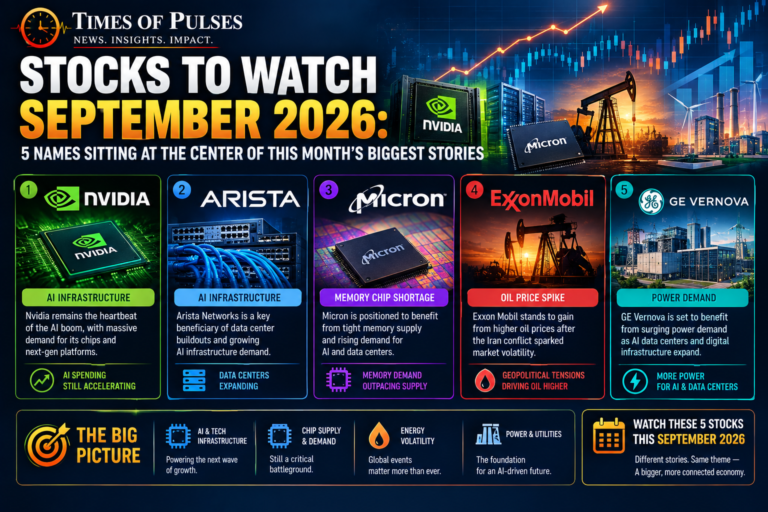
September 2026 has already delivered a strong jobs report that spooked markets, a fresh round of oil price volatility, and a memory chip shortage that refuses to calm down. Rather than picking stocks at random, the smartest place to look for stocks to watch September 2026 is at the companies sitting directly inside these actual news stories, not the ones simply riding general market sentiment.

Stocks to Watch September 2026: Why These Five Made the List

Each of these five names ties directly to a theme already moving markets this month: AI infrastructure spending, the ongoing memory chip shortage, rising oil prices, and the power demands of an AI-driven economy. A similar screen from Caveo FX flagged several of these same names for the same underlying reasons. That’s a deliberate filter. Stocks to watch September 2026 should be companies with a clear, current catalyst, not names picked simply because they’re popular.

1. Nvidia (NVDA) — The AI Bellwether

Nvidia remains the single clearest signal for the entire AI spending boom, and it’s impossible to talk about stocks to watch September 2026 without starting here. We covered how Nvidia’s most recent earnings report broke a year-long pattern of falling stock prices despite beating estimates, with revenue up 106% year over year and guidance well above Wall Street’s forecasts. With hyperscaler capital spending expected to climb toward $1.3 trillion next year, Nvidia’s trajectory continues to set the tone for the broader AI trade heading into the rest of September.

2. Micron Technology (MU) — Riding the Memory Chip Shortage

Memory chips have been one of the most volatile corners of the market this year, and Micron sits right at the center of it. We wrote about the wild swings in Sandisk and Micron shares driven by a genuine DRAM and NAND shortage, a shortage that’s also colliding with new semiconductor tariff proposals from the Commerce Department. That combination, real supply scarcity plus a policy wildcard, is exactly why Micron remains one of the more closely watched stocks to watch September 2026, even for investors who don’t usually follow chip stocks closely.

3. Exxon Mobil (XOM) — Catching the Oil Price Spike

With oil prices climbing sharply after renewed US-Iran military strikes pushed crude toward its biggest weekly gain since July, major producers like Exxon Mobil are positioned to benefit directly. As we discussed when covering how to actually invest in oil price volatility, integrated majors like Exxon tend to see outsized free cash flow once oil trades above roughly $80 a barrel, cash that increasingly flows to dividends and buybacks. That makes Exxon one of the more straightforward stocks to watch September 2026 for anyone looking to track the oil story through an actual company rather than the commodity itself.

4. Arista Networks (ANET) — The AI Infrastructure Pick

Every AI data center needs high-speed networking to actually function, and Arista Networks has become one of the go-to names for that specific piece of the AI buildout. As hyperscalers keep expanding data center capacity to meet AI demand, Arista’s networking equipment sits in a position to benefit regardless of which specific AI model or chipmaker ends up winning the broader race, making it a lower-drama way to stay exposed to the same trend driving Nvidia.

5. GE Vernova (GEV) — Powering the AI Buildout

The AI boom has a physical bottleneck that gets far less attention than chips: electricity. GE Vernova, which spun off from General Electric to focus on power generation and grid infrastructure, is positioned to benefit as data centers drive rising electricity demand across the country. With utilities and grid operators racing to keep up with AI-driven power needs, GE Vernova rounds out this list of stocks to watch September 2026 by representing a completely different layer of the same underlying trend.

What Ties These Stocks to Watch September 2026 Together

Look closely and a pattern emerges: four of these five names, Nvidia, Micron, Arista, and GE Vernova, are different layers of the exact same AI infrastructure buildout, chips, memory, networking, and power. Exxon is the outlier, tied instead to the geopolitical oil story, but it shares something important with the other four: each one is reacting to a real, current, verifiable news event rather than pure speculation. That’s the actual filter worth applying to any list of stocks to watch September 2026 you come across this month.

What This Means for Your Own Portfolio

  1. Don’t buy a stock just because it’s “in the news.” Being mentioned in stocks to watch September 2026 roundups, including this one, is a reason to research further, not a reason to buy immediately.
  2. Notice the concentration risk. If your portfolio already holds broad tech index funds, you likely have overlapping exposure to several of these AI infrastructure names already, buying them individually could mean doubling up more than you realize.
  3. Match volatility to your time horizon. Chip and AI infrastructure stocks have moved sharply in both directions this year; money you’ll need within the next year or two shouldn’t be concentrated in names this volatile.
  4. Watch the news driving each stock, not just the price. The whole point of this list is that these five companies are tied to specific, ongoing stories, if the underlying story changes, so does the case for watching the stock.

Bottom Line

This month’s stocks to watch September 2026 aren’t random picks, they’re the companies sitting directly inside the biggest financial stories already unfolding: the AI infrastructure boom, the memory chip shortage, and renewed oil price volatility. Whether any of these five belongs in your own portfolio depends on your risk tolerance and time horizon, but understanding why each one is being talked about this month is a more useful exercise than simply copying a stock list.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.
Jobs Report Rate Hike Odds: Why a “Great” Jobs Report Just Made Wall Street Panic

0

Jobs Report Rate Hike Odds: Why a “Great” Jobs Report Just Made Wall Street Panic

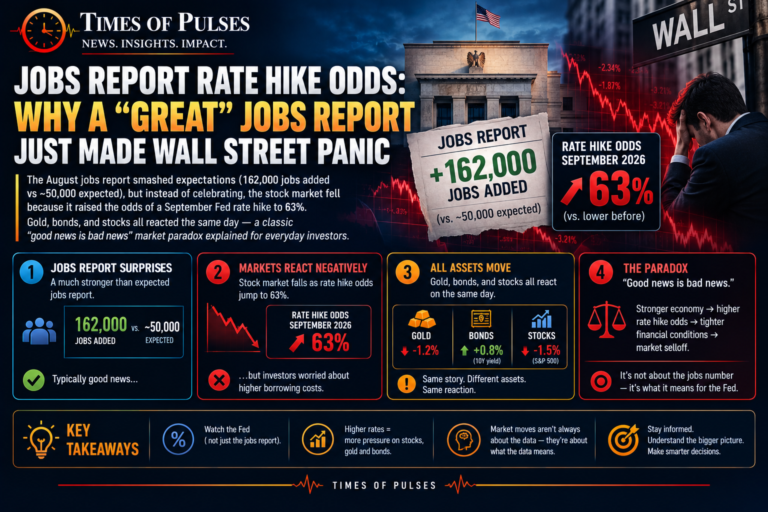
Here’s something that confuses almost everyone the first time they see it happen: the US just posted a genuinely strong jobs report, and the stock market fell anyway. That’s not a typo. On Friday, jobs report rate hike odds jumped sharply, and it’s exactly why good economic news can sometimes be bad news for your portfolio.

What the Jobs Report Actually Showed

The August jobs report was, by almost any measure, strong. US employers added 162,000 jobs, more than three times what economists were expecting, with forecasts sitting in the 45,000 to 55,000 range. Unemployment held steady at 4.1%, and the government also revised July’s initially negative reading up into positive territory, meaning the labor market wasn’t just strong in August, it was stronger throughout the summer than initially reported.

Normally, a report like this would be pure good news. Instead, it triggered the jobs report rate hike odds spike that sent stocks lower on the same day.

Why a Strong Jobs Report Sent Stocks Falling

This is the part that trips people up: a hot jobs report makes the Federal Reserve less likely to cut interest rates, and in some cases, more likely to consider raising them. Treasury yields jumped immediately after the report, and Schwab’s market update noted that jobs report rate hike odds for the Fed’s September meeting climbed to 63%, according to Bloomberg data, reversing a decline in those odds that had been building earlier in the week.

Higher rate-hike odds work against stocks for a straightforward reason: higher interest rates make borrowing more expensive for companies, make bonds more competitive with stocks for investor money, and reduce what future company earnings are worth in today’s dollars. That’s exactly why the S&P 500 fell 0.38% to 7,719, the Dow dropped 0.51% to 53,414, and the Nasdaq slipped 0.29% to 26,507 on a day when the actual economic data was unambiguously positive.

The Fed Pressure Angle Making This Louder Than Usual

This jobs report rate hike odds shift is landing amid a specific backdrop worth knowing about: President Trump has been publicly turning up pressure on Fed Chair Kevin Warsh as a potential rate hike looms, adding a political dimension to what would otherwise be a purely data-driven Fed decision. That pressure doesn’t change the underlying economics, but it does mean this particular Fed decision is getting more public attention than a typical rate call.

Gold, which tends to fall when rates are expected to rise, dropped 1.14% to $4,429 an ounce the same day, continuing the pattern we covered when gold’s record rally partly reversed after Fed Chair Warsh’s Jackson Hole speech. The 10-year Treasury yield, which had already been climbing for weeks, rose further to 4.789%, and the dollar index strengthened to 99.157 as traders priced in a higher chance of tighter monetary policy ahead.

Why This “Good News Is Bad News” Pattern Keeps Happening

The jobs report rate hike odds reaction makes more sense once you separate two different questions markets are constantly weighing: is the economy doing well, and is monetary policy about to get tighter or looser? For most of this year, investors have been hoping for a cooling labor market specifically because it supports the case for rate cuts. A report this strong flips that calculus, and markets react to the policy implication, not just the standalone economic headline.

This isn’t a new pattern, it’s one of the most consistent dynamics in how markets process economic data, but it catches new investors off guard nearly every time a “good” report causes a “bad” market day.

What This Means for Your Own Money

  1. Don’t read market direction as a verdict on the economy itself. A falling stock market on a strong jobs report doesn’t mean the economy is weakening, it means investors are repricing how the Fed might respond.
  2. Rate-sensitive parts of your finances are worth watching closely right now. With jobs report rate hike odds elevated, mortgage and borrowing costs could stay higher for longer than markets had been hoping just a week ago.
  3. A single data point rarely determines the actual Fed decision. The September meeting is still weeks away, and additional inflation and employment data will factor in before anything is finalized.
  4. Keep an eye on long-term yields, not just the headline stock move. The 10-year Treasury yield’s climb toward multi-year highs has been a recurring theme all year, and jobs data like this is a direct input into where that yield goes next.

Bottom Line

The jobs report rate hike odds jump this week is a textbook example of why “the economy is strong” and “stocks are up” aren’t the same statement. A genuinely good August jobs report pushed the odds of a September rate hike to 63%, and that shift, not the jobs number itself, is what sent stocks, gold, and bond prices moving on Friday. Understanding that distinction is one of the more useful mental models for making sense of market reactions that otherwise look completely backwards.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.
Oil Price Volatility Investing: Everyone’s Losing Money on Crude’s Swings Except These Investors

Oil Price Volatility Investing: Everyone’s Losing Money on Crude’s Swings Except These Investors

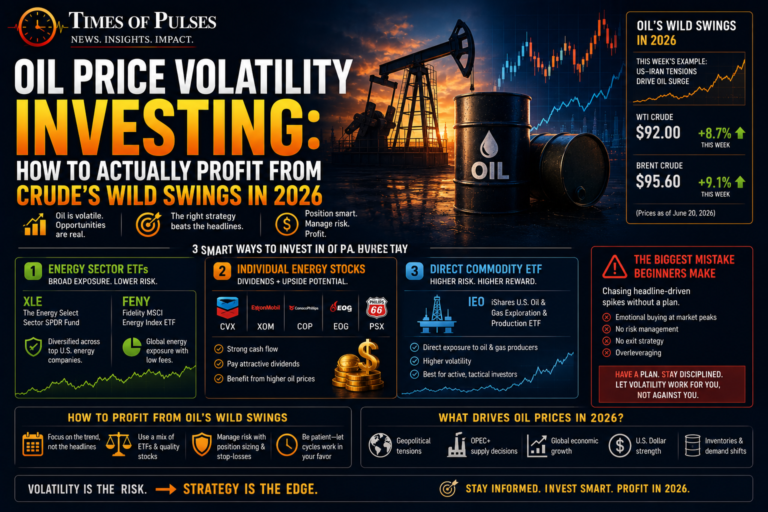
Every time oil prices spike on fresh Middle East headlines, like the surge we just covered after renewed US-Iran strikes this week, the same question comes up: is there an actual way to benefit from this, or is it just something that costs more at the pump? The honest answer is that oil price volatility investing is a real, accessible strategy, but doing it well means understanding which approach fits your risk tolerance, not just buying the first oil-related ticker you see.

Why Oil Price Volatility Investing Isn’t About Predicting the Next Headline

The biggest mistake people make when they hear “oil is spiking, how do I profit” is trying to time the next geopolitical event. Nobody can reliably predict whether the next round of US-Iran tension eases in a week or escalates further, and we’ve watched that exact story swing both directions repeatedly this year. Real oil price volatility investing isn’t about calling the next headline correctly, it’s about choosing a structure that benefits from the underlying trend, elevated and unstable oil prices, regardless of which specific week the news breaks.

Option 1: Energy Sector ETFs — The Easiest Starting Point

For most people, energy sector ETFs are the simplest and lowest-risk way to get exposure to rising oil prices without picking individual companies. The Energy Select Sector SPDR Fund (XLE) holds major producers like ExxonMobil and Chevron, and it’s returned roughly 31% year-to-date and about 44% over the past year, while charging a tiny 0.08% expense ratio and paying a dividend yield near 2.6%. The Fidelity MSCI Energy Index ETF (FENY) tracks similarly, around 31% year-to-date, but casts a wider net across mid and small cap energy names at an even lower cost.

What makes ETFs like these appealing for oil price volatility investing specifically is that you’re buying real companies with real cash flow, not a bet on the commodity price itself. When oil climbs above roughly $80 a barrel, producers like Exxon and Chevron generate outsized free cash flow that increasingly flows to dividends and buybacks, meaning you get paid to hold through the swings rather than needing to guess the next move perfectly.

Option 2: Individual Energy Stocks for Dividend Income

If you’d rather pick specific companies than buy the whole sector, major integrated oil producers and refiners offer a more direct route into oil price volatility investing, typically with attractive dividend yields on top. This approach requires more research since individual stocks carry company-specific risk on top of oil price risk, a refinery outage or bad earnings quarter can hurt a single stock even while oil prices climb. It’s a reasonable middle ground for investors who want more control than an ETF but aren’t ready for the volatility of direct commodity exposure.

Option 3: Direct Oil ETFs — The Riskier, More Amplified Play

For investors specifically chasing crude price moves rather than company performance, funds like the iShares U.S. Oil & Gas Exploration & Production ETF (IEO) strip out the stable integrated majors and lean almost entirely into upstream producers whose earnings move nearly tick for tick with crude. IEO has returned about 33% year-to-date, ahead of the broader energy ETFs, but Yahoo Finance’s coverage of energy ETFs notes it also carries the sharpest downside risk if oil prices ease back toward the EIA’s longer-term forecasts.

There’s an important caution specific to this corner of oil price volatility investing: futures-based commodity ETFs (funds that track the oil price directly rather than owning company shares) can quietly lose value over time even when oil prices are flat, due to a structural cost called contango from constantly rolling futures contracts. That’s a genuinely important distinction beginners often miss, an ETF holding oil company shares and an ETF holding oil futures contracts can behave very differently even when the news is identical.

The Mistake Most Beginners Make

The most common error in oil price volatility investing is treating every price spike as a trading signal rather than understanding the difference between a short-term news reaction and a genuine multi-week trend. We saw this exact pattern play out when oil surged on renewed Iran conflict this week, prices moved sharply, but shipments through the Strait of Hormuz never actually stopped, meaning the physical supply story hadn’t changed as dramatically as the price action suggested. Chasing every headline-driven spike tends to mean buying near short-term peaks and selling out during the inevitable pullback, the opposite of what actually builds wealth.

What This Means for Your Own Money

  1. Match your approach to your actual risk tolerance. Energy ETFs like XLE offer steadier, dividend-supported exposure; direct commodity or upstream-heavy funds like IEO amplify both the gains and the losses.
  2. Don’t put money into oil price volatility investing that you’ll need in the next year or two. Energy remains one of the more cyclical sectors, and a position bought during a spike can sit underwater for months if tensions ease faster than expected.
  3. Treat this the same way we’ve discussed hedging against broader economic uncertainty. Just as Ray Dalio recommended gold as a portfolio hedge against a specific risk rather than his entire portfolio, energy exposure works best as a measured allocation, not an all-in bet triggered by one news cycle.
  4. Keep the cash you’re not investing working too. Whatever portion of your portfolio you keep in reserve for opportunities like this deserves to sit in a high-yield savings account rather than earning nothing while you wait.

Bottom Line

Oil price volatility investing is a legitimate, accessible way to turn the same headlines rattling markets into portfolio exposure, but the method matters as much as the timing. Energy ETFs like XLE and FENY offer a steadier, dividend-supported way in; direct commodity-linked funds offer sharper upside and downside for investors who understand the added risk. Whichever route fits your situation, the real edge isn’t predicting the next US-Iran headline, it’s having a structure in place before the next spike happens rather than scrambling to react once it does.


This article is for informational and educational purposes only and does not constitute financial or investment advice. Energy markets and geopolitical events are unpredictable; consult a licensed financial advisor before making investment decisions.

Oil Prices Iran Strikes: Crude Heads for Its Biggest Weekly Gain Since July

Oil Prices Iran Strikes: Crude Heads for Its Biggest Weekly Gain Since July

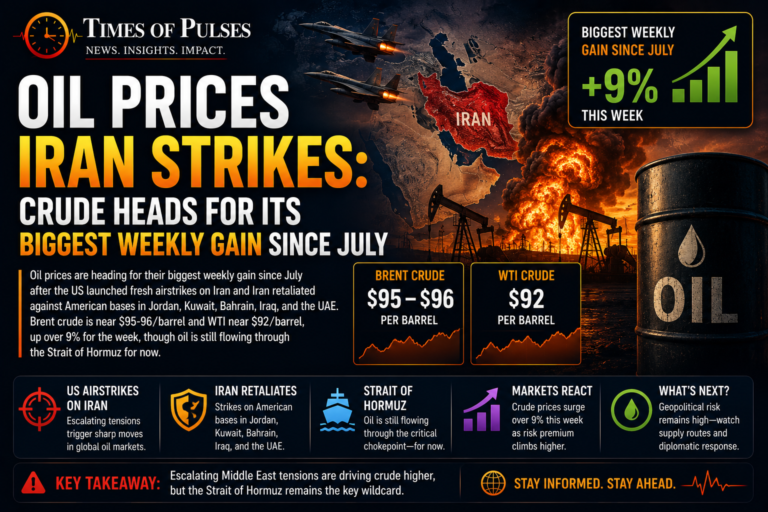
Just when the Strait of Hormuz standoff seemed to be settling into an uneasy calm, it flared up again, and this time oil prices are moving harder than they have in weeks. Oil prices Iran strikes headlines are back at the top of financial news this week after the US carried out a fresh wave of airstrikes against Iranian targets, and crude is now on pace for its biggest weekly gain since July.

What Actually Happened This Week

After roughly a month of relative calm following the deadlock we covered when Iran’s demands clouded the outlook for reopening the Strait of Hormuz, the US launched a new round of airstrikes against Iranian targets over the weekend and into this week. Iran’s Revolutionary Guard retaliated by targeting American military positions across the region, including bases in Jordan, Kuwait, Bahrain, Iraq, and the UAE. This oil prices Iran strikes escalation marks a genuine reescalation of a conflict that markets had, for a few weeks, started to price as cooling off.

President Trump said the latest attacks on Iran would be “short-lived,” but also reiterated that the US remains prepared for further strikes and maintained that the US controls access through the Hormuz waterway. That combination, a promise of restraint alongside a readiness for more action, is exactly the kind of uncertainty that keeps this oil prices Iran strikes story moving markets day to day.

The Numbers: How Far Oil Has Actually Moved

The price action has been sharp. Bloomberg’s oil market coverage this week noted that Brent crude, the global benchmark, climbed to around $95 to $96 a barrel this week. West Texas Intermediate, the US benchmark, pushed toward $92 a barrel and was up more than 9% for the week alone, putting oil on track for its largest weekly gain since July. Over the past month, crude prices are up close to 13% to 20% depending on the benchmark, and prices now sit more than 40% higher than this time last year.

Adding to the pressure, US crude inventories fell by 4.5 million barrels last week, the first inventory drop since late July, a sign that supply is tightening even as the oil prices Iran strikes conflict adds fresh uncertainty on top of already-reduced stockpiles.

Why the Strait of Hormuz Keeps Driving This Story

The Strait of Hormuz carries roughly a fifth of the world’s oil supply, which is exactly why any renewed hostility near it moves prices more sharply than most other geopolitical headlines. Despite this week’s exchange of strikes, crude shipments have continued passing through the strait at an estimated average of 8 million barrels a day, meaning actual physical supply hasn’t been cut off, even as the oil prices Iran strikes conflict raises the risk that it eventually could be.

That distinction matters. Markets aren’t just pricing in what’s happening today, they’re pricing in the probability of a worse disruption tomorrow. As long as shipments keep flowing despite the fighting, prices can remain volatile without spiking into true crisis territory, but that calculation can change quickly if either side escalates further.

Why This Keeps Happening in Cycles

If this pattern feels familiar, that’s because it is. We’ve now tracked this same dynamic multiple times this year: prices spike on fresh hostilities, ease when diplomatic hope resurfaces, then spike again when that hope fades or fighting resumes. The oil prices Iran strikes situation this week is simply the latest cycle in a conflict that has repeatedly refused to settle into either a clean resolution or a sustained crisis.

Forecasters are reflecting that same uncertainty in their outlooks. Current 30-day projections for WTI crude range anywhere from roughly $70 to $102 a barrel for September 2026, an unusually wide band that reflects just how much depends on factors still very much in motion, including the trajectory of the Iran conflict, the Federal Reserve’s increasingly hawkish tone, and the possibility of a September rate move.

What This Means for Your Wallet

  1. Don’t treat this week’s gas price as a stable baseline. With oil prices Iran strikes headlines shifting sentiment day to day, the price at the pump this week may look meaningfully different in two or three weeks, in either direction.
  2. Build a buffer into your fuel and travel budget rather than trying to time it. We’ve covered this exact approach before when gas prices were swinging earlier this year, and the same logic applies now: a small cushion beats trying to guess which week will be cheap.
  3. Watch your broader budget, not just gas. Energy costs ripple into everything from grocery delivery fees to airfare, and if your household is already feeling paycheck pressure, rising fuel costs are one more variable worth planning around rather than being surprised by.
  4. If you hold energy stocks or broad index funds, expect continued volatility, not a clean trend in either direction, for as long as this conflict stays unresolved.

Bottom Line

The oil prices Iran strikes story is back at the center of energy markets this week, with crude on pace for its biggest weekly gain since July after a fresh round of US airstrikes and Iranian retaliation. Actual oil shipments through the Strait of Hormuz haven’t stopped, which is keeping this a volatility story rather than a full supply crisis for now, but the wide range in current forecasts shows just how much uncertainty remains. As with every earlier chapter of this conflict, the safest financial move isn’t trying to predict the next headline, it’s building enough flexibility into your budget to absorb whichever way prices move next.


This article is for informational and educational purposes only and does not constitute financial or investment advice. Geopolitical events and energy markets are unpredictable and can change rapidly; consult a licensed financial advisor before making investment decisions.

Save or Pay Off Debt First? Why September 2026 Makes This an Unusually Easy Call

0

Save or Pay Off Debt First? Why September 2026 Makes This an Unusually Easy Call

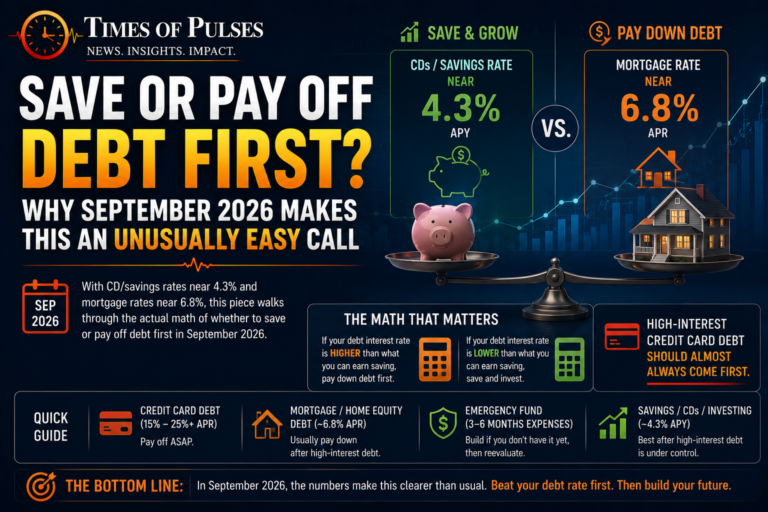
If you’ve got some extra cash and you’re not sure whether to stash it in savings or throw it at debt, the numbers right now actually make this decision clearer than it’s been in years. The question of whether to save or pay off debt first always depends on the math, and this September, that math has a real gap in it worth understanding before you decide where your next dollar goes.

The Rate Gap Driving This Question in 2026

Two things are true at the same time right now, and together they’re exactly why the save or pay off debt question matters more than usual. First, savings accounts and CDs are paying some of the best rates in years, with top 18-month CDs currently offering up to 4.35% APY. Second, borrowing costs on things like mortgages haven’t come down nearly as much, with the average 30-year fixed mortgage sitting around 6.76% APR as of early September. That’s a real gap between what you can earn on cash and what you’re paying to borrow it, and it’s the whole reason the save or pay off debt calculation isn’t as simple as “debt is always bad.”

Why Savings Accounts Are Paying More Than Usual

Right now, some of the strongest CD offers include an 18-month CD from Bread Savings at 4.35% APY and comparable 18-month and 2-year CDs from Marcus by Goldman Sachs at 4.3% APY, according to Yahoo Finance’s roundup of current CD rates, both well above what savings accounts paid just a few years ago. These elevated rates are a direct result of where the Federal Reserve has kept its benchmark rate this year, and they’re part of why the save or pay off debt decision genuinely depends on what kind of debt you’re comparing it to.

Why Borrowing Costs Are Also Climbing

At the same time, borrowing has gotten more expensive on the mortgage side specifically. The average 30-year fixed mortgage rate was running around 6.759% (6.819% APR) in early September, with 20-year fixed loans near 6.65% and 15-year fixed loans closer to 6.12%. Part of what’s pushing rates up is the bond market: the 10-year Treasury yield, which mortgage rates track closely, climbed to around 4.81% this week, its highest level since November 2023, driven by renewed geopolitical tensions and concerns about government borrowing. That combination is exactly why the save or pay off debt question doesn’t have one universal answer, it depends entirely on which specific rate you’re comparing your savings yield against.

When It Actually Makes Sense to Save or Pay Off Debt

Here’s the actual rule of thumb: compare the interest rate on your debt to what you can earn on savings. If a CD is paying 4.3% and your mortgage is at 6.76%, you come out ahead paying down the mortgage faster in strict interest-rate terms, since you’re avoiding a 6.76% cost rather than earning a 4.3% return. But that math flips for lower-rate debt. If you have a car loan or an older mortgage locked in below 4%, parking extra cash in a high-yield CD or savings account instead of paying that debt down early is often the better move mathematically, since you’re earning more than you’d save.

This is really the core of the save or pay off debt decision: it’s not about debt being good or bad in the abstract, it’s about which number is bigger.

The Exception: High-Interest Debt

There’s one place where the save or pay off debt question isn’t close at all: credit cards and other high-interest consumer debt. With average credit card APRs still running well above 20%, no CD or savings account anywhere is going to out-earn that. If you’re carrying a credit card balance, that debt should come before building savings almost every time, regardless of how attractive today’s CD rates look.

We’ve written before about how a growing share of Americans can only manage their credit card minimum payments, and this rate gap is part of why that trap is so costly, high-interest debt compounds against you faster than almost any savings account can compound in your favor.

What This Means for Your Own Money

  1. Line up your actual interest rates side by side. The save or pay off debt decision isn’t guesswork, it’s a direct comparison between your debt’s interest rate and your best available savings yield.
  2. Don’t ignore the bigger economic backdrop. With Treasury yields sitting at levels not seen since 2007 on the long end and mortgage rates following suit, borrowing costs across the board are elevated right now, not just on new mortgages.
  3. Job market softness adds a reason to keep some cushion. Private payroll growth slowed to just 38,000 jobs in August, the weakest reading since January, a reminder that an emergency fund still matters even while you’re weighing the save or pay off debt tradeoff.
  4. Remember this ties into the bigger affordability picture. We’ve covered how housing costs have become the top financial worry for young Americans, and today’s mortgage rates are a direct part of that story if you’re weighing paying down an existing home loan faster.

Bottom Line

The save or pay off debt question isn’t a matter of financial philosophy, it’s simple math that changes based on the specific rates in front of you. Right now, with CDs paying north of 4% and mortgage rates near 6.8%, higher-rate debt still generally wins the comparison, while low-rate debt and healthy savings can comfortably coexist. The one rate that changes nothing about this calculation is high-interest credit card debt, which should almost always come first no matter what today’s savings accounts are offering.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making changes to your personal finances.

SBA Loan Rates 2026 Just Hit Their Lowest Level Since 2022 — Here’s What That Means for Your Business

0

SBA Loan Rates 2026 Just Hit Their Lowest Level Since 2022 — Here’s What That Means for Your Business

If you’ve been putting off financing your small business because of high interest rates, the math just changed. SBA loan rates 2026 have dropped to their lowest ceiling in years, and a separate fee waiver could make borrowing even cheaper for certain business owners. Here’s exactly where the numbers stand right now, why they fell, and what the tariff headlines happening at the same time mean for your bottom line.

SBA Loan Rates 2026: The Numbers Right Now

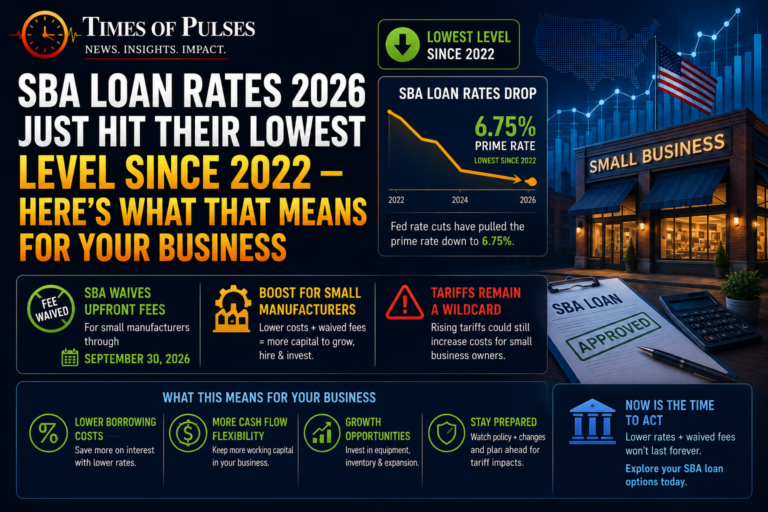
The prime rate, the benchmark most business loans are priced against, currently sits at 6.75%, the lowest level since late 2022. That’s a meaningful drop from the 8.50% prime rate that held for roughly 15 months through early 2024.

Here’s how that translates into actual SBA loan rates 2026:

  • SBA 7(a) variable loans over $350,000: capped at 9.75%, down from around 11.50% in 2024
  • SBA 7(a) variable loans $50,000 to $350,000: capped at 10.75%
  • SBA 7(a) fixed-rate loans: 11.75% to 14.75%
  • SBA 504 loans: 5% to 7%
  • SBA microloans: 8% to 13%

For comparison, a standard bank term loan currently runs 6.80% to 11.00%, and a business line of credit typically falls between 8.00% and 14.00%. SBA-backed products remain some of the cheapest financing small business owners can access, and SBA loan rates 2026 are now at their most favorable point in roughly three years.

Why SBA Loan Rates 2026 Fell This Much

The drop traces directly back to the Federal Reserve. The Fed cut rates three times in September, October, and December of 2025, bringing the federal funds target down to 3.50%–3.75% and pulling the prime rate down alongside it. Since then, the Fed has held steady through its January, March, April, and June 2026 meetings, meaning SBA loan rates 2026 have stayed at this lower level for months rather than being a brief dip.

Because SBA 7(a) loans are priced as prime plus a lender spread, capped at specific percentage points depending on loan size, that 175-basis-point decline in the prime rate flows fairly directly into what business owners actually pay. This is the lowest SBA rate environment since 2022, according to lender data tracking these products.

A New Fee Waiver on Top of Lower Rates

Small manufacturers got an additional break layered on top of falling SBA loan rates 2026. The SBA has waived upfront fees for manufacturing-related loans through September 30, 2026: 7(a) manufacturing loans up to $950,000 now carry a 0% upfront fee, and 504 manufacturing loans have both the upfront fee and annual service fee reduced to 0%. SBA Administrator Kelly Loeffler framed the move as part of an effort to help “job creators expand production and train and hire more U.S. workers,” according to the agency’s announcement.

For a manufacturer taking out a loan near that $950,000 ceiling, skipping the upfront guarantee fee alone, which NerdWallet notes can otherwise run up to 3.75% of the loan amount, adds real savings on top of the already-lower SBA loan rates 2026.

Tariffs Are the Wildcard

Cheaper financing is only half the picture for small business owners right now. On the cost side, the picture is murkier. We recently covered the semiconductor tariff framework the Commerce Department is developing, and that’s just one piece of a broader tariff environment that’s been raising input costs across manufacturing, retail, and import-dependent small businesses throughout 2026.

Lower SBA loan rates 2026 make it cheaper to borrow, but tariffs can raise the cost of the equipment, materials, and inventory that loan is meant to finance in the first place. We’ve also written about how tariff-related savings and refunds have tended to land with large companies rather than flowing back down to smaller businesses or consumers, which is worth keeping in mind if you’re counting on tariff relief to offset rising costs.

What This Means for Your Small Business

  1. If you’ve been waiting for a better rate environment, this is close to as good as it’s been in years. SBA loan rates 2026 sitting near a three-year low is a real, structural change, not just short-term noise.
  2. Manufacturers specifically should look at the fee waiver before it expires. The 0% upfront fee window closes September 30, 2026, so timing matters if this applies to your business.
  3. Don’t finance a purchase without factoring in tariff exposure. If your business imports equipment, components, or inventory, price in the possibility of higher costs on the other side of the loan, not just the interest rate itself.
  4. Shop the loan type, not just the headline rate. SBA 504 loans (5-7%) can be meaningfully cheaper than SBA 7(a) loans depending on what you’re financing, and eligibility rules differ between the two.

Bottom Line

SBA loan rates 2026 falling to their lowest point since 2022, combined with a temporary fee waiver for manufacturers, genuinely improves the financing side of running a small business right now. But it’s only one half of the equation. With tariff policy still evolving and input costs an open question for many industries, the smarter move is to treat cheaper borrowing as an opportunity to plan carefully, not a green light to spend without checking how the cost side of your business might shift over the next year.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making changes to your business’s finances.

Chip Tariffs 2026 Are Coming — Here’s What They Could Mean for Your Next Phone or Laptop

0

Chip Tariffs 2026 Are Coming — Here’s What They Could Mean for Your Next Phone or Laptop

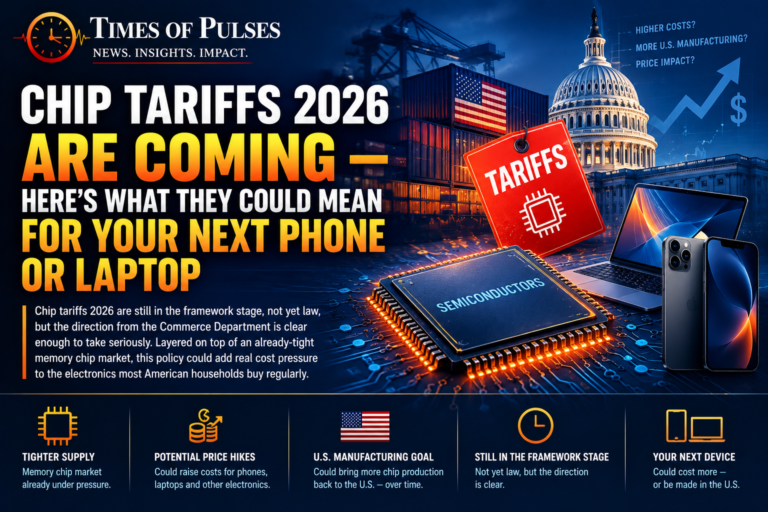
The Trump administration just confirmed something tech buyers should be paying attention to. On September 2, Commerce Secretary Howard Lutnick told CNBC that the White House is actively developing a tariff framework specifically targeting semiconductors, and that chipmakers already know it’s coming. These chip tariffs 2026 plans arrive at the worst possible moment for consumers, right as memory chip shortages are already pushing device prices higher on their own.

What Lutnick Actually Said About Chip Tariffs 2026

Lutnick confirmed a Politico report from the previous week that the administration had been quietly considering the move. Speaking on CNBC, he described the coming approach as targeted rather than blanket, saying the goal is to reward domestic manufacturing: “if you build here, you don’t pay, but if you don’t build here, expect to pay to enter the greatest market in the world.” He added that the administration expects semiconductor production to shift back to the United States as a result.

The exact rate, timeline, and scope of these chip tariffs 2026 haven’t been made public yet. But the direction is now unmistakable: companies that manufacture chips overseas and sell into the U.S. market should expect to pay more to do so, and some of that cost is likely to land on the products you buy.

Why This Is Landing at a Bad Time

If this news feels familiar, it should. We’ve been covering a related story for weeks: a global memory chip shortage that’s already driving up the cost of components inside nearly every phone, laptop, and PC on the market. J.P. Morgan has estimated DRAM prices could climb more than 400% between 2024 and the end of 2026, a trend nicknamed “chipflation.” Chip tariffs 2026, layered on top of a shortage that’s already tightening supply, could compound the pressure on consumer electronics prices rather than offset it.

This isn’t the first time chip-related news has rattled markets this year either. Back in the spring, we covered how a single Chinese chip breakthrough report was enough to trigger a global market selloff, a reminder of just how sensitive the entire tech sector has become to anything touching semiconductor supply chains. Chip tariffs 2026 are a policy-driven version of that same sensitivity: a single Commerce Department announcement can move chipmaker stocks and consumer prices in the same news cycle.

The Winners and Losers of Chip Tariffs 2026

Companies that already manufacture chips domestically stand to benefit the most from this policy shift, since Lutnick’s framework explicitly exempts companies that “build here.” That’s part of why some memory chip makers have had such a strong run this year. We wrote about how one overlooked chipmaker’s stock rallied more than 700% as memory demand surged, and a domestic-manufacturing carve-out in chip tariffs 2026 could add another tailwind for U.S.-based producers specifically.

On the other side, companies that rely heavily on overseas chip fabrication, and by extension, the consumers who buy their finished products, are the ones more likely to feel the cost of these tariffs. Semiconductors sit inside far more than just computers and phones, they’re in cars, appliances, and virtually every piece of modern consumer electronics, which means the reach of chip tariffs 2026 could extend well beyond the tech aisle.

The Bigger Market Backdrop

Chip tariffs 2026 aren’t happening in isolation. They’re landing during a week when the benchmark 10-year Treasury yield hit 4.814%, its highest level since November 2023, and private payrolls grew by just 38,000 jobs in August, the slowest pace since January and below economist expectations. Renewed U.S.-Iran hostilities have also pushed oil prices higher and added another layer of uncertainty to markets already digesting rising yields and a cooling labor market.

None of that changes the tariff story directly, but it does mean chip tariffs 2026 are arriving while consumers are already dealing with a mix of higher borrowing costs, a softening job market, and elevated energy prices. Extra cost pressure on electronics is not landing on especially strong footing for household budgets right now.

What This Means for Your Own Money

  1. If you’re planning a major electronics purchase, timing may matter more this year. Between chipflation and the possibility of new tariffs, prices on phones, laptops, and other chip-heavy devices are more likely to drift higher than lower over the coming months.
  2. Watch how this interacts with existing consumer costs. We’ve previously covered how tariff revenue has tended to flow to large companies rather than back to consumers, so don’t assume a “build here” exemption automatically translates into savings at checkout.
  3. This is a sector-specific risk, not a reason to panic-sell broad holdings. If you hold index funds or tech ETFs, you already have some exposure to how chip tariffs 2026 play out, but that’s different from needing to make a dramatic portfolio change today.
  4. No official rate or start date exists yet. Treat “chip tariffs 2026” as a developing policy story for now, worth watching closely, but not yet a finalized cost you can budget around precisely.

Bottom Line

Chip tariffs 2026 are still in the framework stage, not yet law, but the direction from the Commerce Department is clear enough to take seriously. Layered on top of an already-tight memory chip market, this policy could add real cost pressure to the electronics most American households buy regularly. Whether it ultimately pushes more chip manufacturing back to the U.S., as the administration hopes, or simply raises prices in the meantime, is the question worth watching over the next few months.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making changes to your investment portfolio.
Gold Price Drop Wipes Out Part of Its Best Month in Over 100 Years

0

Gold Price Drop Wipes Out Part of Its Best Month in Over 100 Years

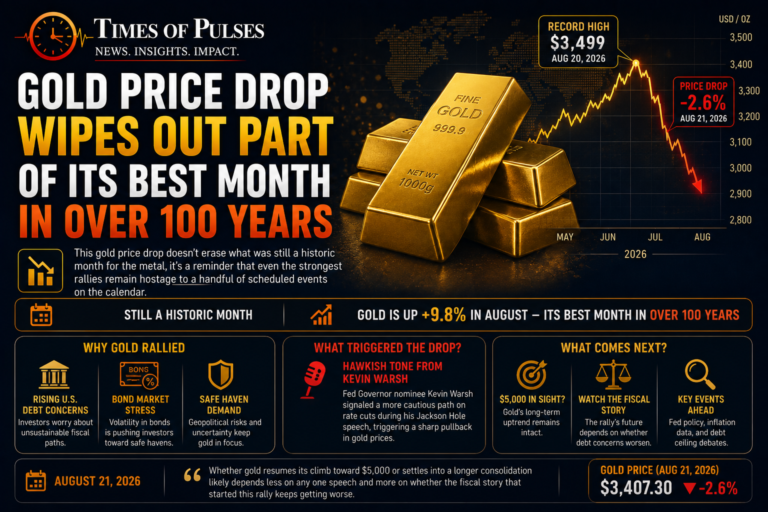
Gold was on track for something historic this August. Then Federal Reserve Chair Kevin Warsh opened his mouth at Jackson Hole, and roughly 3% of the gain vanished within a day. This gold price drop after the Jackson Hole speech is a reminder of just how sensitive even a record-breaking rally can be to a single sentence from the right person.

The Gold Price Drop Followed a Historic August Run

Heading into this week, gold was up about 14% for the month of August alone, on pace to be the metal’s strongest single month in more than a century. On Tuesday, spot gold touched a three-month high of $4,696.18 an ounce, putting it within striking distance of the psychologically huge $5,000 level that bulls have been eyeing for months. For a metal that typically moves in single-digit percentages over an entire year, a 14% monthly gain is an extraordinary move, and it had investors, including billionaire Ray Dalio, pointing to gold as one of the few places to hide from a deteriorating fiscal picture in Washington.

What Triggered the Rally in the First Place

The spark behind gold’s run wasn’t random. It traces back to the same story we covered when Ray Dalio issued his debt crisis warning: the U.S. Treasury’s announcement that it would sharply increase buybacks of long-dated government bonds. Investors read that move as a sign of stress in the bond market, and money poured into gold as a hedge against a weakening dollar and a widening federal deficit. That single policy announcement is largely what pushed gold from its already-elevated levels up to Tuesday’s three-month high.

The Warsh Speech Behind the Gold Price Drop

Then came Friday, August 28, and the main event of the entire Jackson Hole symposium: Kevin Warsh’s first speech as Federal Reserve Chair since taking office in May. Markets had been bracing for this moment for weeks, and the gold price drop that followed shows why. CNBC’s coverage of the speech noted that gold had already been drifting lower in the hours before Warsh even stepped up to the podium, as traders positioned defensively against the risk of a hawkish tone. Warsh told the audience that despite recent inflation readings coming in better than feared, he wasn’t convinced underlying price pressures had meaningfully improved, adding that the Fed still has “work to do” on returning inflation to its 2% target. He also said price stability was a bigger concern to him right now than the slowing labor market, a notable shift in emphasis for a Fed that had spent much of the past year focused on employment data.

Warsh stopped short of giving explicit forward guidance on interest rates. But the tone alone was enough. The dollar strengthened immediately on his comments, and gold, which pays no yield and becomes less attractive when rates stay higher for longer, slid as much as 1.2% in the minutes after he spoke. By the end of the day, spot gold had fallen further, down around 3% to roughly $4,455 an ounce, a sharp pullback from Tuesday’s high just three days earlier.

Why One Speech Can Cause a Gold Price Drop This Sharp

This kind of gold price drop makes more sense once you understand what Warsh represents right now. He’s leading a Fed that, under his direction, no longer telegraphs its next move ahead of time the way previous chairs did, so every public appearance carries outsized weight. His own July policy meeting ended in a 9-3 vote to hold rates steady, with three committee members dissenting in favor of an immediate hike, an unusually high level of internal disagreement this early in a new chair’s term. With July’s core inflation reading still running around 3.3% to 3.7%, well above the Fed’s target, markets were primed to react to any hint that Warsh leans hawkish, and that’s exactly what his Jackson Hole remarks delivered.

Silver and palladium fell alongside gold on the same news, down roughly 1% and 0.8% respectively, underscoring that this wasn’t a gold-specific story so much as a broad reaction across every asset that benefits from a weaker dollar and lower rates.

What This Means for Your Own Money

  1. A double-digit monthly gain in gold is not the new normal. August’s 14% move was described by market commentators as the strongest month for gold in over a century, precisely because moves like this are rare, not routine.
  2. Understand what you’re actually holding gold for. The same Treasury buyback story that fueled this rally is the debt-related concern Ray Dalio flagged in his own portfolio recommendations — gold here is functioning as a hedge against fiscal and currency risk, not a short-term trading vehicle.
  3. Fed commentary will keep moving this trade. With Warsh’s Fed no longer pre-announcing its intentions, expect gold, along with rate-sensitive assets more broadly, to react sharply to future speeches and press conferences rather than settling into a calm trend.
  4. Zoom out before reacting to any single day. Even after this gold price drop, the metal remains up sharply for the month and has posted a roughly 95% gain over the past year, context that matters more than any single Friday afternoon swing. If you haven’t reviewed how much of your own portfolio sits in gold or cash versus stocks, a move this size is a reasonable prompt to check.

Bottom Line

This gold price drop doesn’t erase what was still a historic month for the metal, it’s a reminder that even the strongest rallies remain hostage to a handful of scheduled events on the calendar. Gold’s run higher was driven by real concerns about U.S. government debt and bond market stress, and those concerns haven’t disappeared just because Kevin Warsh sounded hawkish for one afternoon in Wyoming. Whether gold resumes its climb toward $5,000 or settles into a longer consolidation likely depends less on any one speech and more on whether the fiscal story that started this rally keeps getting worse.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making changes to your investment portfolio.
Nvidia Earnings Stock Surge Finally Breaks a Curse That Lasted a Full Year

0

Nvidia Earnings Stock Surge Finally Breaks a Curse That Lasted a Full Year

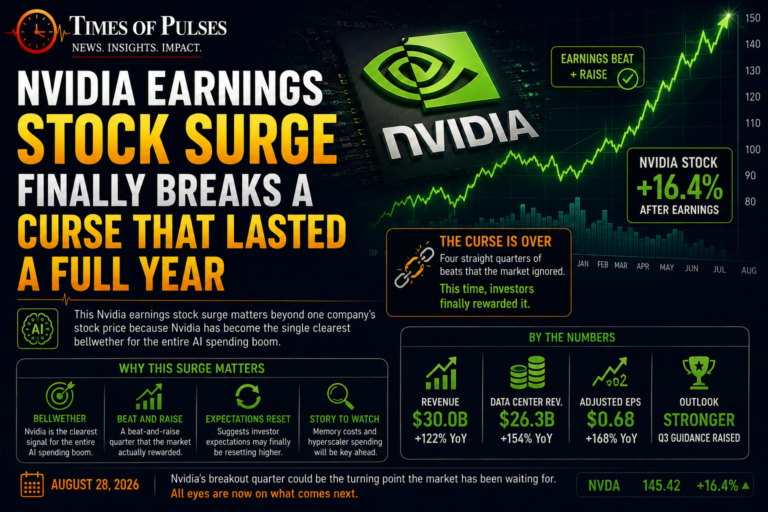
For the last four straight quarters, Nvidia did something strange: it beat Wall Street’s earnings estimates every single time, and its stock fell anyway. That streak just ended. The Nvidia earnings stock surge that followed Wednesday’s report wasn’t just another beat, it was the first genuinely positive reaction the market has given Nvidia in about a year, and the numbers behind it explain why this quarter finally felt different.

The Numbers Behind the Nvidia Earnings Stock Surge

Nvidia reported its fiscal second-quarter 2027 results after the market closed on August 26. Revenue came in at $96.2 billion, up 106% year over year, comfortably ahead of the company’s own $91 billion guidance and above most Wall Street estimates that had clustered in the $92 billion to $95 billion range. Earnings per share landed at $2.22, more than double what Nvidia reported in the same quarter a year earlier.

The bigger surprise came in the forward guidance. Nvidia told investors to expect $108 billion in revenue for the current quarter, well above the roughly $104 billion Wall Street had been modeling. Hitting that number would make Nvidia only the tenth S&P 500 company in history to post $100 billion or more in quarterly revenue. On the earnings call, CEO Jensen Huang went further, forecasting close to 70% revenue growth for fiscal 2028, a figure that came in noticeably above what analysts had already baked into their models.

Shares jumped 4.4% in after-hours trading once Huang finished speaking, marking the start of the broader Nvidia earnings stock surge that carried into Thursday morning, with Nasdaq 100 futures rising roughly 1% as traders processed the report. CNBC’s live coverage of the earnings call noted that Nvidia’s outlook assumed zero data center sales from China, meaning the beat came without any help from that market.

Why the Nvidia Earnings Stock Surge Didn’t Happen Before This

To understand why this Nvidia earnings stock surge is such a big deal, you have to look at what happened the last four times. Despite beating EPS estimates in every one of its previous five quarterly reports, Nvidia’s stock fell after four of them, with single-day reactions ranging from roughly -0.8% to as sharp as -5.5%. The pattern had become so consistent that Wall Street strategists were openly predicting a fifth straight decline heading into this report, arguing that the market had grown numb to Nvidia simply beating already-sky-high expectations.

The reason wasn’t the headline numbers, it was guidance. With Nvidia trading at a market capitalization near $5 trillion, investors had already priced in near-flawless execution. A quarter that merely matched whispered expectations wasn’t enough to move the stock higher; only guidance that meaningfully exceeded the bar could do that. For four quarters in a row, it didn’t. This time, the $108 billion guide and Huang’s 70% growth forecast finally cleared that bar, which is exactly what triggered the Nvidia earnings stock surge investors had been waiting a year to see.

The Memory Chip Connection Behind the Nvidia Earnings Stock Surge

One detail buried in the report matters for more than just Nvidia shareholders. The company said its gross margin, which held at 75% this past quarter, will slip to 74% in the current quarter. Analysts pointed directly to rising costs for memory chips and wafers as a key reason. This lines up with the broader memory chip shortage that has been rattling stocks like Micron and Sandisk in recent weeks, the same “chipflation” dynamic that’s driving DRAM prices sharply higher industry-wide. Even a company as dominant as Nvidia isn’t fully insulated from that pressure, which tells you how widespread the memory squeeze has become across the entire AI supply chain.

Nvidia also confirmed a major new deal with Amazon Web Services, which agreed to buy 2 million Nvidia GPUs alongside the company’s new Vera CPU. Management said capital spending among the five largest hyperscalers is expected to climb to $1.3 trillion next year, up from $800 billion in 2026, a signal that the AI infrastructure buildout driving this Nvidia earnings stock surge still has real momentum behind it rather than fading.

What This Means for Your Own Portfolio

  1. A single earnings report doesn’t confirm a trend reversal. This Nvidia earnings stock surge is one positive reaction after four negative ones, which is meaningful, but it’s still one data point, not proof the pattern is permanently broken.
  2. You likely have exposure whether you meant to or not. Nvidia sits in nearly every major index fund and tech ETF, so a move like this Nvidia earnings stock surge ripples through many portfolios beyond direct shareholders. If you haven’t checked how your money is actually allocated recently, an event this size is a reasonable prompt to look.
  3. Rising rates change how growth stocks get valued. Companies priced for decades of future growth, like Nvidia, are more sensitive to shifts in Treasury yields than most other stocks, since higher borrowing costs reduce what those future earnings are worth today.
  4. Watch margins, not just revenue. The dip from 75% to a guided 74% gross margin is small on paper but signals a real cost pressure, rising memory and component prices, that’s worth tracking across the whole tech sector, not just Nvidia.

Bottom Line

This Nvidia earnings stock surge matters beyond one company’s stock price because Nvidia has become the single clearest bellwether for the entire AI spending boom. A beat-and-raise quarter that the market actually rewarded, after four quarters of shrugging off similar beats, suggests investor expectations may finally be resetting to a level Nvidia can consistently clear. Whether that holds through the next earnings cycle, especially as memory costs and hyperscaler spending both keep climbing, is the story to watch from here.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making changes to your investment portfolio.
Memory Chip Stock Surge Sends Sandisk and Micron Soaring After a Brutal One-Day Crash

0

Memory Chip Stock Surge Sends Sandisk and Micron Soaring After a Brutal One-Day Crash

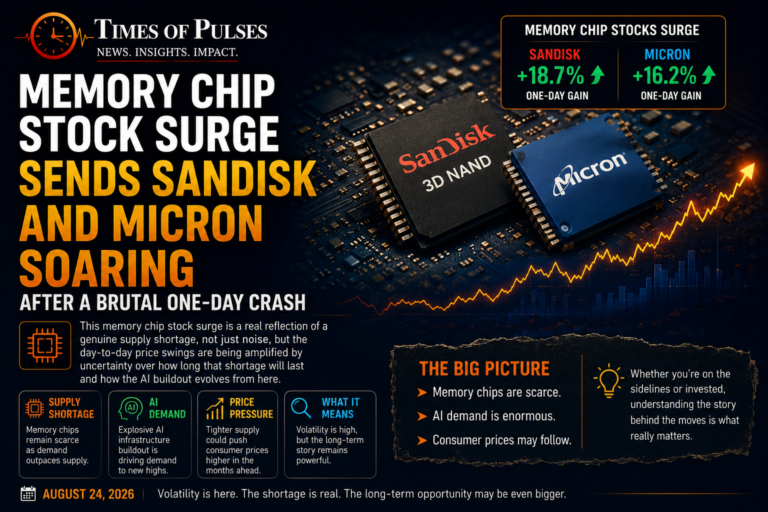
Wall Street just watched memory chip stocks fall off a cliff and then claw right back up within 24 hours, and the whiplash is making investors nervous and excited at the same time. This memory chip stock surge is happening right as Nvidia prepares to report earnings this week, and it’s tangled up with a bigger story that could quietly raise the price of your next phone or laptop. Here’s exactly what happened, why it happened, and what it actually means for your money.

The Crash That Came Right Before the Surge

On Monday, August 24, semiconductor stocks dragged the broader market lower. The S&P 500 slipped 0.28% and the Nasdaq Composite lost 0.76%, weighed down almost entirely by chip names. Micron Technology sank 5.8%, Sandisk dropped 6%, and Seagate Technology tumbled 6.5%. The iShares Semiconductor ETF (SOXX), which tracks the sector as a whole, fell 2.7% on the day. It looked, for a moment, like the AI trade was cracking.

Then came the memory chip stock surge nobody quite expected so soon. By early Tuesday trading, chip stocks were reversing hard. Every major memory name advanced in premarket trading, with Sandisk and Micron leading the bounce and Nasdaq 100 futures climbing 0.7% to recover Monday’s losses.

What’s Actually Driving the Memory Chip Stock Surge

The swings aren’t really about any single company. They’re about a structural shortage of memory chips, the components (DRAM and NAND) that let computers and AI servers store and process data. According to a report cited by Benzinga, J.P. Morgan Global Research estimates DRAM prices could climb more than 400% between the start of 2024 and the end of 2026, a phenomenon the bank has nicknamed “chipflation.” That shortage is the real engine behind this memory chip stock surge, and it’s also why the stocks are so jumpy: any headline about supply, demand, or a hyperscaler’s next contract sends the whole group swinging in one direction or the other.

The root cause is straightforward. AI data centers need enormous quantities of high-speed memory, and hyperscalers like Microsoft, Google, and Amazon have been locking up supply through long-term agreements, some running five years or longer. That leaves memory makers with far less flexibility to serve everyday consumer electronics, tightening supply everywhere else at the same time.

Why This Trade Keeps Whipsawing Investors

What makes the memory chip stock surge so dramatic is how binary the sentiment has become. When a report suggests supply is loosening or a hyperscaler might be pulling back, memory stocks get hit hard, exactly what happened Monday. When the next data point suggests the shortage is even worse than feared, the same stocks rip higher just as fast, exactly what happened Tuesday morning. Analysts have described this memory chip stock surge and its mirror-image selloffs as one of the most volatile corners of the entire AI trade, precisely because the underlying shortage is real but the timing of when it eases is genuinely uncertain.

Adding to the tension this week: investors are also digesting new U.S. sanctions tied to geopolitical tensions, incoming housing and consumer data, and Nvidia’s closely watched earnings report, all landing in the same 48-hour window as this memory chip stock surge.

The “Chipflation” Problem: What This Means for Your Wallet

Here’s the part that matters even if you don’t own a single share of Micron or Sandisk. Memory chips aren’t just an investing story, they’re a component in nearly every device you own. As DRAM and NAND prices climb, manufacturers pass at least some of that cost on to consumers. Reports have already pointed to memory now accounting for a much larger share of PC build costs than it did a year ago, and device makers have flagged the possibility of higher prices on everything from laptops to smartphones as this shortage continues. In other words, the same memory chip stock surge that’s exciting traders could show up later this year as a slightly higher price tag the next time you shop for electronics.

What This Means for Your Own Money

  1. Don’t chase the swing. A stock that’s up double digits one morning after crashing the day before is not a stable long-term signal on its own, it’s a sign of a volatile, headline-driven trade.
  2. If you own broad market or tech-heavy index funds, you already have exposure. Companies like Micron and Sandisk carry real weight in tech and semiconductor indexes, so you may be riding this memory chip stock surge without realizing it. If you haven’t reviewed where your money is actually allocated in a while, this is a reasonable moment to check.
  3. Budget for higher electronics prices, not just watch the stock. If chipflation continues as J.P. Morgan expects, a new laptop or phone next year could simply cost more than it does today.
  4. Keep an eye on interest rates too. Volatile growth stocks tend to react even more sharply when Treasury yields are moving, since higher borrowing costs change how investors value future earnings from companies like these.
  5. **Update:** Chip stocks fully recovered from this selloff within days — read how the rebound happened here chip-stocks-erase-selloff.

Bottom Line

This memory chip stock surge is a real reflection of a genuine supply shortage, not just noise, but the day-to-day price swings are being amplified by uncertainty over how long that shortage will last and how the AI buildout evolves from here. Whether you’re watching from the sidelines or holding shares through an index fund, the underlying story, memory chips are scarce, AI demand is enormous, and consumer prices may follow, is worth understanding regardless of which way the stock moves on any given morning.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making changes to your investment portfolio.