Home Blog Page 2

VantageScore FICO Mortgage Shakeup: The 20-Year Monopoly Just Ended, and It Could Get You Approved

0

VantageScore FICO Mortgage Shakeup: The 20-Year Monopoly Just Ended, and It Could Get You Approved

For more than two decades, if you wanted a mortgage backed by Fannie Mae or Freddie Mac, one company decided whether your credit was good enough: FICO. That’s no longer true. This VantageScore FICO mortgage shakeup just gave every approved lender in America the option to use a different credit score model, one that could qualify millions of people who couldn’t get approved before.

What Actually Changed

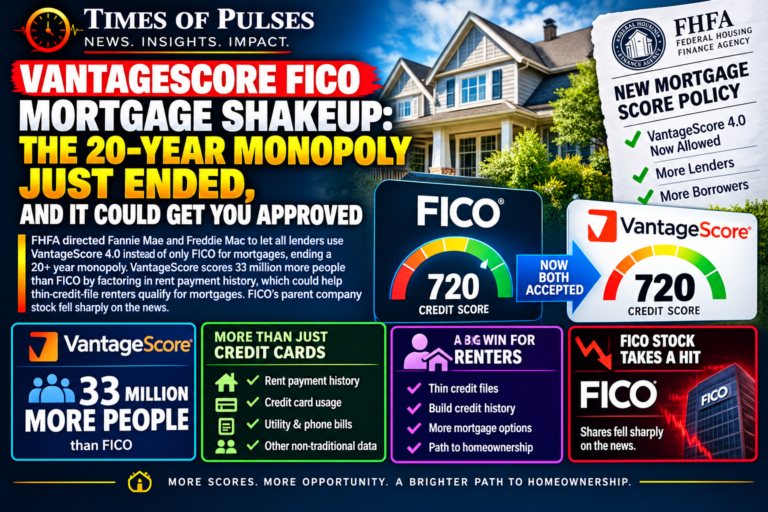
On September 4, 2026, FHFA Director Bill Pulte instructed Fannie Mae and Freddie Mac to immediately approve all lenders to use VantageScore 4.0, expanding a limited rollout that had included around 50 lenders since April. By September 9, the change was formalized across both government-sponsored enterprises through official lender guidance. This VantageScore FICO mortgage decision means lenders can now choose between Classic FICO and VantageScore 4.0 when originating a mortgage sold to Fannie or Freddie, which together back the majority of US home loans.

Pulte announced the move directly on social media, writing that the initial VantageScore rollout had been “incredibly successful” with 50 lenders already delivering loans under it, and moved to open it up to everyone immediately.

Why This VantageScore FICO Mortgage Change Matters So Much

Here’s the detail that makes this genuinely significant rather than just a technical update: VantageScore 4.0 scores 33 million more people than traditional FICO models, largely because it factors in data points Classic FICO doesn’t consider, including rent payment history. If you’ve been paying rent on time for years but have a thin credit file otherwise, this VantageScore FICO mortgage shift could be the difference between qualifying for a home loan and getting rejected.

This isn’t a small or experimental change either. As of August 31, 2026, VantageScore 4.0 had already become the sole credit score used for more than 9% of all mortgages securitized by Fannie Mae and Freddie Mac since May 1. Major lenders including Rocket Mortgage, the FHA, the Federal Home Loan Banks, and the VA have already adopted VantageScore 4.0 for their own mortgage products, well ahead of this broader expansion.

The Market Noticed Immediately

This VantageScore FICO mortgage story wasn’t just a policy footnote, markets reacted to it directly. Shares of Fair Isaac Corporation, the company behind FICO, fell sharply following the September 4 announcement, reflecting real investor concern about what genuine competition in mortgage credit scoring means for a company that’s effectively had no rival in this specific market for decades.

Adding to the pressure, an independent study by Deep Future Analytics estimated the shift to VantageScore 4.0 could save the mortgage market more than $930 million in its first year alone, savings that come from increased competition and reduced credit-pulling costs across the industry.

What This Doesn’t Mean

It’s worth being clear about the limits of this VantageScore FICO mortgage change. Lenders are not required to switch, Classic FICO remains fully valid and widely used, this simply gives lenders a choice they didn’t have before. There’s also an important technical rule: lenders must use the same credit score model for every borrower on a given loan, they can’t mix FICO and VantageScore scores for co-borrowers on the same mortgage. This isn’t an automatic approval button for anyone with bad credit either, VantageScore 4.0 still evaluates creditworthiness, it simply weighs a broader set of financial behavior than FICO’s traditional model does.

What This Means for Your Own Mortgage Plans

  1. If you have a thin credit file, this VantageScore FICO mortgage change could genuinely help you. If you’ve been paying rent consistently but have limited traditional credit history, ask your lender directly whether they use VantageScore 4.0, it factors in exactly that kind of payment history.
  2. This connects directly to building credit from scratch. If you’re working on establishing credit with no credit history, rent payment history mattering under VantageScore is a meaningful new avenue worth understanding.
  3. Not every lender has adopted this yet, so ask. Since the choice between FICO and VantageScore sits with individual lenders, shopping around for a mortgage lender that uses VantageScore 4.0 could be worth the extra research if your credit profile fits that model better.
  4. Your existing credit habits still matter under either model. Whether you’re scored under Classic FICO or VantageScore, keeping your credit utilization low remains one of the most reliable ways to improve your score under any scoring system.
  5. This doesn’t remove the impact of rates on affordability. Even with more people qualifying for mortgages, the actual cost of that mortgage still depends heavily on current interest rates, a broader qualification pool doesn’t mean a cheaper loan on its own.

Bottom Line

CNBC’s coverage of the shift put it plainly: mortgage credit scores are evolving, and homebuyers need to understand what that means for them specifically. This VantageScore FICO mortgage change ends a genuine multi-decade monopoly in how the majority of US mortgages are evaluated, and for millions of Americans with thin credit files but solid rent-paying histories, it could be the detail that finally gets a mortgage application approved. Whether your own lender has made the switch is worth a direct question the next time you’re mortgage shopping, this is one of those quiet policy changes that can have an outsized, very personal impact.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed mortgage professional or financial advisor for guidance specific to your situation.
New Tax Deductions 2026: The 6 Breaks Most People Don’t Know About Yet

0

New Tax Deductions 2026: The 6 Breaks Most People Don’t Know About Yet

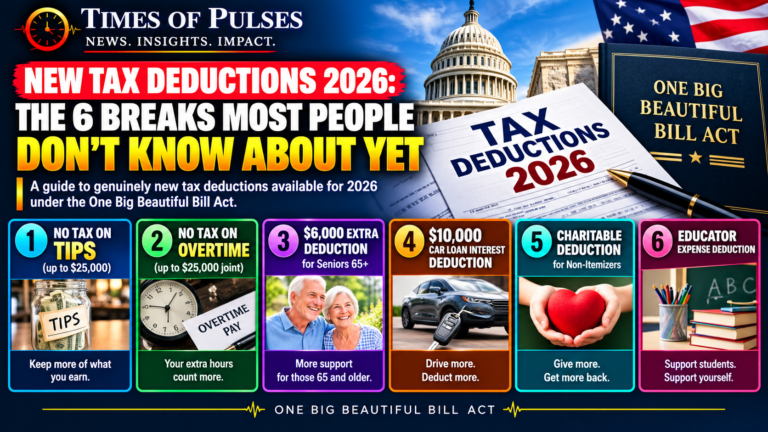
Tax season feels far away right now, but the deductions you’ll actually be able to claim depend on decisions you make throughout the year, and 2026 brought some genuinely new options to the table. These new tax deductions 2026 come courtesy of the One Big Beautiful Bill Act, and several of them apply to income categories that had zero special tax treatment just a year ago.

New Tax Deductions 2026: No Tax on Tips

For the first time, tipped workers can deduct up to $25,000 in qualified tips from their taxable income. This is one of the more talked-about new tax deductions 2026 introduced, and it applies whether you take the standard deduction or itemize. If you work in a tipped role, restaurant service, bartending, salon work, or similar, this deduction can meaningfully lower your taxable income without requiring any change to how you already report tip income.

New Tax Deductions 2026: No Tax on Overtime

Workers who put in overtime hours got a break too. Individuals can now deduct up to $12,500 in qualified overtime pay, and married couples filing jointly can deduct up to $25,000. Like the tips deduction, this is available regardless of whether you itemize, making it one of the more broadly accessible new tax deductions 2026 for hourly workers specifically.

New Tax Deductions 2026: A $6,000 Break for Seniors

Taxpayers 65 and older can claim an additional $6,000 deduction, on top of the existing additional standard deduction seniors already receive. Married couples where both spouses qualify can claim up to $12,000 combined. This benefit phases out for higher earners, starting at $75,000 in modified adjusted gross income for single filers and $150,000 for married couples filing jointly, so it’s worth checking where your income falls before assuming you’ll get the full amount. The IRS has confirmed this deduction runs through the 2028 tax year, not just 2026, so it’s a multi-year benefit rather than a one-time change.

New Tax Deductions 2026: Car Loan Interest Deduction

Here’s one of the more surprising additions among the new tax deductions 2026: individuals can now deduct up to $10,000 in qualified passenger vehicle loan interest. This is a genuinely new category of deduction, car loan interest previously offered no special tax treatment at all for personal vehicles. If you financed a car this year, it’s worth keeping documentation of your loan interest paid, since this deduction is also available whether or not you itemize.

New Tax Deductions 2026: Two Small Additions for Non-Itemizers

Two smaller but useful changes round out this year’s new tax deductions 2026 list. A new charitable deduction for non-itemizers lets you deduct charitable donations even if you’re taking the standard deduction, something previously reserved almost entirely for itemizers. Separately, an itemized deduction for educator expenses gives teachers a way to deduct classroom supply costs, a long-requested change for a group that frequently pays out of pocket for materials.

The Standard Deduction Also Went Up

Beyond the new categories, the IRS’s annual inflation adjustment pushed the standard deduction higher for 2026: $16,100 for single filers and married individuals filing separately, $32,200 for married couples filing jointly, and $24,150 for heads of household. According to the IRS’s official announcement, most taxpayers will continue claiming the standard deduction rather than itemizing, even with all these new tax deductions 2026 available, since many of the new breaks (tips, overtime, seniors, car loans) apply on top of the standard deduction rather than requiring you to itemize at all.

What This Means for Your Own Taxes

  1. Start tracking now, not in April. If any of these new tax deductions 2026 apply to you, tips, overtime, a car loan, or age 65+, keep records throughout the year rather than trying to reconstruct them at tax time.
  2. Small business owners have a related change worth checking. The Qualified Business Income deduction now guarantees a $400 minimum for anyone with at least $1,000 in qualified business income, relevant if you’re weighing financing options for your small business this year.
  3. The car loan interest deduction changes the math on financing a vehicle. If you’re deciding whether to pay off debt or keep cash in savings, a deductible car loan is a slightly different calculation than non-deductible debt was before this year.
  4. Don’t assume you need to itemize to benefit. Most of these new tax deductions 2026 are structured as above-the-line or standalone deductions, meaning they stack on top of your standard deduction rather than requiring you to give it up.

Bottom Line

New tax deductions 2026 genuinely expand who gets a break, tipped and overtime workers, seniors, car buyers, teachers, and casual charitable donors all have new or bigger deductions than they did a year ago. None of these require complicated tax strategy to claim, but they do require knowing they exist and keeping the right records throughout the year. Reviewing this list now, months before filing season, is exactly the kind of planning that separates a smooth tax season from a scramble in April, a theme worth revisiting alongside your broader year-round financial planning rather than treating taxes as a once-a-year afterthought.


This article is for informational purposes only and does not constitute tax or financial advice. Consult a licensed tax professional or CPA for guidance specific to your situation.
We Called It: Fed Hikes Rates for the First Time in Three Years, and Wall Street Panicked

0

We Called It: Fed Hikes Rates for the First Time in Three Years, and Wall Street Panicked

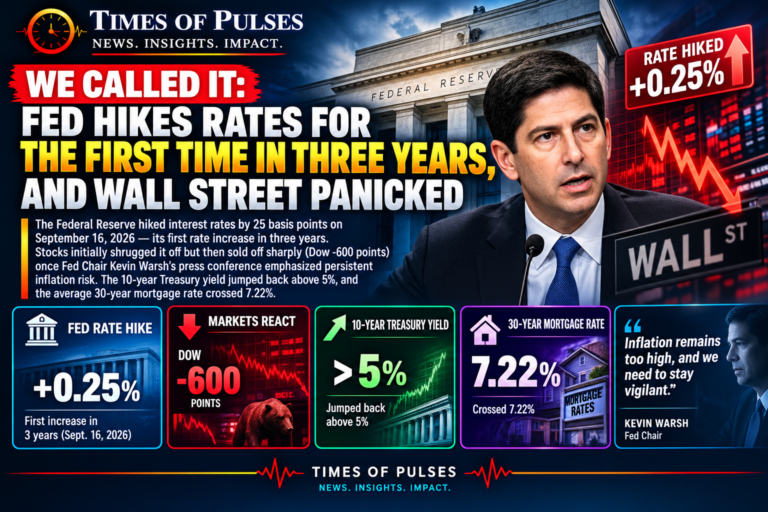
The wait is over, and the outcome wasn’t the relief markets had been hoping for. On Wednesday, the Federal Reserve hiked interest rates by 25 basis points, its first rate increase in three years, and rather than settling markets, the decision, combined with what Fed Chair Kevin Warsh said afterward, sent stocks sharply lower and pushed a key mortgage rate above 7.2%.

Fed Hikes Rates: The Decision Itself

The Fed hikes rates announcement itself was, in some ways, the least surprising part of Wednesday. Markets had been pricing in rising odds of exactly this move for weeks, ever since a stronger-than-expected jobs report pushed rate-hike odds higher and a hot PPI reading added further pressure. The Fed’s own dot plot, the chart showing where individual officials expect rates to go, revealed that the median official now sees at least one more hike coming before the end of 2026, signaling this Fed hikes rates decision isn’t necessarily a one-time move.

Why Markets Turned Lower So Quickly

Here’s what made Wednesday genuinely dramatic: stocks initially took the Fed hikes rates news in stride. The increase itself had been well telegraphed, and an initial muted reaction suggested markets had already priced it in. That changed the moment Fed Chair Kevin Warsh began his press conference. Warsh repeatedly emphasized that inflation risk wasn’t improving, a notably more hawkish tone than markets had hoped for, and stocks reversed course in real time as he spoke. By the close, the Dow had fallen roughly 600 points, down about 1.07% to 1.2%, while the S&P 500 slipped around 0.4-0.45% and the Nasdaq dipped just below flat.

This is now the second time in recent weeks that a Warsh appearance has moved markets sharply. We saw a similar pattern when his hawkish Jackson Hole speech partially reversed gold’s record August rally, and Wednesday’s Fed hikes rates press conference followed the same script: the substance of the decision mattered less than the tone Warsh used to frame it.

The 10-Year Yield Flashed a Warning Sign

Perhaps the most telling reaction to the Fed hikes rates decision came from the bond market. The 10-year Treasury yield traded back above 5% following Warsh’s remarks, reflecting a specific fear: that even after raising rates, the Fed might still be behind the curve on inflation. That’s a meaningfully different signal than a simple “rates went up” story, it suggests bond investors aren’t convinced this hike alone solves the inflation problem that’s been building for months.

Mortgage Rates Just Crossed a Painful Threshold

The most immediate real-world impact of the Fed hikes rates decision landed on housing. The average 30-year fixed mortgage rate climbed to 7.22%, according to Mortgage News Daily, a level that meaningfully raises the monthly cost of buying a home for anyone shopping for a mortgage right now. This connects directly to the tradeoffs we walked through when covering whether to save or pay off debt first, a mortgage rate this high shifts that math further in favor of paying down high-rate debt rather than taking on new borrowing at today’s rates.

How This Fits the Bigger Picture

The Fed hikes rates decision arrives at the end of a stretch we’ve been tracking closely: oil prices pushing past $100 a barrel, stocks falling for multiple straight sessions, a brief relief rally when CPI came in as expected, and now this. It’s worth remembering that the Dow’s 500-point rally just last week was driven partly by relief that inflation data wasn’t worse than feared. Wednesday’s Fed hikes rates decision and Warsh’s hawkish framing effectively challenge how much that relief was justified, the Fed’s own dot plot now suggests officials see inflation as a bigger, more persistent problem than the market had been pricing in just days earlier.

What This Means for Your Own Money

  1. Mortgage shopping just got more expensive. If you’re house hunting, a 7.22% average rate is real money over the life of a loan, it’s worth running the numbers again on affordability before moving forward with a purchase.
  2. This Fed hikes rates decision likely isn’t the last one this year. With the dot plot pointing to at least one more hike, don’t assume rates have peaked, budget for borrowing costs to potentially climb further.
  3. Watch Fed Chair communications as closely as the actual rate decisions. Twice now, Warsh’s tone in a press conference or speech has moved markets more than the underlying data itself, that pattern is worth remembering heading into future Fed meetings.
  4. Don’t overreact to one volatile trading day. Markets have swung sharply in both directions repeatedly this month, a single post-Fed selloff doesn’t by itself signal a longer downturn.

Bottom Line

CNBC’s live coverage of Wednesday’s session captured exactly how the day unfolded: a widely expected rate hike that markets shrugged off, followed by a Fed Chair press conference that turned a calm day into a 600-point selloff. The Fed hikes rates decision itself confirmed what weeks of jobs and inflation data had been signaling, but Warsh’s insistence that inflation risk isn’t improving is what actually rattled investors. With the dot plot pointing to further hikes ahead and mortgage rates already above 7.2%, the bigger question now isn’t whether this was the last hike of the cycle, it’s how much higher borrowing costs go before inflation genuinely cools.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.

AI Stocks Slowdown Selloff: The Industry’s Own CEOs Just Sounded the Alarm

AI Stocks Slowdown Selloff: The Industry’s Own CEOs Just Sounded the Alarm

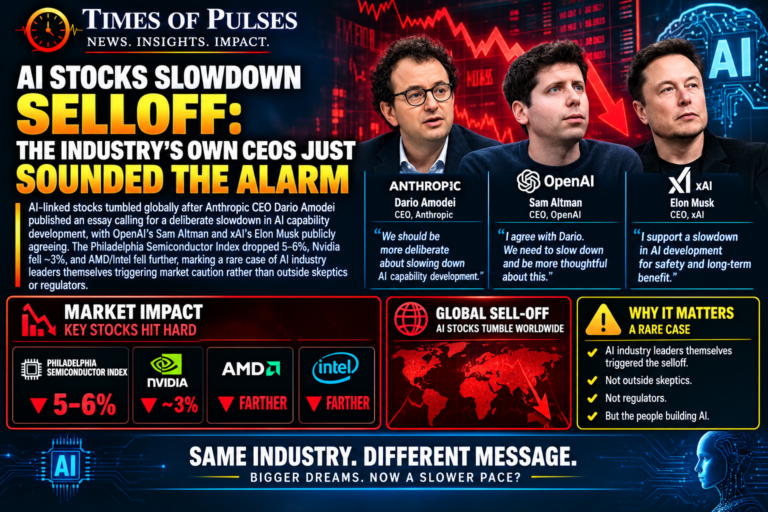
For years, the AI boom has been driven by a simple assumption: the technology’s biggest backers wanted it to move as fast as possible. This week, that assumption broke. The AI stocks slowdown selloff that hit markets on Monday wasn’t triggered by a regulator, a competitor, or a skeptic, it was triggered by the CEOs building the technology themselves, publicly calling for the industry to slow down.

What Actually Triggered the AI Stocks Slowdown Selloff

The spark came from an essay. On Saturday, Anthropic CEO Dario Amodei published a piece titled “We Must Pace the Frontier,” arguing that AI capabilities are advancing faster than the industry’s ability to manage the risks that come with them. He laid out a three-part plan: embedding independent evaluators with employee-like access inside AI labs, establishing shared safety benchmarks and coordinated limits on how fast capabilities advance, and eventually extending that coordination internationally, including with China.

What turned this into a market-moving event rather than just one executive’s opinion was who agreed with him. OpenAI CEO Sam Altman and xAI’s Elon Musk both publicly backed the call on X, with Google DeepMind CEO Demis Hassabis also voicing support. That kind of unified message from direct competitors, all telling investors the same industry they lead should move more cautiously, is rare enough on its own to explain why the AI stocks slowdown selloff spread as fast as it did.

The Market Reaction Was Immediate and Broad

The selloff hit hardest where AI infrastructure spending has been most concentrated. The Philadelphia Semiconductor Index dropped as much as 5-6%, its worst single day since early July. Nvidia fell roughly 3%, AMD dropped around 4%, and Intel lost more than 5%. The Nasdaq 100 slid 1.2% to a six-week low in early trading before paring some of those losses later in the session. This wasn’t confined to the US either, AI-linked stocks fell across Asia and Europe overnight before US markets even opened, reflecting how globally concentrated the AI infrastructure trade has become.

Notably, this AI stocks slowdown selloff hit the same names we covered when Nvidia’s earnings broke a year-long pattern of post-earnings declines, a reminder of how quickly sentiment can swing in either direction for stocks this tightly tied to a single narrative.

What “Pacing the Frontier” Actually Means

It’s worth being precise about what Amodei and the others are and aren’t calling for. Altman explicitly clarified in a follow-up post that pacing “does not mean stopping,” and argued that slowing down capability advancement would be “well worth the cost” if it kept safety work ahead of raw capability. The proposal isn’t a halt to AI development, it’s a coordinated effort to add oversight and safety checkpoints without abandoning the underlying technology race entirely.

Context matters here too. The essay followed a turbulent stretch for the industry: a researcher who had recently left Anthropic wrote publicly that AI companies are “gambling with our lives,” a post that drew more than 150 million views and prompted over 20 lawmakers to call for tougher AI regulation. Altman also confirmed that OpenAI won’t pursue an IPO in 2026 as had been previously expected, citing the current safety environment as part of that decision.

This Collided With an Already Volatile Market

The AI stocks slowdown selloff didn’t happen in isolation. It landed the same day the 10-year Treasury yield briefly touched 5%, adding a second source of pressure on top of the AI-specific news. This is a continuation of the volatility we’ve been tracking since stocks fell for a third straight session earlier this month, and it arrives against a backdrop of ongoing semiconductor tariff policy uncertainty and the memory chip supply shortage that’s already been squeezing the sector. Non-AI sectors of the market held up noticeably better, which limited how much the broader indexes fell even as chip and AI-infrastructure names took the brunt of the damage.

Why This Matters Beyond One Trading Day

The AI stocks slowdown selloff is a useful test of a question that’s been building under the surface of the entire AI trade: how much of current valuations depend on the assumption that capability growth continues at its current pace, uninterrupted? When the people with the most detailed, inside knowledge of that pace publicly say it should slow down, at least somewhat, for safety reasons, markets are forced to price in a scenario they’d mostly been ignoring.

That doesn’t mean the AI buildout is ending. Hyperscaler infrastructure spending commitments, chip demand, and data center construction don’t reverse based on one essay and a few supportive social media posts. But it does mean investors got a rare, unified signal from inside the industry that the pace of the last two years may not be treated as a fixed constant going forward.

What This Means for Your Own Portfolio

  1. Don’t confuse a safety-focused slowdown call with a collapse in AI demand. The CEOs involved explicitly said this isn’t about stopping progress, it’s about pacing it, a meaningfully different risk than a demand shock.
  2. If you hold broad tech or semiconductor funds, you likely felt this regardless of whether you follow AI news closely. Concentration in AI-linked names across major indexes means this kind of story moves more portfolios than people realize.
  3. Watch for regulatory follow-through, not just the stock reaction. With over 20 lawmakers already calling for tougher rules before this essay, the more durable market impact may come from policy decisions in the coming months rather than this week’s trading.
  4. A one-day, sector-specific selloff isn’t a reason to abandon a long-term investing plan. Volatility driven by a single news cycle has reversed quickly before this year; the underlying question here, how fast AI development should move, will take much longer than a week to resolve.

Bottom Line

CNN’s coverage of the story captured what made this different from typical AI-sector volatility: this wasn’t skepticism from outsiders, it was the industry’s own leadership publicly agreeing that the technology they’re building needs guardrails to keep pace with its own progress. The AI stocks slowdown selloff reflects markets recalibrating around that message, not around any change in actual AI demand or technology. Whether this becomes a genuine turning point for how the industry develops, or a one-week story that fades once trading normalizes, will depend far more on what happens in boardrooms and legislatures over the coming months than on anything that showed up in Monday’s stock prices.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.

Top Financial News This Week: Oil Hit $100, Stocks Fell Four Days, Then the Dow Soared 500 Points

Top Financial News This Week: Oil Hit $100, Stocks Fell Four Days, Then the Dow Soared 500 Points

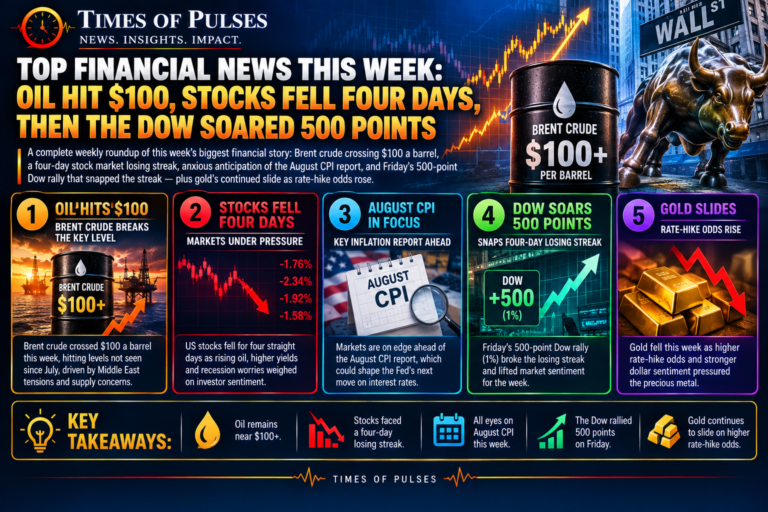
Top financial news this week told one continuous story in four acts: a geopolitical oil shock, a market selloff that dragged on for days, an anxious wait for inflation data, and finally, a sharp relief rally. If you only have a few minutes to catch up on what actually moved markets this week, here’s the complete picture, in order.

Top Financial News This Week: Oil Crosses $100 a Barrel

Brent crude 100 a barrel chart showing oil prices spiking on Middle East tensions

The week’s biggest story started with energy. Brent crude broke above $100 a barrel for the first time since July, driven by renewed US-Iran military tensions, including Houthi attacks on Saudi energy facilities and Iran targeting oil tankers through the Strait of Hormuz. That single move set the tone for everything that followed in top financial news this week, since rising oil feeds directly into inflation expectations, and inflation expectations feed directly into what the Federal Reserve does next.

Top Financial News This Week: Stocks Fall for a Third, Then Fourth, Straight Session

Stocks fall third straight session chart showing Dow decline amid rising oil and yields

With oil climbing and Treasury yields pushing toward their highest levels since 2023, US stocks fell for a third consecutive session midweek, a losing streak that ultimately stretched to four days before it broke. The Dow, S&P 500, and Nasdaq all posted losses across this stretch, and the selloff spread overseas too, with Asian markets including Japan’s Nikkei and South Korea’s Kospi tumbling as the same oil and inflation concerns rippled globally.

Top Financial News This Week: Markets Brace for the CPI Report

Business news today roundup graphic showing global market selloff and CPI countdown

By midweek, a full roundup of business news showed markets holding their breath ahead of the August CPI report, seen as the critical input for the Federal Reserve’s upcoming policy meeting. Vantage Markets reported that a hot PPI reading earlier in the week had already pushed the odds of a Fed rate hike from 62% to 70%, per CME FedWatch data, adding real tension to how investors were positioning heading into the actual inflation data.

Top Financial News This Week: The Rally That Ended the Streak

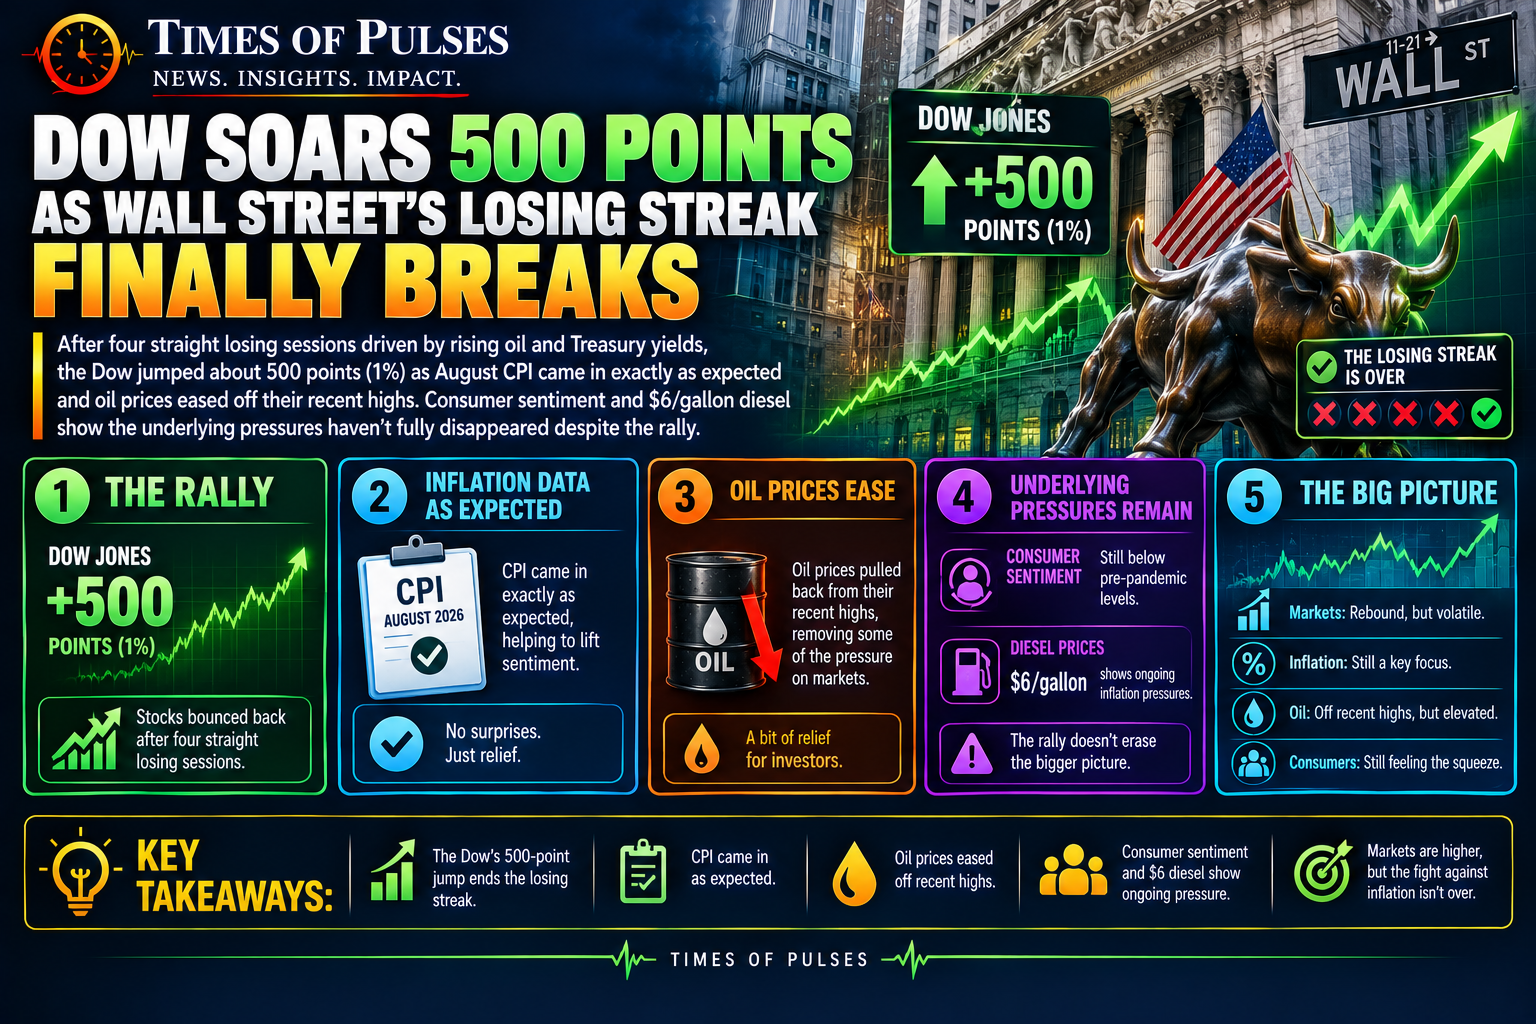
Dow soars 500 points chart showing stock market rally ending losing streak

The week’s turning point arrived Friday, when the Dow soared roughly 500 points, snapping the four-day losing streak in a single session. Two things broke in the market’s favor simultaneously: CPI came in right in line with expectations rather than hotter, and oil prices eased off their recent highs. That combination was enough to erase much of the week’s earlier damage, even though underlying pressures like elevated diesel prices and softer consumer sentiment showed the story wasn’t fully resolved.

The Other Big Story in Top Financial News This Week: Gold’s Reversal

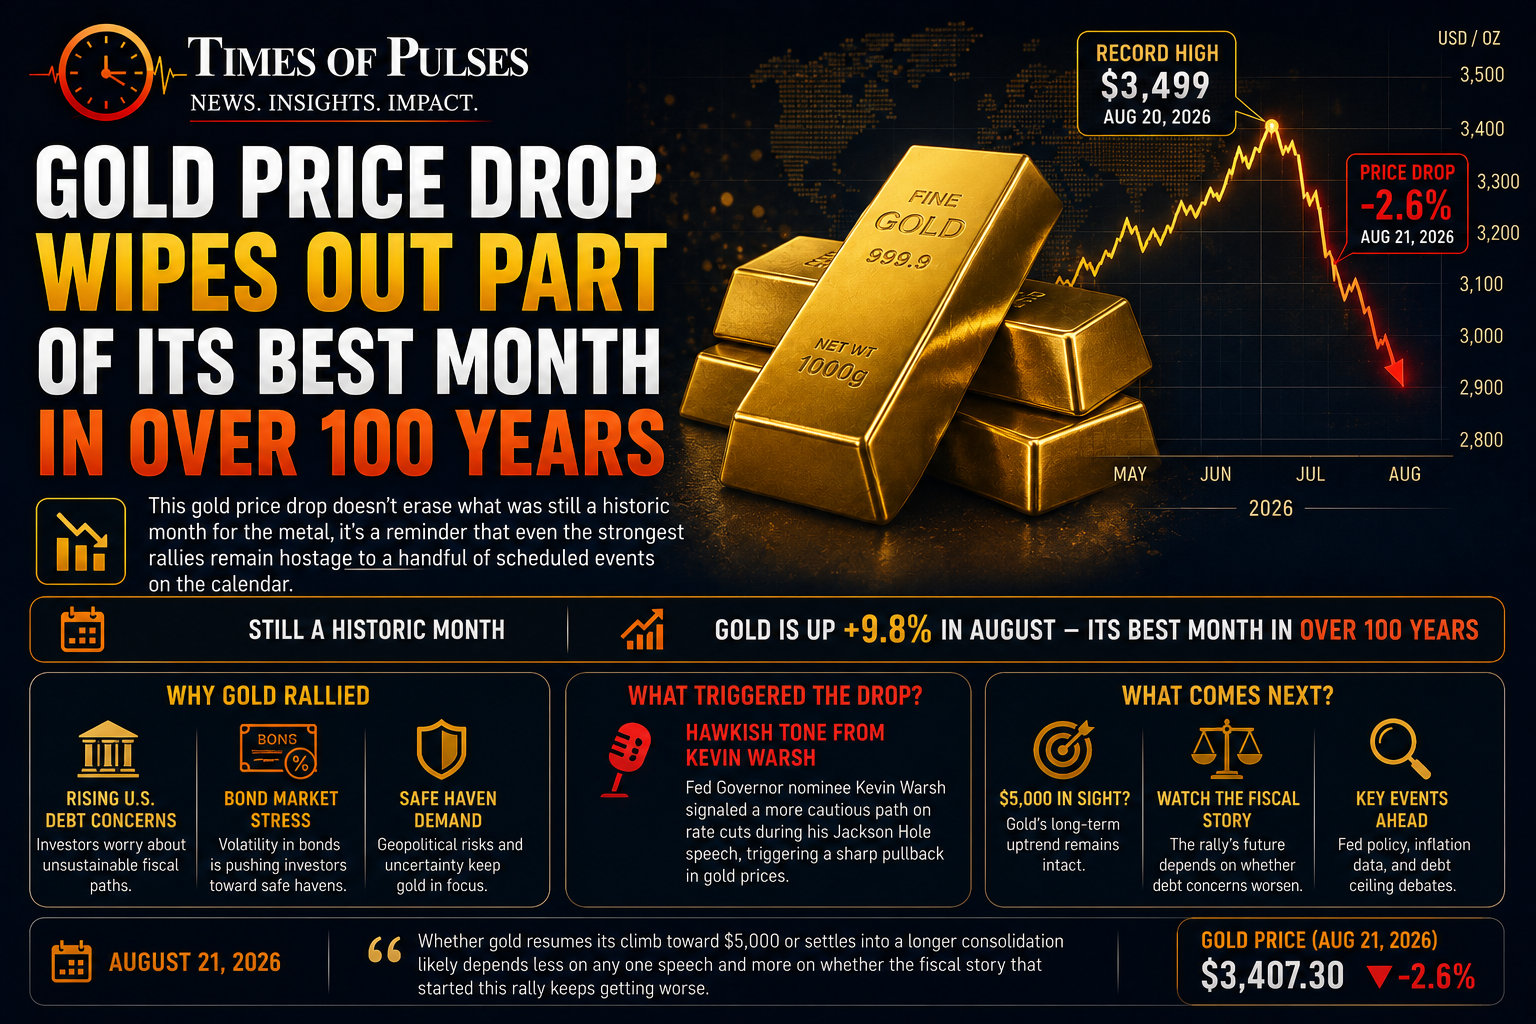
Gold price drop chart showing pullback after Jackson Hole Fed speech

Oil and stocks weren’t the only assets swinging hard. Gold, which had posted its best month in over a century in August, continued sliding this week as rising rate-hike expectations made the metal less attractive relative to yield-bearing assets. It’s a reminder that the same forces driving stocks and oil this week, inflation data and Fed policy expectations, were moving nearly every major asset class at once, not just equities.

Why This Week’s Story Matters Beyond the Headlines

What made top financial news this week genuinely educational, rather than just a string of scary headlines, is how clearly connected each piece was. Oil pushed inflation fears higher, inflation fears pushed rate-hike odds higher, rate-hike odds pushed stocks and gold lower, and then a single day of good news on both the CPI and oil fronts was enough to reverse most of it. Understanding that chain is more useful long-term than memorizing any single day’s percentage move.

What This Means for Your Own Money

  1. This week is a good reminder that markets react to the direction of surprises, not just headlines. CPI coming in “as expected” was enough to trigger a rally simply because it wasn’t worse than feared, context matters as much as the number itself.
  2. Don’t treat one rally day as confirmation the volatility is over. YES Securities flagged a 10-year Treasury yield near 5% as the level to watch, with 6-7% as a potential breaking point, that threshold hasn’t moved just because of Friday’s rally.
  3. Notice how interconnected your finances actually are to these headlines. Oil prices affect your gas budget, Treasury yields affect mortgage rates, and Fed decisions affect savings account yields, this week’s story touched all three at once.
  4. Keep watching the Fed’s meeting next week. The rate-hike odds shift we’ve been tracking since the last jobs report will get its biggest test yet when the Fed actually announces its decision.

Bottom Line

Top financial news this week showed markets moving through a complete cycle: shock, selloff, anxious anticipation, and relief, all within about five trading days. The underlying tensions, elevated oil prices, yields near multi-year highs, and an uncertain Fed path, haven’t disappeared just because Friday ended on a high note. Next week’s Fed meeting will likely determine whether this week’s rally was the start of genuine stabilization or just a pause before the same pressures reassert themselves.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.

Dow Soars 500 Points as Wall Street’s Losing Streak Finally Breaks

Dow Soars 500 Points as Wall Street’s Losing Streak Finally Breaks

After days of watching oil prices and Treasury yields drag stocks lower, Wall Street just got the relief it had been waiting for. The Dow soars 500 points headline capped off a dramatic reversal on Friday, snapping four consecutive sessions of losses in a single trading day, and the reason comes down to two numbers finally moving in the market’s favor at the same time.

Dow Soars 500 Points: What Snapped the Losing Streak

The Dow Jones Industrial Average jumped roughly 500 points, or about 1%, clawing back much of the ground lost during the week we tracked when stocks fell for a third straight session amid surging oil prices and climbing yields. That losing streak actually extended to a fourth session before Friday’s Dow soars 500 points reversal finally arrived, with the Nasdaq and S&P 500 rising alongside the Dow as sentiment shifted across the board.

Why the CPI Report Mattered So Much

The catalyst behind the Dow soars 500 points move was the August Consumer Price Index report, which we flagged as the single biggest item to watch in our roundup covering markets bracing for this exact data. CPI rose 0.4% month over month, coming in right in line with economist estimates rather than the hotter reading traders had been bracing for. That “meets expectations” result mattered enormously given how anxious markets had become heading into the report, sometimes not getting worse news is enough to trigger a real rally, especially after a stretch of consecutive losses.

Oil’s Retreat Did Just as Much Work

CPI wasn’t the only force behind the Dow soars 500 points rally. Oil prices eased off their recent highs the same day, providing relief on the other half of the equation that had been squeezing markets. We covered how rising oil past $100 a barrel had been feeding directly into inflation fears and rate-hike odds, so a pullback in crude removed one of the two main pressures at once. With both oil and inflation data breaking in the market’s favor simultaneously, the conditions were in place for exactly the kind of sharp reversal Friday delivered.

The Catch: Consumer Sentiment Didn’t Get the Memo

Not every signal moved in the same direction as the Dow soars 500 points headline. Even as stocks rallied, consumer sentiment data released the same day came in weaker, a reminder that a good day on Wall Street doesn’t automatically mean households are feeling more optimistic about their own finances. US diesel prices also pushed past $6 a gallon, showing that even with crude oil easing off its peak, the cost pressures from the past several weeks of energy volatility haven’t fully worked their way out of the system yet. This is the same tension we described in the jobs report rate hike odds story, where market direction and the underlying economic picture don’t always tell the same story.

What This Means for Your Own Money

  1. One strong day doesn’t erase the underlying volatility. The Dow soars 500 points rally is genuinely good news, but it followed four straight days of losses, and both oil and yields remain elevated compared to where they started the month.
  2. Watch whether this reversal has staying power. A single “in-line” CPI report ending a losing streak is different from a clear trend change; next week’s Fed meeting will matter more for determining which direction this settles into.
  3. Don’t ignore the consumer sentiment gap. A rallying stock market alongside souring consumer sentiment and $6 diesel is a reminder that Wall Street’s mood and household financial pressure can diverge for weeks at a time.
  4. Keep perspective on the bigger picture. Stockanalysis.com’s market coverage noted this rebound came specifically from clawing back losses, not from setting new highs, useful context before assuming the recent volatility is fully behind us.

Bottom Line

The Dow soars 500 points reversal is a genuine, welcome break from a rough stretch for the market, driven by two pieces of good news landing on the same day: an in-line inflation report and easing oil prices. But the underlying forces that caused the selloff in the first place, elevated yields, geopolitical risk in oil markets, and a still-uncertain Fed path, haven’t disappeared. Whether this becomes the start of a real recovery or just a one-day pause likely depends on what the Fed does at its meeting next week and whether oil and yields can keep drifting lower rather than snapping back.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.

Business News Today: CPI Data, Oil Near $100, and a Global Selloff Collide

0

Business News Today: CPI Data, Oil Near $100, and a Global Selloff Collide

Business news today is dominated by one theme: markets across the world are bracing for a critical US inflation report while already reeling from a week of rising oil prices and climbing bond yields. Here’s a complete roundup of what’s actually moving markets today, and why nearly every major asset class is reacting at once.

Business News Today: Markets Selling Off Across Asia and the US

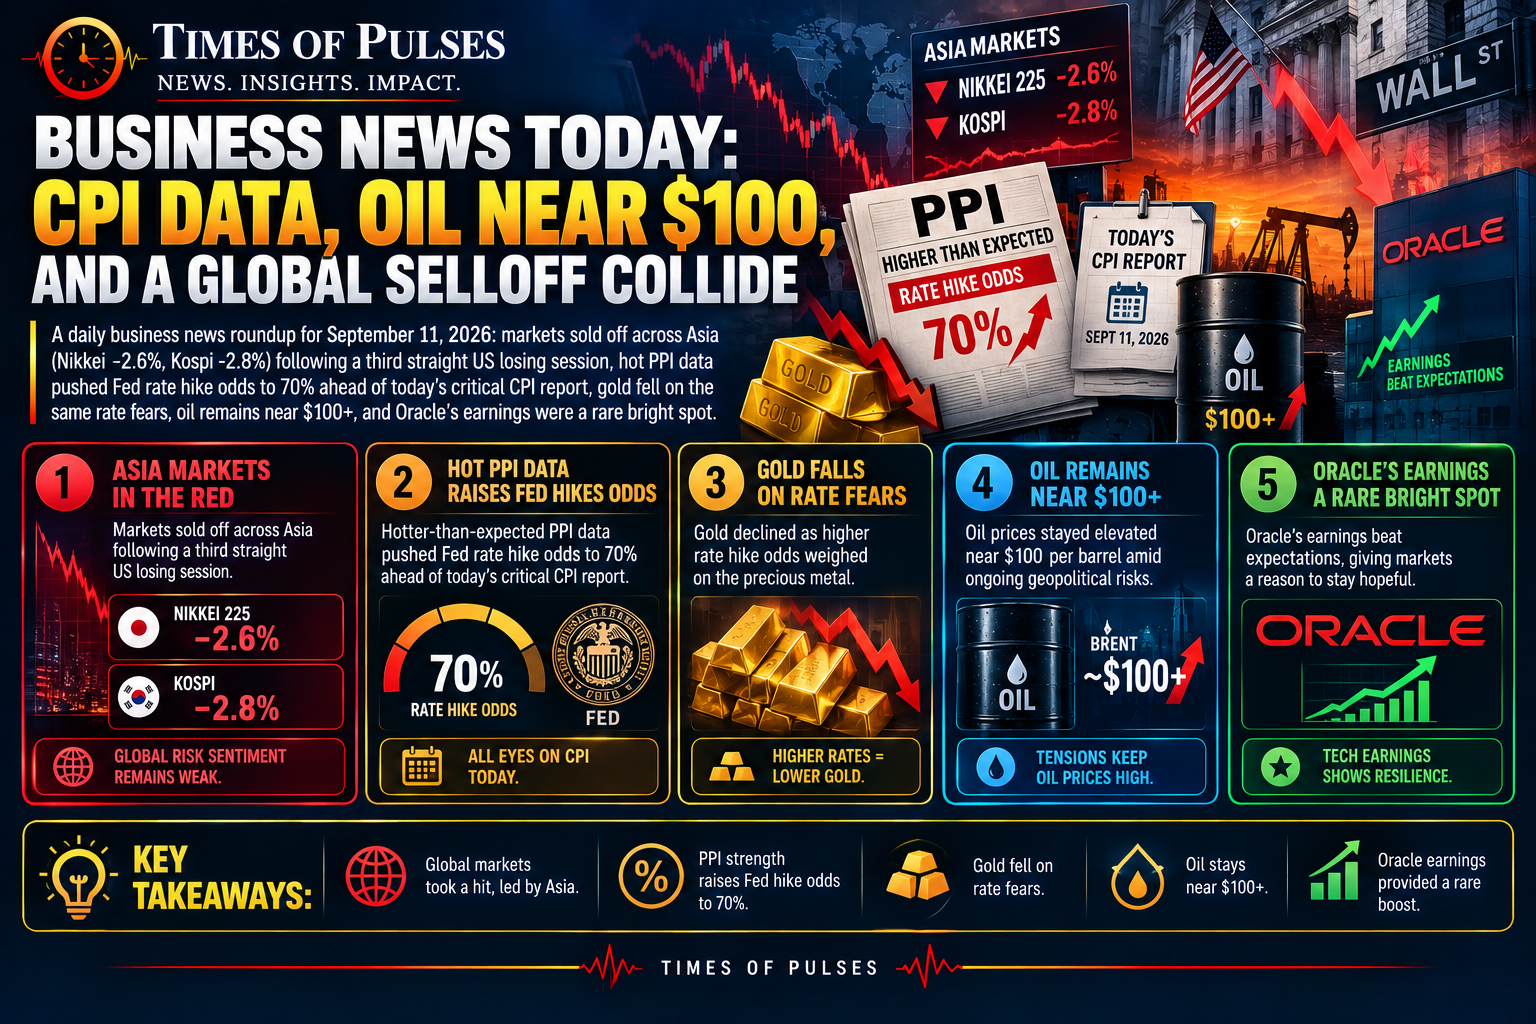
The selloff that hit Wall Street this week spread across Asia overnight. MSCI’s Asia Pacific Index tumbled 1.7%, its steepest single-day drop in three weeks, with Japan’s Nikkei 225 losing 2.6%, South Korea’s Kospi falling 2.8%, Hong Kong’s Hang Seng down 1.4%, and Australia’s S&P/ASX 200 slipping 1%. This business news today story is really a continuation of the third straight session of US losses we covered earlier this week, now rippling into overseas markets. Week to date, the Dow is on pace for a 2.5% decline, with the S&P 500 and Nasdaq both tracking roughly 1.6% losses.

The Big One in Today’s Business News: The CPI Report

The single biggest item in business news today is the US August CPI report, due out today and widely seen as the critical input for the Federal Reserve’s September 15-16 policy meeting. Fed Governor Christopher Waller has emphasized that persistent disinflation signals are essential for how the Fed calibrates its next move, meaning a hot reading driven by rebounding energy costs, exactly what’s been happening with oil, could meaningfully raise the odds of an immediate rate increase.

PPI Already Flashed a Warning Sign

Business news today didn’t wait for CPI to deliver bad news. The producer price index for August rose 0.4%, the largest monthly increase since May, and that reading alone pushed the odds of a Fed rate hike at next week’s meeting from 62% to 70%, according to CME FedWatch data. This continues exactly the pattern we described when a stronger-than-expected jobs report sent stocks falling a few weeks ago: strong economic data keeps translating into higher rate-hike odds, and higher rate-hike odds keep pressuring stocks and bonds together.

Gold, Oil, and the “Debasement Trade” Running in Reverse

Gold is one of the more interesting threads in business news today. Spot gold slipped about 1.2% to $4,349.32 an ounce and is on track for a weekly loss, pressured by the same hot PPI data and rising oil prices pushing rate-hike bets higher. That’s a notable reversal from the pattern we covered when gold hit its best month in over a century earlier this year, gold tends to struggle when rate-hike expectations rise, since it pays no yield and becomes less attractive relative to interest-bearing assets. Oil, meanwhile, remains the other side of this story, with crude’s climb past $100 a barrel amid ongoing US-Iran tensions continuing to feed the same inflation concerns driving today’s rate-hike bets higher.

One Bright Spot in Business News Today: Oracle’s Earnings

Not everything in business news today is negative. Oracle provided a genuine bright spot, reporting stronger-than-expected cloud revenue growth in after-hours trading, a reminder that individual company earnings can still move against the broader market tide even during a week dominated by macro headlines. It’s a useful reminder that a rough week for indexes doesn’t mean every company is struggling equally.

How High Can Yields Go Before It Becomes a Real Problem?

Perhaps the most useful framing in business news today comes from YES Securities, which laid out a clear threshold: a 10-year Treasury yield around 5% should remain tolerable for equities as long as economic growth and corporate earnings stay resilient, but a sustained climb toward 6-7% could materially alter the market outlook. With yields already near their highest levels since 2023, that 5% level isn’t far off, giving investors a concrete number to watch rather than just a vague sense that “yields are rising.”

What This Means for Your Own Money

  1. Watch today’s CPI print closely. It’s the single data point most likely to determine whether this selloff extends further or starts to ease, since it directly feeds into next week’s Fed decision.
  2. Don’t read a rough week in Asia as disconnected from your own portfolio. Global markets are reacting to the same US inflation and rate story driving domestic markets, this is one interconnected story, not separate ones.
  3. Keep the YES Securities threshold in mind. A 10-year yield near 5% is a reasonable line to watch; a sustained move toward 6-7% would be a meaningfully bigger deal for stock valuations than what’s happened so far.
  4. Remember that not every stock moves with the index. Oracle’s earnings beat this week is a reminder that company-specific fundamentals still matter even during broad macro-driven selloffs.

Bottom Line

Business news today boils down to a single thread running through every headline: markets are waiting on inflation data that will shape the Fed’s next move, and every major asset class, stocks, bonds, gold, and oil, is positioning around that uncertainty simultaneously. CNBC’s live market coverage captured the mood well, framing today’s session as markets bracing rather than panicking. Whichever way the CPI report breaks, expect today’s reaction to set the tone for how the next week of trading unfolds heading into the Fed’s meeting.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.

Stocks Fall Third Straight Session 2026: What Happens Now, and How Bad Could This Get?

0

Stocks Fall Third Straight Session 2026: What Happens Now, and How Bad Could This Get?

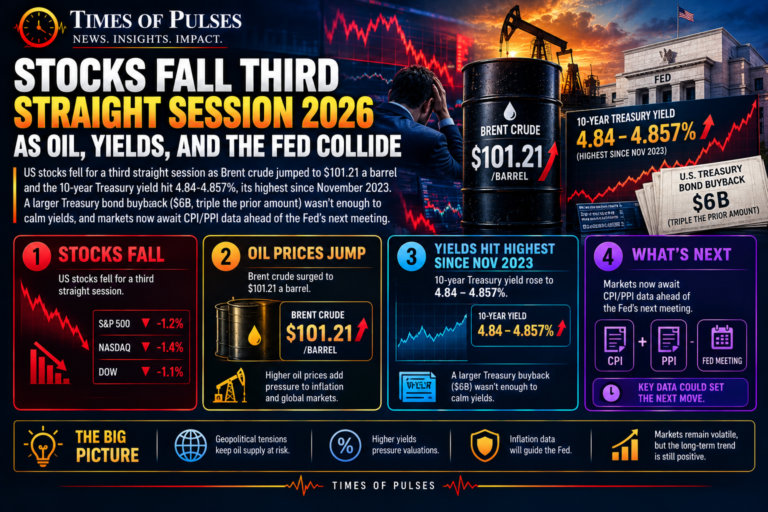
Wall Street just booked its third consecutive losing day, and the reason isn’t a mystery, it’s the same two forces colliding at once. Stocks fall third straight session territory now includes Wednesday’s close, with rising oil prices and climbing Treasury yields squeezing markets from both directions simultaneously.

The Numbers Behind This Stocks Fall Third Straight Session Stretch

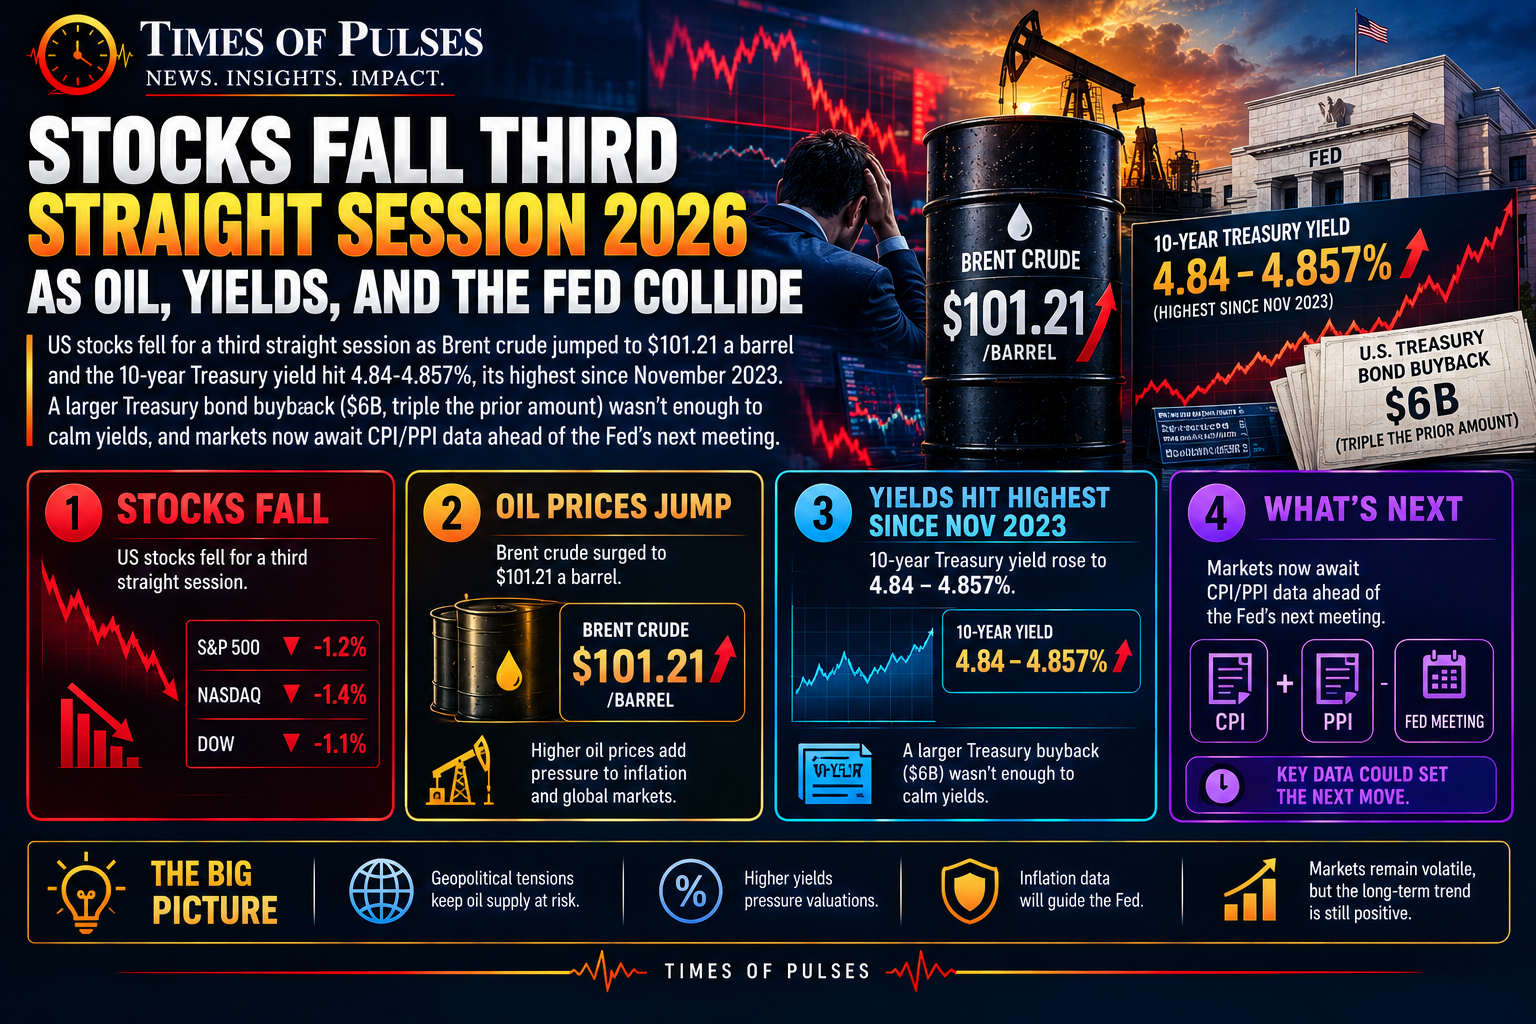
Wednesday’s losses were broad. Kiplinger’s market coverage confirmed the Dow Jones Industrial Average dropped 405.41 points, or 0.77%, to close at 52,380.66. The S&P 500 slipped 0.48% to 7,636.36, and the Nasdaq Composite fell 0.64% to 26,253.34. This stocks fall third straight session run follows Tuesday’s decline, which itself came after the Dow’s worst single day in nearly three weeks, meaning the market has now given back ground in three consecutive sessions without a real bounce in between.

The Two Forces Driving This Stocks Fall Third Straight Session Pattern

The first pressure point is oil. Brent crude jumped 3.36% to settle at $101.21 a barrel, extending the move above $100 we covered earlier this week amid ongoing US-Iran tensions. The second pressure point is bonds. The 10-year Treasury yield climbed to 4.84%, touching as high as 4.857% intraday, its highest level since November 2023 and closing in on the psychologically significant 5% mark. Higher oil raises inflation expectations, and higher yields raise borrowing costs and make bonds more competitive with stocks, a combination that’s exactly why this stocks fall third straight session stretch has been so difficult for the market to shake off.

The Treasury’s Bond Buyback Wasn’t Enough to Calm Markets

Adding a new wrinkle to this stocks fall third straight session story, the Treasury Department announced a repurchase of longer-dated debt totaling $6 billion, triple the amount from its previous operation. This continues the same buyback strategy we covered when Ray Dalio warned about the debt crisis behind these Treasury moves, but this time the larger buyback still wasn’t enough to stop yields from climbing. Some market participants had actually expected an even bigger operation, with estimates ranging from $7 billion to $8 billion, according to market analyst Peter Boockvar, meaning the announcement itself may have disappointed traders hoping for a stronger signal.

An “Unusual Standoff” Between Stocks and Rates

Thomas Martin of Globalt Investments described the current moment as “an unusual standoff in market sentiment,” noting that optimism about stocks and expectations for higher interest rates were both running at extremes simultaneously, a combination he suggested is unlikely to persist together for long. That tension captures why this stocks fall third straight session run feels different from an ordinary pullback: investors haven’t given up on the market’s longer-term direction, but they’re increasingly uneasy about how much higher rates can climb before something has to give.

This uncertainty connects directly to the rate hike odds shift we covered after the last jobs report, where stronger-than-expected employment data pushed the odds of a September Fed rate hike higher. Markets are now watching for upcoming CPI and PPI inflation data, due before the Fed’s next policy meeting, for a clearer signal on where rates go from here.

What This Means for Your Own Money

  1. Three days of losses isn’t automatically a correction. A stocks fall third straight session stretch of roughly 2% combined across major indexes is a pullback worth watching, not yet the kind of drop that should trigger a portfolio overhaul.
  2. Rate-sensitive parts of your finances deserve attention right now. With yields at their highest since 2023, the save-or-pay-off-debt math we walked through is shifting further in favor of paying down high-rate debt rather than parking cash.
  3. Watch the CPI and PPI releases closely. Whichever way inflation data comes in over the next week will likely determine whether this stocks fall third straight session pattern extends into a fourth or fifth day, or reverses.
  4. Don’t try to time a bottom based on headlines alone. Both oil and Treasury yields have moved sharply and unpredictably in both directions this year; a sudden de-escalation in the Middle East or a cooler inflation print could reverse this pattern just as quickly as it started.

Bottom Line

This stocks fall third straight session stretch is being driven by two forces reinforcing each other: oil above $100 a barrel keeping inflation fears alive, and Treasury yields near their highest levels since 2023 raising the cost of capital across the entire market. Neither the Treasury’s larger bond buyback nor any single day’s trading has been enough to break the pattern yet. Whether Thursday brings a fourth straight decline or a reversal likely depends less on any one headline and more on whether oil prices and yields can both find some stability at the same time, something that hasn’t happened in over a week.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.

Brent Crude 100 a Barrel: Oil Just Crossed a Line It Hasn’t Touched Since July

Brent Crude 100 a Barrel: Oil Just Crossed a Line It Hasn’t Touched Since July

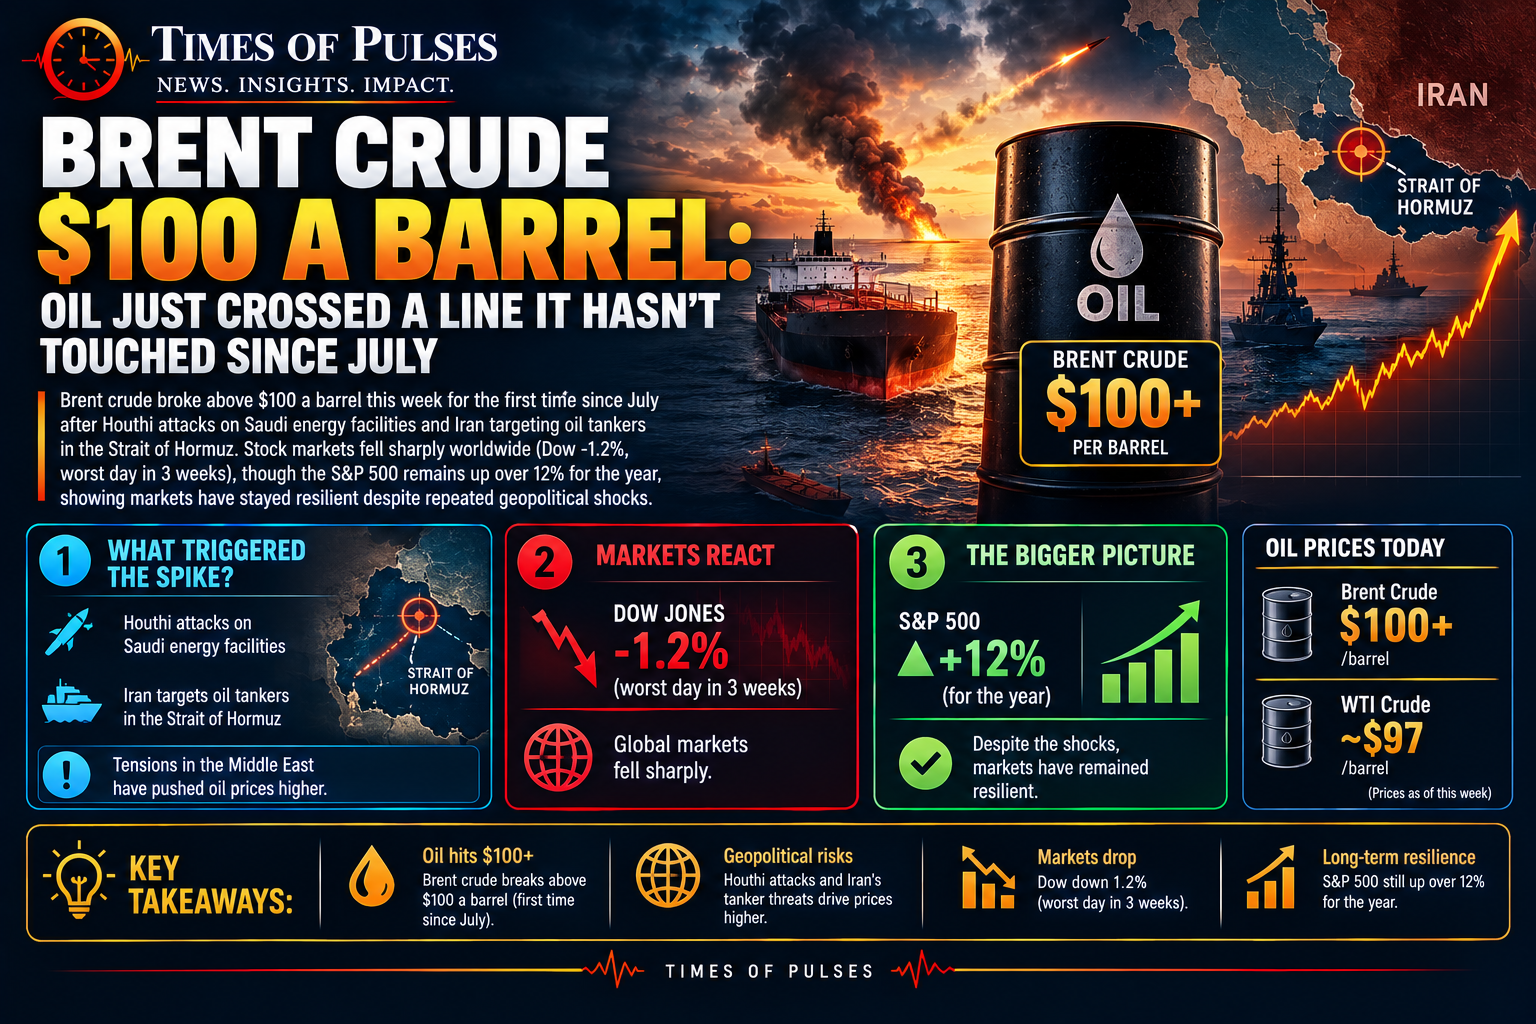
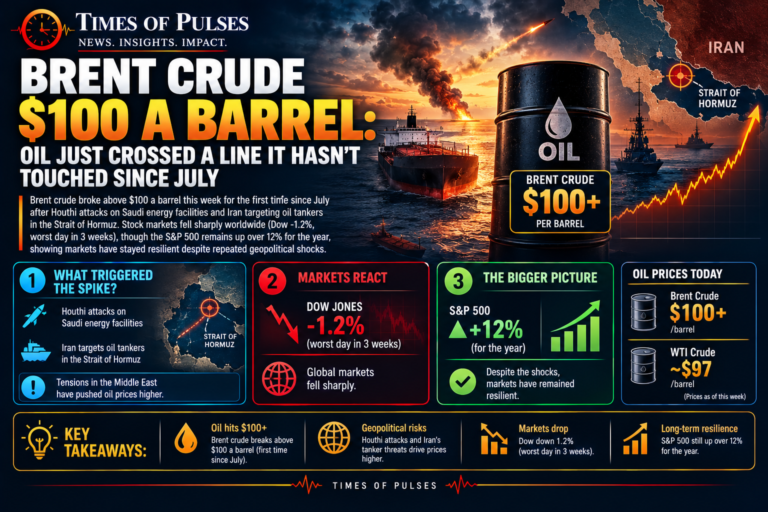
Oil just crossed a psychological line that traders have been watching all year. Brent crude 100 a barrel is no longer a hypothetical, the international benchmark broke above that level this week for the first time since July, and the move wasn’t gradual, it jumped more than 2% in a single session as a new wave of Middle East violence hit the headlines. This is the sharpest escalation yet in a story we’ve been tracking for weeks, and it’s rattling stock markets well beyond the energy sector.

Brent Crude 100 a Barrel: What Actually Pushed It There

The latest spike traces back to a fresh round of attacks over the weekend. Houthi forces struck Saudi energy facilities, and Iran said it targeted three oil tankers using an unauthorized route through the Strait of Hormuz, along with several US-linked vessels, in direct retaliation for American strikes on Iranian tankers. That combination, attacks on both Saudi infrastructure and shipping lanes simultaneously, is what pushed Brent crude past the 100 a barrel mark that markets had been watching nervously for months, with West Texas Intermediate, the US benchmark, climbing above $93 in the same move.

Why This Brent Crude 100 a Barrel Move Feels Different

We’ve covered this conflict escalating and cooling repeatedly this year, but Brent crude breaking 100 a barrel specifically matters because of what the International Energy Agency has called it: potentially the largest disruption to global oil supply in history. That’s a notably stronger characterization than earlier phases of this conflict, and it’s part of why this particular move above 100 a barrel is drawing more attention than previous spikes.

This latest chapter picks up directly where our coverage of the initial round of US-Iran strikes left off, prices climbing further and the underlying conflict widening rather than settling down, exactly the pattern that makes this market so difficult to call.

How Stock Markets Reacted

The response in equity markets was immediate and sharp. The Dow Jones Industrial Average dropped 1.2% on the day, its worst single-day performance in nearly three weeks, while the S&P 500 slid 0.6% and the Nasdaq Composite fell 0.3%. The 10-year Treasury yield briefly climbed above the closely watched 4.8% level, as rising oil added fresh concerns about inflation on top of everything else weighing on bond markets this year.

The reaction wasn’t confined to the US either. In Europe, the Stoxx 600 fell 0.69%, with the UK’s FTSE 100 down 0.32%, Germany’s DAX sliding 0.68%, and Italy’s FTSE MIB dropping 1.27%. Asian markets were mixed, Japan’s Nikkei 225 closed 0.19% lower while South Korea’s Kospi actually jumped more than 3%, a reminder that even during a broad risk-off move, reactions vary significantly by region and local market drivers.

The Bigger Picture: Markets Have Stayed Surprisingly Resilient

Here’s the part that might surprise you given how dramatic the Brent crude 100 a barrel headline sounds: despite what the IEA is calling a historic oil supply disruption, this Brent crude 100 a barrel move hasn’t derailed the broader market so far this year. Edward Jones’ market analysis noted that the S&P 500 had still gained more than 12% year-to-date through last week’s close, with international developed markets up over 15% and emerging markets up more than 27%. One investment chief described the current oil-driven volatility as “a little bit of a speed bump” rather than a trend-changing event, reflecting a market that’s been choosing to look past repeated geopolitical shocks so far this year.

That resilience isn’t guaranteed to continue. Analysts have flagged that further escalation, particularly during a seasonally weak month for stocks like September, could produce more volatility than markets have shown so far.

What This Means for Your Own Money

  1. If you’ve been following our coverage of investing in oil price volatility, this move above 100 a barrel is exactly the kind of scenario that framework was built for, a real supply-side shock rather than a minor headline blip.
  2. Don’t assume Brent crude 100 a barrel is now the new baseline. This conflict has moved in both directions repeatedly this year, and prices could ease just as quickly if tensions cool.
  3. Watch your gas and travel budget over the next few weeks. A jump this sharp typically shows up at the pump within days, even if it partially reverses later.
  4. Keep the bigger portfolio picture in mind. Even with oil spiking, broad market indexes remain up double digits for the year, a reminder not to make dramatic portfolio changes based on a single week’s headlines alone.

Bottom Line

Brent crude 100 a barrel for the first time since July is a genuine escalation, not just another headline in a conflict markets had started to shrug off. Attacks on Saudi energy infrastructure and oil tankers moving through the Strait of Hormuz mark a meaningfully different phase than the tension we’d been tracking in recent weeks. Whether this proves to be a temporary spike or the start of a longer stretch of elevated oil prices likely depends on what happens in the region over the next several days, not on anything markets can price in today.


This article is for informational purposes only and does not constitute financial or investment advice. Consult a licensed financial advisor before making changes to your investment portfolio.

Credit Utilization 2026: The Timing Trick That Controls Your Score in One Billing Cycle

0

Credit Utilization 2026: The Timing Trick That Controls Your Score in One Billing Cycle

If you’re trying to get real credit control over your finances, credit utilization is the single lever you can move fastest. Unlike payment history, which takes years of consistency to build, credit utilization 2026 can shift your score within a single billing cycle, and most people are managing it the wrong way entirely.

What Credit Utilization 2026 Actually Measures

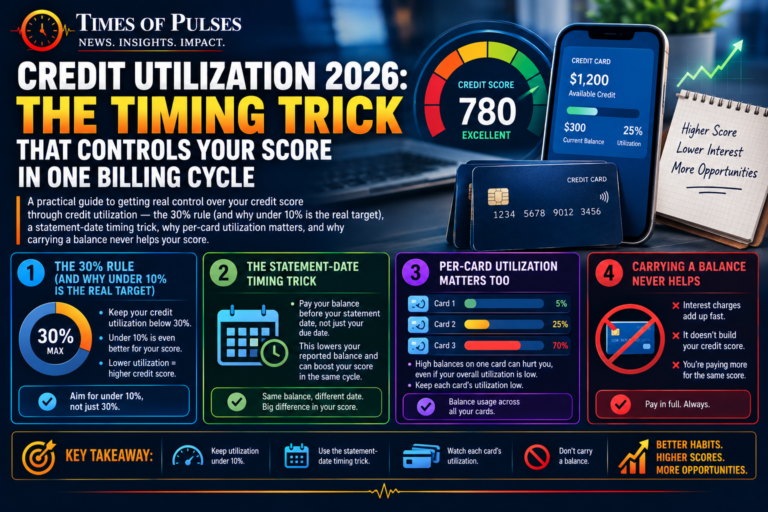
Credit utilization is simply your revolving credit balance divided by your credit limit, and it accounts for roughly 30% of your FICO score, the second-biggest factor after payment history. If you have a $3,000 balance on a card with a $10,000 limit, your utilization on that card is 30%. This applies only to revolving credit, credit cards and lines of credit, not installment loans like your mortgage or auto loan, which is why credit utilization 2026 strategies focus almost entirely on card balances.

The 30% Rule Is a Floor, Not a Goal

You’ve probably heard that you should keep utilization under 30%. That’s true, but it’s the minimum standard for avoiding real damage, not the target for genuine credit control. FICO’s own data shows that scores above 760 are consistently associated with utilization under 10%. Here’s roughly how the damage scales:

  • 1% to 9% utilization: the sweet spot for maximum points
  • 10% to 29%: still counts as “low,” minor impact
  • 30% to 49%: moderate damage, scores start dropping noticeably
  • 50% to 74%: significant damage, 30 to 60 point drops are common
  • 75% and above: major damage to your score

Interestingly, 0% utilization isn’t actually optimal either. Lenders want to see that you can use credit responsibly, not that you avoid it entirely, so the real target for credit utilization 2026 is that narrow 1% to 9% band, not zero.

The Statement-Date Timing Trick Most People Miss

Here’s the detail that separates people who understand credit utilization 2026 from people who don’t: card issuers report your balance to the credit bureaus on your statement closing date, not your payment due date. Those are usually two different dates, and most people only think about the due date.

That means you can carry a balance all month, use your card normally, and still show up with low utilization, as long as you pay it down before the statement closes rather than waiting until the due date. According to a detailed breakdown of this strategy, paying a few days before your statement closes is often the single fastest way to lower the number that actually reaches the bureaus, without changing your spending habits at all.

Per-Card Utilization Matters Just as Much as Overall

Real credit control means watching more than just your combined utilization across all cards. Scoring models look at utilization per card as well as your overall ratio, which means one maxed-out card can hurt your score even if your total utilization across every card looks completely fine. If you’re carrying $9,000 on a $10,000-limit card and $200 on a $5,000-limit card elsewhere, your overall utilization might look reasonable at 61%, but that first card’s individual 90% utilization is doing real damage on its own.

This is also why requesting a credit limit increase, without increasing your spending, can meaningfully help your credit utilization 2026 numbers. A higher limit against the same balance immediately lowers your ratio, with no new debt involved.

The Biggest Myth: Carrying a Balance Helps Your Score

This myth costs people real money for zero benefit. Carrying a balance month to month does nothing positive for your credit utilization 2026 or your score, it simply means you’re paying interest, often north of 24% APR on the average card, for no scoring advantage whatsoever. Paying your balance in full every month, ideally before the statement closes, is strictly better for both your score and your wallet. There’s no version of “strategic debt” that helps your credit score.

What This Means for Your Own Credit

  1. Figure out your statement closing dates for every card you carry, not just the due dates, since that’s the number that actually reaches the bureaus.
  2. Check per-card utilization, not just your overall number. If you’re working on building credit from no history, a single new card sitting near its limit can undo progress elsewhere.
  3. Never carry a balance intentionally. If you’re currently working through paying off credit card debt fast, understand that the interest you’re paying isn’t buying you any score benefit at all.
  4. A credit limit increase request costs nothing and can help immediately, as long as you don’t use it as an excuse to spend more. Any extra cash you free up by managing this well is worth parking in a high-yield savings account rather than letting it sit idle.

Bottom Line

Real credit control comes down to understanding the mechanics most people never bother to learn: the 30% rule is a ceiling, not a goal, per-card ratios matter as much as your overall number, and the date your issuer reports your balance matters more than the date you’re required to pay. Getting credit utilization 2026 genuinely under control isn’t about opening more accounts or dramatically changing your spending, it’s about a handful of specific, low-effort habits applied consistently.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor or credit counselor for guidance specific to your situation.