Home Blog Page 5

Grocery Prices Are Americans’ Top Financial Worry — Here’s What the New Survey 2026 Actually Found

0

Grocery Prices Are Americans’ Top Financial Worry — Here’s What the New Survey 2026 Actually Found

Forget housing, gas, or healthcare — when Americans are asked what’s actually stressing their wallet the most right now, one answer keeps coming out on top: the grocery store. Multiple 2026 surveys, from different research groups using different methodologies, have all landed on the same conclusion. Here’s what the data actually shows, why groceries specifically hit harder than other rising costs, and what you can realistically do about it.

The Numbers Behind Grocery Prices as Americans’ Top Financial Worry

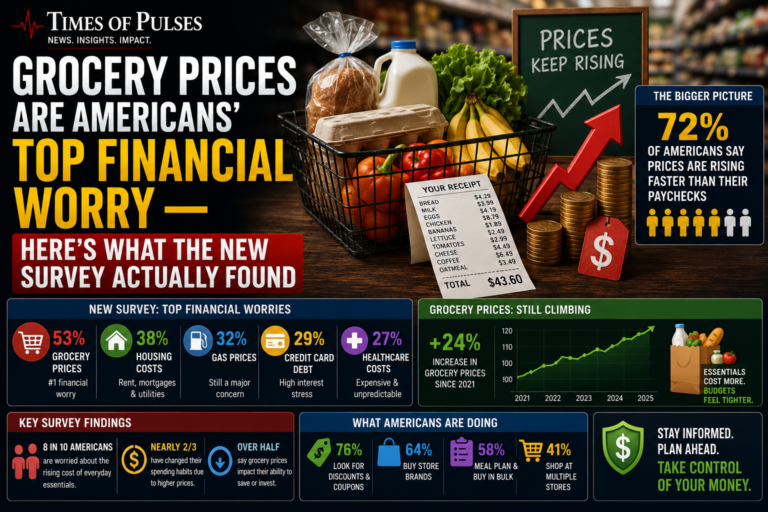
The consistency across separate surveys this year is genuinely striking. KeyBank’s 2026 Financial Mobility Survey found that 58% of respondents cited grocery prices as their top financial concern, well ahead of housing costs at 44% and healthcare expenses at 30%. A separate survey from The Kitchen Table Project, conducted by Global Strategy Group among 1,100 registered voters, found 63% cited groceries as their top financial pressure — compared to just 36% for housing, 33% for gasoline, and 29% for utilities.

Nearly 9 in 10 Americans (88%) say they’ve adjusted their financial behavior specifically in response to rising costs, and 67% say the overall cost of living is placing significant pressure on their household, according to the same research.

Why Grocery Prices Hit Differently Than Other Rising Costs

It’s worth understanding why groceries specifically top the list, even when housing and healthcare costs are also climbing. Food is unavoidable, recurring, and highly visible in a way other expenses aren’t. You can delay a car repair or negotiate a rent renewal, but you can’t skip eating, and you see the price every single week at checkout. That visibility makes grocery inflation feel more immediate and painful than costs that show up less frequently, like an annual insurance premium or a mortgage rate.

The actual price data backs up the frustration: food-at-home prices have increased more than 30% since January 2020, and are up roughly 25% over just the past five years, according to Urban Institute research. Fruit and vegetable prices specifically rose 5.3% over the past year alone, per Bureau of Labor Statistics data, with meat and poultry singled out repeatedly across surveys as the most painfully unaffordable category.

What’s Actually Driving Grocery Prices Higher

When surveyed about the cause, Americans point to a mix of factors, and they’re not entirely wrong:

  • Tariffs and trade restrictions were cited most often (48%) as a driver of higher costs
  • Corporate pricing practices were a close second (46%), with many respondents believing companies have raised prices to increase profits beyond what rising input costs alone would justify
  • Supply-side shocks have compounded over recent years — the pandemic, avian influenza outbreaks affecting egg and poultry supply, drought affecting crop yields, and geopolitical disruptions to fertilizer and diesel costs tied to the ongoing Middle East conflict we’ve covered extensively this year

Notably, 67% of Americans say current grocery prices are simply “unfair,” and 82% believe elected officials have the power to bring costs down if they choose to act — reflecting genuine, bipartisan frustration that crosses party lines.

How Households Are Actually Coping (And Where It’s Getting Risky)

The survey data reveals some genuinely concerning coping patterns. A separate Urban Institute analysis found that many families are turning to credit to manage grocery costs: about 35% of adults paid for groceries with a credit card and paid the bill in full, which is a manageable habit. But another 20% used a credit card and carried a balance, and 8.7% didn’t even make their minimum payment consistently — meaning grocery costs are now directly feeding into the credit card minimum payment trap we’ve covered in detail before, where average APRs run above 20%.

Beyond credit, roughly 1 in 3 families report buying less produce specifically, according to a separate survey from Advance America, raising real questions about nutrition trade-offs as households stretch tighter budgets.

Why This Likely Isn’t Ending Soon

Unfortunately, the forward-looking data isn’t especially reassuring. Three-quarters of middle-income Americans expect grocery prices to keep climbing over the next six months, according to Primerica’s Q1 2026 survey, and the USDA itself projects food-at-home prices will rise another 2.8% in 2026. The next official Consumer Price Index reading, covering July data, is due August 12 — worth watching closely given how central grocery costs have become to this inflation conversation.

How to Actually Manage Rising Grocery Costs

  1. Shift your credit card grocery spending to a card you pay in full monthly. If groceries are pushing you toward carrying a balance, that’s a sign to revisit your overall budget rather than let a recurring necessity quietly become expensive debt.
  2. Focus savings efforts on the specific categories driving the pain. Since meat, poultry, and produce are repeatedly flagged as the most painful categories, look specifically at bulk buying, store brands, or seasonal produce in those areas rather than trying to cut broadly across your entire grocery list.
  3. Track your actual grocery spending trend, not just individual trip totals. Comparing month-over-month spending helps you see whether your household is keeping pace with the roughly 3% year-over-year food inflation, or falling further behind.
  4. Build grocery cost volatility into your broader budget, the same way we’ve suggested building flexibility for gas prices and tariff-driven price increases this year — groceries deserve the same buffer treatment given how consistently they’re outpacing general inflation.
  5. Watch the August 12 CPI report specifically for the food component, since another notable increase would confirm this pressure is continuing rather than easing.

What You Should Actually Do This Week

  1. Review your last three months of grocery receipts to identify which specific categories are driving your own cost increases
  2. Check whether grocery spending is contributing to a credit card balance you’re not paying off in full, and treat that as a genuine budget priority to address
  3. Compare store brand alternatives specifically in the meat, poultry, and produce categories most surveys flag as the biggest pain points
  4. Build a specific grocery buffer into your monthly budget rather than treating each price increase as a surprise

Bottom Line

Grocery prices topping Americans’ list of financial worries isn’t a matter of perception — it’s backed by consistent data across multiple independent surveys, real price increases exceeding 25-30% over recent years, and forward-looking expectations that costs will keep climbing. The visible, unavoidable, weekly nature of grocery spending makes this pressure feel more immediate than other rising costs, even ones that may cost more overall. Understanding which specific categories are driving your own household’s increase, and building genuine budget flexibility around it, is a more effective response than waiting for prices to simply come back down.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor for guidance specific to your household budget.
“Moneymaxxing” Is Everywhere on Social Media Right Now — Here’s What It Actually Means

0

“Moneymaxxing” Is Everywhere on Social Media Right Now — Here’s What It Actually Means

If you’ve scrolled social media lately, you’ve probably seen “maxxing” attached to everything — looksmaxxing, sleepmaxxing, vacationmaxxing. Now finance has its own version, and moneymaxxing is being called something bigger than just another trend. CNBC reported this week that financial advisors are describing it as a genuine “cultural shift,” not a fad that fades in a few months. Here’s what moneymaxxing actually means, why it’s resonating so widely, and how to actually apply it to your own finances.

What Moneymaxxing Actually Is

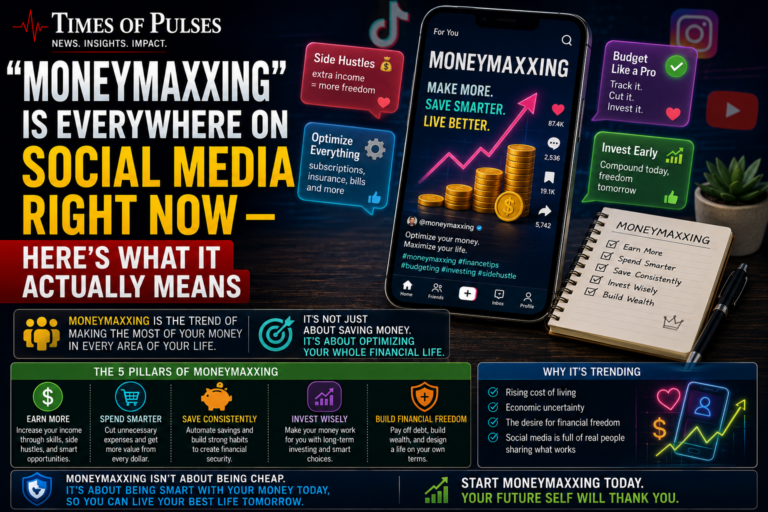
Moneymaxxing is the practice of intentionally optimizing every dollar you have — reviewing your spending, savings, and investments with fresh eyes and asking a simple question: am I actually making the most of what I already have? Certified Financial Planner Felicia Greenwald, who helped popularize the term after a LinkedIn post, describes it as a modern, gamified take on financial habits people have always had access to, just repackaged in a way that feels more engaging and less intimidating.

Common moneymaxxing tactics include:

  • Moving savings into the highest-yielding accounts available, rather than leaving cash in a low-interest account
  • Reviewing and reallocating investments to make sure they still match your actual goals
  • “Pointsmaxxing” — squeezing maximum value out of credit card rewards and points programs
  • Cutting unused subscriptions and genuinely unnecessary recurring expenses
  • Using AI-powered budgeting tools to spot spending patterns you might otherwise miss

Why Moneymaxxing Is Resonating So Widely Right Now

The timing isn’t random. Northwestern Mutual’s 2026 Planning & Progress Study found that over half of millennials remain financially dependent on their parents, and Americans on average don’t expect to reach full financial independence until age 37. Separate 2025 data from the same company found that 43% of millennials don’t have a retirement account, 31% lack a savings account, and a striking 79% of Gen Z and 66% of millennials don’t have any emergency fund at all — a gap we’ve covered in detail in our recent reporting on the $2000 emergency fund crisis.

Jack Howard, head of money wellness at Ally Bank, told reporters that moneymaxxing appears to have real staying power specifically because it focuses on building everyday habits rather than chasing a quick fix — a genuinely different approach than most viral finance trends, which tend to burn out within a season.

The Generational Split Inside Moneymaxxing

Interestingly, moneymaxxing doesn’t look the same across age groups. Millennials tend to approach it through stability-focused habits — budgeting discipline, bill timing, and long-term planning, reflecting the financial caution many developed coming of age during and after the 2008 recession. Gen Z’s version leans more toward flexibility, rewards optimization, and using digital tools to make everyday spending “work harder,” reflecting a generation that grew up with mobile banking and instant financial data at their fingertips.

A related, more intense version of this same shift has emerged too: Bloomberg recently profiled young “retirement-maxxers” — Gen Z savers, some in their mid-20s, aggressively saving 50% or more of their income, with one profiled saver reaching $300,000 saved by age 26 through disciplined, sustained sacrifice.

Why Financial Advisors Are Taking Moneymaxxing Seriously

This isn’t just a social media curiosity to industry professionals. A CFP Board Ambassador specifically compared moneymaxxing’s underlying philosophy to the established FIRE (Financial Independence, Retire Early) movement, noting it reframes genuinely sound financial principles in a way that feels more accessible and less overwhelming to people who might otherwise avoid thinking about their finances altogether.

That accessibility matters. Financial content consumption is genuinely high among younger generations, yet the preparedness gaps above show that consuming financial content and actually acting on it are two very different things. Moneymaxxing’s appeal is that it turns “optimize your finances” from an abstract goal into something that feels more like a game with visible, trackable wins.

How to Actually Start Moneymaxxing Yourself

  1. Get a genuinely clear picture of where you stand first. List every account, balance, and recurring expense before trying to optimize anything — you can’t maximize what you haven’t mapped out.
  2. Audit your savings account rate. If your emergency fund or savings sits in a low-interest account, moving it to a high-yield option, something we’ve covered in our guide to the best high-yield savings accounts, is one of the simplest, highest-impact moneymaxxing moves available.
  3. Review your credit card rewards structure. If you’re not maximizing points, cashback, or benefits you’re already entitled to on cards you already use, that’s value being left on the table every month.
  4. Cut genuinely unused subscriptions, not necessarily everything enjoyable — moneymaxxing isn’t about deprivation, it’s about intentional spending.
  5. Use technology to spot patterns you’re missing. AI-powered budgeting tools can surface spending trends that are easy to overlook when reviewing a bank statement manually.
  6. Curate your financial social media feed deliberately. Following accounts and people with similar financial goals can provide both practical ideas and a sense of accountability, according to behavioral finance experts.

What You Should Actually Do This Week

  1. Pick one moneymaxxing category to start with — savings rate, credit card rewards, or subscription audit — rather than trying to overhaul everything at once
  2. Check your current savings account APY against current best high-yield options, since this is often the single fastest win available
  3. Set a specific, trackable target, since part of moneymaxxing’s appeal is treating financial progress like a game with visible milestones
  4. Revisit your progress monthly, not just once, since the “everyday habits” framing is what experts say gives this trend more staying power than past viral finance fads

Bottom Line

Moneymaxxing isn’t introducing radically new financial concepts — reviewing your spending, chasing better interest rates, and using rewards programs fully are all ideas that have existed for decades. What’s genuinely different is the framing: turning financial optimization into an accessible, almost gamified habit rather than an intimidating, occasional chore. Given the real preparedness gaps behind the trend — millions of Americans without emergency funds or retirement accounts — a cultural shift that makes people actually engage with their money, whatever you call it, is worth taking seriously.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor for guidance specific to your financial situation.

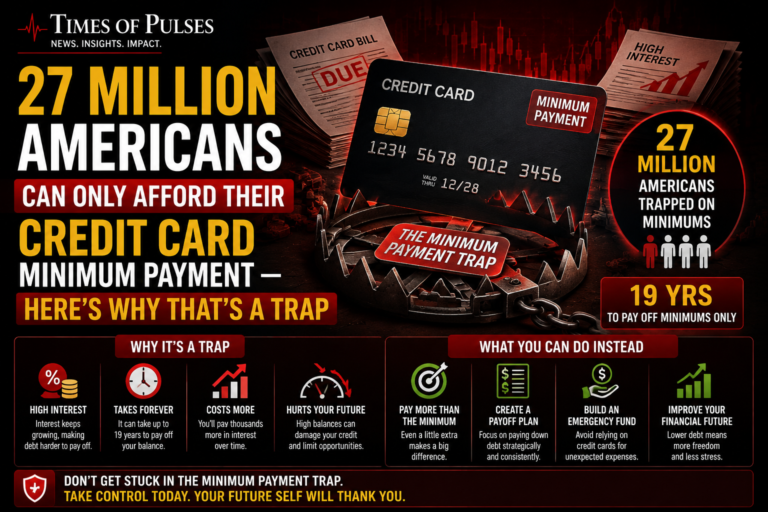
27 Million Americans Can Only Afford Their Credit Card Minimum Payment — Here’s Why That’s a Trap

0

27 Million Americans Can Only Afford Their Credit Card Minimum Payment — Here’s Why That’s a Trap

Here’s a number worth sitting with: more than 27 million Americans can currently only afford to make the minimum payment on their credit cards. If that’s you, or someone in your family, you’re not failing at money management — you’re caught in a mathematically brutal trap that even financial experts say most people misunderstand. Here’s exactly why the credit card minimum payment trap works against you, and a real way out.

The Scale of the Credit Card Minimum Payment Problem

According to a March 2026 report from The Century Foundation and Protect Borrowers, roughly 111 million Americans — about half of all active cardholders — now carry a credit card balance from month to month, up 17% from just five years ago. Of that group, more than 27 million can only afford the credit card minimum payment each month, not a dollar more.

The Consumer Financial Protection Bureau’s own data confirms this is a genuine, worsening trend: 15% of general-purpose cardholders made only the minimum payment in 2024, the highest share recorded since at least 2015. Separately, the Federal Reserve Bank of Philadelphia found that over 11% of accounts at the country’s largest banks were minimum-payment-only in the fourth quarter of 2024 — also a 12-year record.

Why the Credit Card Minimum Payment Feels Responsible (But Isn’t)

This is the part most people genuinely don’t understand: an Experian survey found that 40% of Americans mistakenly believe making the credit card minimum payment is an effective debt management strategy. It feels responsible — your account stays current, you avoid late fees, and no one calls you about collections. But the math tells a very different story.

Take a real example: a $10,000 balance at 20% APR, making only minimum payments, takes 19 years to pay off and costs $21,600 total — more than double the original balance. On a $15,000 balance at 22% APR, if the minimum payment is $300 a month, roughly $275 of that goes straight to interest, leaving just $25 a month actually reducing what you owe.

This is exactly why so many people describe minimum payments as “paying but not getting anywhere” — because mathematically, that’s almost exactly what’s happening.

Why This Is Getting Worse Right Now

A few forces are compounding to push more people into the credit card minimum payment trap specifically in 2026:

Interest rates remain elevated. The average APR across all credit card accounts sat at 20.97% in the most recent quarter, with new card offers averaging even higher at 23.72%. The CFPB found private-label card APRs reaching 31.3% — the highest level recorded since tracking began.

Total debt has hit a record high. Total U.S. credit card debt exceeded $1.17 trillion in early 2026, and Americans paid an estimated $181 billion in credit card interest in 2025 alone — more than double the $75 billion paid just four years earlier.

Income pressure is squeezing the same households from multiple directions. As we’ve covered in our reporting on rising housing costs and paychecks under pressure this year, the same economic squeeze pushing people toward credit cards in the first place is also making it harder to pay down what they’ve already borrowed.

The gap is worse for younger and lower-income households. Bankrate’s 2026 survey found 56% of cardholders earning under $50,000 annually carry debt month to month, and nearly 45% of college students using credit cards report paying only the minimum.

The Real Cost of the Credit Card Minimum Payment Habit

Beyond the raw math, staying on minimum payments carries compounding risks:

  • 19% of credit card debtors are specifically worried they might not be able to make even the minimum payment at some point in the next six months, according to Bankrate’s 2026 survey
  • 22% believe they will never get out of credit card debt at all — a genuinely alarming sign of how trapped this pattern can feel
  • Every dollar spent servicing old debt is a dollar unavailable for building the emergency fund we discussed in our recent coverage of the $2000 emergency fund gap, creating a cycle where new financial shocks just add to the same growing balance

How to Actually Break Out of the Credit Card Minimum Payment Trap

  1. Pay anything above the minimum, even small amounts. On that $15,000 example above, bumping your payment from $300 to $400 a month dramatically cuts both your payoff timeline and total interest paid, since more of each payment starts attacking principal instead of just covering interest.
  2. Use the avalanche or snowball method deliberately, rather than spreading small extra payments randomly across multiple cards. Our full guide on how to pay off credit card debt fast walks through both approaches in detail, including which one fits different situations.
  3. Look into a balance transfer card if your credit qualifies. Moving a high-interest balance to a 0% introductory APR card, even temporarily, means every payment goes toward principal instead of interest during that window.
  4. Consider a debt consolidation loan for genuinely overwhelming balances. Combining multiple high-APR cards into one fixed-rate loan, often well below 20%, can meaningfully cut what you’re paying in interest each month.
  5. Contact a nonprofit credit counselor if minimum payments themselves feel unaffordable. Agencies affiliated with the National Foundation for Credit Counseling can sometimes negotiate lower rates through a structured debt management plan, without the credit damage that debt settlement carries.
  6. Stop new charges on cards you’re actively paying down. Every new purchase on a card carrying a balance immediately starts accruing interest, actively working against the progress you’re making.

What You Should Actually Do This Week

  1. Calculate what you’re actually paying in interest on your current balances using your card’s APR and balance — seeing the real number is often the push needed to pay more than the minimum
  2. Identify your highest-APR card first and prioritize extra payments there, regardless of which balance is largest
  3. Check if you pre-qualify for a balance transfer card without a hard credit inquiry, which most major issuers now allow
  4. If you’re among the 19% worried about missing even a minimum payment, contact your card issuer proactively — many have hardship programs that are far better than defaulting

Bottom Line

The credit card minimum payment trap catches 27 million Americans not because they’re careless with money, but because minimum payments are specifically structured to feel responsible while barely denting the actual debt. Understanding the real math — how little of each minimum payment actually reduces what you owe — is the first step toward escaping it. The good news: even modest extra payments, applied strategically, can cut years off your payoff timeline and thousands off your total interest, without needing a dramatic change in your monthly budget.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor or nonprofit credit counselor for guidance specific to your debt situation.

Could You Cover a $2000 Emergency Right Now? 1 in 4 Americans Say They Can’t

0

Could You Cover a $2000 Emergency Right Now? 1 in 4 Americans Say They Can’t

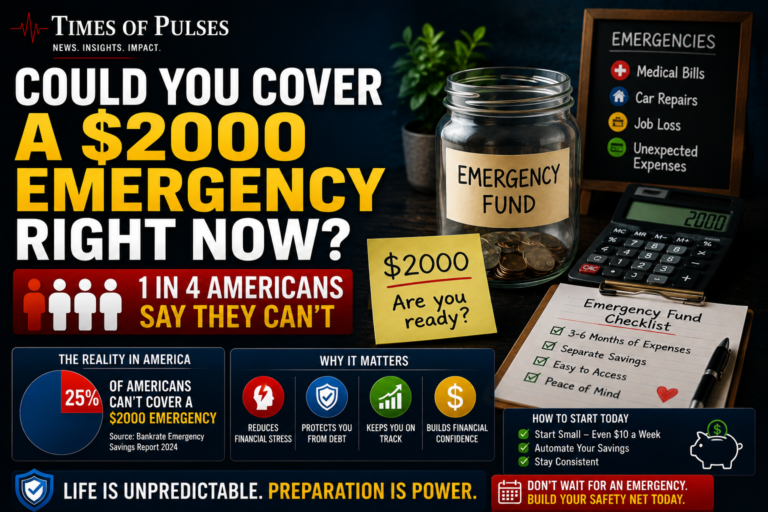
Here’s an uncomfortable question worth asking yourself honestly: if your car broke down tomorrow, or you had a sudden medical bill, could you cover a $2000 emergency without going into debt? According to new 2026 polling, a full quarter of Americans would say no — and another chunk aren’t confident either way. If that question made you pause even for a second, you’re far from alone, and understanding why this gap exists is the first step to closing it.

The Real Numbers Behind the $2000 Emergency Question

When Gallup specifically asked Americans about their confidence in handling a $2000 emergency, the answers revealed a genuine national vulnerability: only 36% said they’re “certain” they could cover it, 19% said they “probably could,” 13% said “probably could not,” and a striking 26% said they’re “certain they could not.” Add those last two groups together, and nearly 4 in 10 Americans are staring down real financial danger the moment an unplanned expense hits.

This isn’t a fringe problem. It’s showing up across nearly every measure of financial well-being right now. A record 55% of Americans say their financial situation is getting worse — the highest share since the Great Recession, according to Gallup’s annual survey. And 88% report feeling some form of financial stress heading into 2026, per polling from the National Endowment for Financial Education.

Why So Many People Are One Emergency Away From Trouble

A few forces are compounding at once to create this $2000 emergency gap:

Affordability concerns dominate everything else. Inflation and the high cost of living remain the single biggest financial worry for Americans, cited by a wide margin over every other concern — housing, healthcare, energy, and transportation costs are all squeezing the same monthly budget simultaneously, leaving less room to build a cushion.

Debt is quietly eating into people’s ability to save. 40% of households say paying down debt is their biggest anticipated expense this year, and 28% report specifically worrying about making minimum credit card payments — up from just 17% back in 2021. When more of your paycheck goes toward debt service, less is available to build the emergency fund that would prevent needing that debt in the first place.

Real income growth hasn’t kept pace. Median household income has seen minimal real growth once adjusted for inflation, while the cost of essentials — housing, food, transportation — has climbed steadily, shrinking the disposable income households would otherwise use to build savings.

Unexpected setbacks are common, not rare. 51% of U.S. adults report experiencing an unexpected money emergency within just the last five years, and that rate is substantially higher for households already carrying debt or raising children — meaning the people least equipped to handle a shock are also the most likely to face one.

Why This $2000 Number Specifically Matters

Financial experts frequently use the $2000 threshold because it represents a realistic, common emergency — a car repair, an ER visit copay, a broken appliance, or a plane ticket for a family emergency. It’s deliberately not an extreme, rare catastrophe; it’s the kind of expense most households will genuinely face within any given year or two. That’s exactly what makes the 26% “certain they could not” figure so significant: this isn’t about surviving something rare, it’s about handling something common.

What Happens When You Can’t Cover the Emergency

When a household can’t absorb a $2000 shock from savings, the money has to come from somewhere else, and the alternatives are almost always more expensive:

  • Credit card debt at double-digit interest rates, turning a one-time $2000 expense into a much larger total cost over time if only minimum payments are made
  • Borrowing from retirement accounts, which can trigger penalties and taxes while permanently reducing long-term compounding growth
  • Payday loans or buy-now-pay-later services, both of which we’ve covered before as genuinely risky when used to cover essentials rather than planned purchases
  • Selling assets at an inopportune time, sometimes at a loss, simply because cash is needed immediately

How to Actually Close Your Own $2000 Emergency Gap

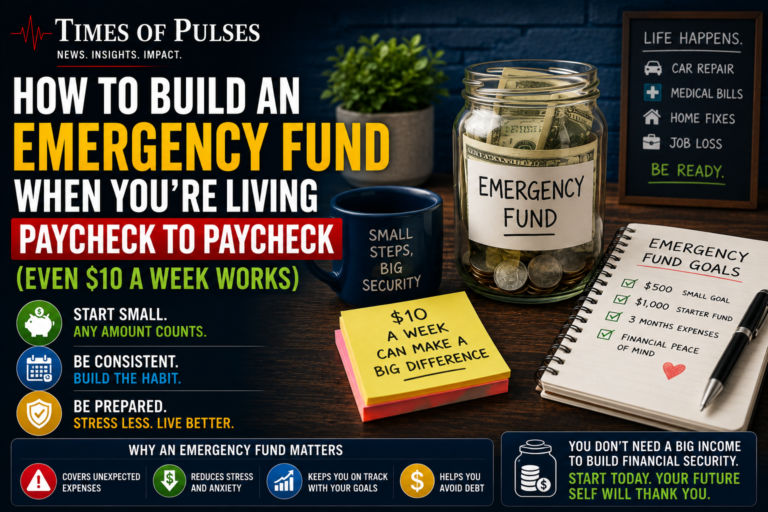
  1. Start with a specific, smaller target, not the full amount at once. Building toward $500 first, then $1,000, then $2000, is far more sustainable than trying to save the whole cushion in one push. Progress, not perfection, is what actually gets households out of the “certain I could not” category.
  2. Automate a fixed amount every payday, even if it’s small. As we’ve discussed in our guide to building a portfolio from zero, automatic, consistent contributions reliably outperform sporadic, larger deposits that depend on remembering or having extra cash on hand.
  3. Keep this money genuinely separate and boring. A high-yield savings account, kept apart from your everyday checking account, reduces the temptation to dip into it for non-emergencies while still earning meaningful interest — we’ve covered specific current rate options in our guide to the best high-yield savings accounts.
  4. Attack high-interest debt in parallel, not instead of saving. Even a small emergency cushion, alongside a real debt payoff plan, prevents the cycle where every setback adds to the same credit card balance you’re trying to pay down.
  5. Treat windfalls as emergency fund fuel, not spending money. Tax refunds, bonuses, or unexpected extra income are some of the fastest ways to jump from “probably could not” to “certain I could,” without requiring any change to your regular monthly budget.
  6. Recalculate your actual number. $2000 is a useful national benchmark, but your real target should reflect your specific situation — someone with a car, dependents, or health conditions may reasonably need a larger cushion than someone without those specific risks.

What You Should Actually Do This Week

  1. Answer the $2000 question honestly for yourself — certain you could, probably could, probably couldn’t, or certain you couldn’t — and treat that answer as your real starting point
  2. Open a dedicated high-yield savings account if you don’t already have one specifically earmarked for emergencies
  3. Set one automatic transfer, even $25 a paycheck, rather than waiting until you feel you have “extra” money
  4. If debt is actively preventing you from saving, tackle your highest-interest balance first using a specific plan rather than a vague intention

Bottom Line

The fact that a quarter of Americans can’t confidently cover a $2000 emergency isn’t a personal failing — it reflects genuinely difficult, well-documented economic pressure hitting households from multiple directions at once: elevated costs, stagnant real income, and rising debt service. But the path out of the “certain I could not” category is remarkably consistent regardless of where you start: a specific target, an automatic contribution, and a separate account that stays untouched until you actually need it. The gap is real, but it’s also genuinely closeable, one automated deposit at a time.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor for guidance specific to your emergency savings and debt situation.

Stock Market Rally Today: Stocks Near Record Highs, Gold Tops $4,000, and the AI Trade Is Suddenly Back On

0

Stock Market Rally Today: Stocks Near Record Highs, Gold Tops $4,000, and the AI Trade Is Suddenly Back On

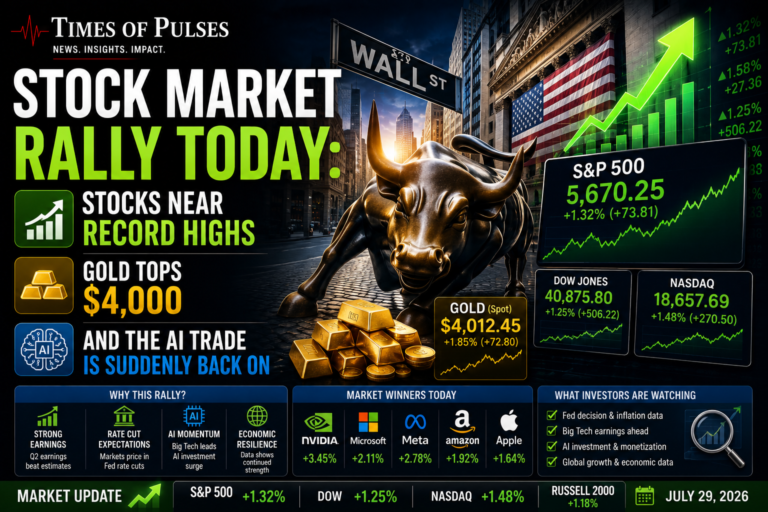
The stock market rally today is one of those rare stretches where almost every major asset class seems to be throwing its own party at the same time — and for very different reasons. The S&P 500 closed at 7,600.50, up 1.48% and its highest close since early June, sitting just short of a fresh record. Gold is holding above the symbolic $4,000-an-ounce mark. And the “AI trade,” which spent much of July looking shaky, is suddenly back in favor on Wall Street. Three storylines, one wild week — let’s walk through what’s actually going on.

What’s Driving the Stock Market Rally Today

The most immediate trigger is geopolitical: President Trump paused Iran strikes, and markets responded almost instantly with relief. That pause, combined with a genuine tech-led rebound, marked a sharp reversal from July’s technology selloff — a shift that comes right on the heels of bank earnings season, which had already given investors an early read on how resilient the broader economy really is. Investors had spent weeks worrying that massive AI infrastructure spending wasn’t translating into real returns — this week, that confidence came roaring back, and prediction markets are leaning bullish too, with traders pricing in a strong probability that stocks extend their gains.

It’s worth sitting with how fast sentiment flipped here. A few weeks ago, chip stocks were bleeding and analysts were openly questioning whether the AI spending boom made financial sense. Now the same sector is leading a rally that’s pushing the S&P 500 toward record territory. Markets, as always, don’t do nuance well — they do mood swings.

Meanwhile, Gold Is Quietly Having a Historic Year Too

Here’s the part that makes the stock market rally today genuinely interesting rather than just another “stocks go up” headline: gold is holding above $4,000 an ounce at the same time equities are rallying — live coverage from 24/7 Wall St has the gold spot price hovering near $4,064, with Deutsche Bank calling the metal’s current run an “explosive phase.” Normally these two move in opposite directions — gold is the classic safe-haven trade, and it tends to fall when investors feel confident enough to pile into stocks. Right now, both are climbing, which tells you the market isn’t fully convinced the calm will last. Easing Treasury yields are giving gold room to hold its gains even as risk appetite for equities returns.

The Part Nobody’s Cheering About: Asia Isn’t Buying the Optimism

Not every corner of the globe is celebrating the stock market rally today the way Wall Street is — especially with oil prices still sitting near $90 a barrel from the same Iran conflict that just eased. Asian stocks actually failed to follow Wall Street’s tech-led rally, with persistent volatility in South Korea’s Kospi Index underscoring lingering concerns over whether the AI trade is really back for good, or just having a good week. That’s a meaningful signal — Asian markets are deeply tied to the semiconductor supply chain that powers the AI boom, and if they’re not fully convinced, that’s worth paying attention to before assuming this rally has legs.

What’s Coming Next That Could Make or Break This

A closely watched ISM services report is due out shortly, and it’s expected to shape Fed rate-cut expectations heading into the fall. The stakes here are genuinely high: any reading below the key 54 threshold would likely reignite aggressive bets on a Fed pivot toward cuts, which tends to be a mixed bag — good for borrowing costs, but sometimes read by markets as a sign the economy is cooling more than expected. You can follow live market updates here as the report lands.

What This Means for You

  1. If you’re invested in a broad index fund, this week’s stock market rally today is good news on paper, but don’t mistake one strong week for a guaranteed trend. Markets that swing this fast on geopolitical headlines can reverse just as quickly.
  2. If you’re considering buying gold as a hedge, remember it’s already near historic highs — chasing an asset after a big run is rarely the ideal entry point. Dollar-cost averaging tends to beat trying to time a peak.
  3. Watch the ISM services report if you’re tracking mortgage rates or planning any major borrowing decision soon — it could shift Fed rate-cut expectations meaningfully in either direction.
  4. Don’t overreact to AI stock swings. The sector has now whipsawed from a selloff to a rally within weeks. If you own tech-heavy positions, this kind of volatility is likely to continue until the market gets more clarity on whether AI spending is truly paying off.

Bottom Line

The stock market rally today captures everything that makes 2026 markets so hard to read: stocks near record highs, gold near record highs, a paused conflict, a still-nervous Asia, and a critical economic report looming just days away. When stocks and gold rally together, it usually means the market is optimistic and hedging its bets at the same time — a genuinely rare combination worth understanding rather than just riding blindly. The smartest move right now is the one that’s worked all year: stay diversified, avoid chasing any single asset after a sharp run-up, and let the next data release — not this week’s headlines — guide your next decision.


This article is for informational and educational purposes only and does not constitute financial or investment advice. Markets are inherently unpredictable; consult a licensed financial advisor before making investment decisions.

Trumps Retirement Plan Could Force Your Employer to Save for You

0

Trumps Retirement Plan Could Force Your Employer to Save for You

What if saving for retirement wasn’t optional for your employer anymore? That’s essentially the idea President Trump has been floating since early July: borrowing Australia’s “superannuation” system, where employers are legally required to put money into every worker’s retirement account, whether the worker asks for it or not. No legislation exists yet, but the concept is worth understanding now, because it points at a real gap in how most Americans currently save for retirement.

What Trump Actually Proposed

On July 6, 2026, Trump announced his administration is studying an Australia-style retirement system and said he’s “going to try very hard” to bring similar accounts to American workers, with plans to discuss the idea with Congress. Nothing has been formally proposed yet, and any real program would still need to clear Congress, but the concept centers on one specific idea: mandatory employer contributions to individual retirement accounts.

How Australia’s System Actually Works

Australia’s “superannuation” system, established in 1992, requires employers to contribute a set percentage of a worker’s ordinary earnings — currently 12% — into a retirement account that belongs entirely to the worker. Unlike Social Security, this isn’t a shared, pay-as-you-go pool; it’s money invested in the individual’s name, growing (or shrinking) with the market over their career. Workers can also add their own voluntary contributions on top, and professional fund managers handle the investing.

The system has earned real global credibility, receiving a B+ rating from the Mercer CFA Institute Global Pension Index, compared to a C+ rating for the current U.S. retirement system.

Why This Idea Is Gaining Attention Now

The timing isn’t random. America’s personal savings rate has fallen sharply, from 6.4% in early 2024 down to just 2.6% by April 2026, reflecting genuine financial pressure on households from persistently high costs. Meanwhile, Social Security’s own trustees have issued warnings about the program’s long-term funding, adding urgency to the conversation about supplemental retirement options.

Right now, U.S. employers can choose whether to offer a 401(k) at all, and even when they do, employee participation and employer matching are both optional. Australia’s model flips that entirely — participation isn’t a choice for the employer or the worker.

The Key Difference From Social Security

It’s important to understand this proposal wouldn’t replace Social Security — it would sit on top of it. Social Security currently replaces only about 40% of a typical worker’s pre-retirement income on average, and this kind of account is being discussed specifically as a supplement to close that gap, not a substitute.

The risk profile is genuinely different too. Social Security provides a guaranteed monthly benefit for life, adjusted annually for inflation (2026’s cost-of-living adjustment sits at 2.8%). A superannuation-style account, by contrast, would give a worker a pot of money they own outright, but its value would rise and fall with the market — meaning someone retiring during a market downturn could end up with meaningfully less than expected, a real risk that doesn’t exist with a guaranteed Social Security benefit.

Why Experts Are Skeptical This Happens Quickly

Financial experts have raised genuine concerns about whether the U.S. is actually ready for this shift. A mandatory 12% employer contribution is a significant new cost, and there’s real concern that businesses could respond by passing that cost on to workers through lower wages or reduced other compensation — meaning the “free” retirement savings might not be entirely free in practice.

There’s also a basic timing problem: if the U.S. started a superannuation-style program next year, accounts wouldn’t have enough time to build meaningful balances for workers already close to retirement, limiting the near-term benefit for anyone currently in their 50s or 60s.

What This Could Mean for You

Since this remains a floated concept without actual legislation, there’s nothing to act on directly yet. But it’s worth understanding where you’d stand if something like this eventually passes:

  1. If you’re younger, a mandatory employer contribution on top of your own savings could meaningfully accelerate how to build a retirement portfolio over a full career, similar to the compounding math we’ve walked through in our guide to building a portfolio from zero.
  2. If you’re older with minimal retirement savings, this specific proposal likely wouldn’t have enough time to meaningfully change your situation before retirement, making your own savings rate and Social Security timing more important than waiting on policy change.
  3. If you’re self-employed or between employers frequently, watch closely for how any actual legislation would handle enrollment portability, since Australia’s system assumes stable, ongoing employment relationships.

What You Should Actually Do Right Now

  1. Don’t wait on this proposal to start or increase your own retirement savings. With no legislation yet, this remains purely speculative, and your own consistent contributions matter regardless of what Congress eventually decides.
  2. If your employer offers a 401(k) match today, make sure you’re capturing the full match — that’s a guaranteed return you don’t need Congress to approve.
  3. Watch for concrete legislative proposals, since the difference between a floated idea and an actual bill with specific contribution rates and rules is significant.
  4. Understand this would supplement, not replace, Social Security if it ever passes, so continue treating your Social Security benefit as one piece of a larger retirement plan rather than your only plan.

Bottom Line

Trump’s interest in an Australia-style superannuation system reflects a real, well-documented gap: America’s personal savings rate has fallen sharply, and the current 401(k) system leaves both participation and employer contributions optional. Whether this specific proposal ever becomes law is genuinely uncertain, and even supporters acknowledge the U.S. may not be structurally ready for a mandatory system this significant. For now, the most useful takeaway isn’t waiting to see what Congress does — it’s recognizing that the underlying problem this idea is trying to solve (Americans under-saving for retirement) is real, and worth addressing in your own plan regardless of how the policy conversation unfolds.


This article is for informational purposes only and does not constitute financial or retirement planning advice. This proposal has not been enacted into law and details may change substantially; consult a licensed financial advisor for guidance specific to your retirement planning.

Iran Strikes Postponed 2026: Dow Jumps 600 Points as Trump Signals De-Escalation

0

Iran Strikes Postponed 2026: Dow Jumps 600 Points as Trump Signals De-Escalation

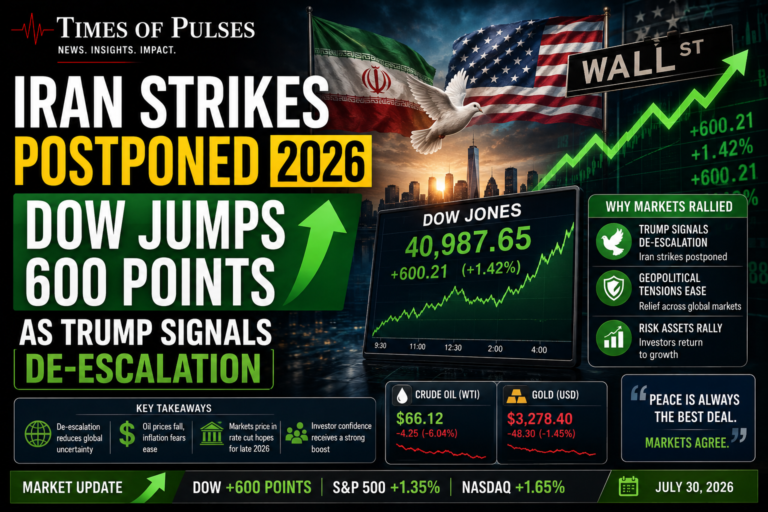
Markets just delivered one of their sharpest relief rallies of the year. The Iran strikes postponed 2026 decision — President Trump pulling back from threatened attacks on Iran’s power infrastructure — sent the Dow Jones Industrial Average surging over 600 points, while oil prices tumbled double digits in a single session. Here’s what actually happened, and why markets reacted so strongly to a pause rather than a resolution.

What Actually Happened

After a tense weekend that saw Trump issue an ultimatum — threatening to strike Iran’s power facilities if the Strait of Hormuz remained closed for 48 hours — the Iran strikes postponed 2026 story took a genuinely surprising turn. Trump announced early in the week that he had instructed the military to postpone strikes on Iran’s energy infrastructure, citing “very good and productive” talks between the U.S. and Tehran that were expected to continue.

This came despite Tehran having launched fresh attacks in the region just before the announcement — a reminder of how quickly this conflict has swung between escalation and de-escalation in recent weeks, following the earlier wave of U.S. strikes and Iranian retaliation we’ve covered extensively this month.

The Market Reaction Was Immediate and Dramatic

The Iran strikes postponed 2026 news triggered a sharp, broad-based rally:

  • The Dow Jones Industrial Average rose 1.4%, gaining over 600 points
  • The S&P 500 jumped roughly 1.2%
  • The Nasdaq Composite climbed about 1.4%

Oil prices told an even more dramatic story. West Texas Intermediate crude sank 10%, trading near $89 a barrel, while global benchmark Brent crude pulled back below $100 after briefly topping $113 in premarket trading — one of the sharpest single-day oil price reversals we’ve tracked throughout this entire conflict.

Why a “Postponement” Moved Markets So Much

This is worth understanding clearly: markets didn’t react to a peace deal or a resolved conflict — they reacted to reduced near-term escalation risk. The Iran strikes postponed 2026 decision specifically removed the immediate threat to Iran’s power and energy infrastructure, which had been the trigger for the weekend’s ultimatum. Trump reportedly told reporters that the Strait of Hormuz — the critical oil shipping corridor we’ve discussed at length this year — could reopen “very soon” if the ongoing talks continue to bear fruit.

Given how much of this year’s oil price volatility has centered specifically on Strait of Hormuz risk, any credible signal of that corridor reopening carries outsized weight for energy markets, which explains the double-digit single-day move in crude prices.

This Fits a Pattern We’ve Tracked All Year

If the market’s whiplash reaction feels familiar, it should. We’ve now covered multiple cycles of escalation and de-escalation in this conflict — oil spiking above $100 a barrel, then falling on peace deal hope, then rising again on renewed hostilities, and now this sharp reversal following the Iran strikes postponed 2026 announcement. Each cycle has triggered genuine, tradeable volatility across equities, oil, chip stocks, and even crypto markets, underscoring just how sensitive this specific conflict has become for portfolios far beyond direct energy exposure.

What This Means for Your Money

  1. Don’t treat this as a resolved conflict. A postponement tied to “productive talks” is meaningfully different from a peace agreement — the same de-escalation cycle has reversed multiple times already this year.
  2. Gas price relief may follow, but cautiously. If oil prices hold near these lower levels, pump prices could ease in the coming weeks — though as we’ve covered before, gas prices tend to lag crude oil moves in both directions.
  3. Expect continued volatility around Strait of Hormuz headlines. Given how directly tied oil prices have become to this specific chokepoint, any shift in the talks’ progress is likely to keep moving energy markets sharply.
  4. Resist chasing the rally in either direction. Markets have swung dramatically on Iran-related headlines multiple times this year alone — a single day’s relief rally doesn’t guarantee the trend holds.

Bottom Line

The Iran strikes postponed 2026 decision delivered a genuine, sharp relief rally across stocks and a dramatic pullback in oil prices, but it’s worth reading this correctly: markets rewarded reduced immediate risk, not a resolved conflict. Given how many times this specific situation has escalated and de-escalated throughout the year, the most useful response remains what we’ve suggested throughout this ongoing story — stay informed on the Strait of Hormuz talks specifically, and avoid making major financial decisions based on any single day’s dramatic swing.


This article is for informational and educational purposes only and does not constitute investment advice. Geopolitical developments are unpredictable and can reverse quickly; consult a licensed financial advisor before making investment decisions.

Stocks to Watch August 2026: 5 Companies Analysts Are Talking About Now

Stocks to Watch August 2026: 5 Companies Analysts Are Talking About Now

Following a genuinely turbulent July — marked by a chip stock selloff, a hawkish Fed surprise, and a historic Microsoft rally — stocks to watch August 2026 reflect a market still sorting out who’s really benefiting from the AI spending boom versus who’s just paying for it. Here’s a factual breakdown of what analysts are actually saying this month, so you can do your own research rather than chase a headline.

Why Stocks to Watch August 2026 Center on One Key Question

The Big Tech earnings that wrapped up in late July split Wall Street over a single question: is massive AI infrastructure spending translating into real revenue, or is it running ahead of actual demand? That divide is exactly why this month’s stocks to watch August 2026 fall into companies that answered that question convincingly, and ones still facing real investor skepticism.

Companies With Strong Analyst Support Right Now

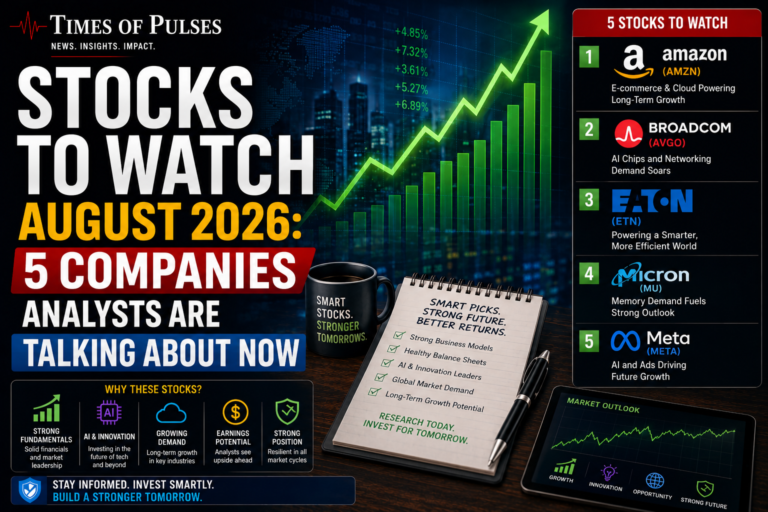
Amazon (AMZN) — Amazon carries some of the strongest analyst backing among stocks to watch August 2026, with all 28 covering firms rating it a Buy and none on Hold or Sell. The confidence stems from Amazon Web Services reaccelerating to 37% revenue growth, alongside a disclosed $496 billion backlog of signed customer demand. Analysts have specifically noted that unlike some competitors, Amazon’s spending increase came with proof that customers had already agreed to pay for it — which is why the stock rose on its results while others fell on similar spending news.

Broadcom (AVGO) — Highlighted as a growth-sector pick for the remainder of 2026, Broadcom sits in the technology sector benefiting from continued AI and infrastructure demand, with July’s broader selloff having reset valuations without changing the underlying growth story, according to recent sector analysis.

Eaton (ETN) — Representing the industrial products sector, Eaton has been flagged as a beneficiary of structural infrastructure demand tied to the broader AI buildout, an area analysts expect to keep growing through the second half of 2026.

Micron (MU) — Continuing its strong run from our July stocks to watch coverage, Micron posted a 785% EPS gain for its fiscal year ending August 31, following a 538% gain the prior year. Analysts note the stock, up over 630% in the past year, still hasn’t necessarily reached its ceiling, with some describing AI-driven memory demand as being in its “early innings.”

A Company Facing Real Analyst Skepticism

Meta Platforms (META) — Meta presents one of the more genuinely divided stories among stocks to watch August 2026. The company disclosed a new financing structure — a strategic venture with BlackRock for a 1-gigawatt data center — alongside quarterly capital expenditure of $31.1 billion against free cash flow of just $784 million, essentially zero. While Meta retains a Strong Buy rating from many analysts, at least ten have expressed genuine nervousness about the financing structure, and money-flow chart patterns suggest the same volatility seen in Meta’s stock earlier this year could repeat if buyer confidence doesn’t clearly return.

What This Divide Actually Reveals

The contrast between Amazon and Meta this earnings season is a genuinely useful real-world lesson: two companies both increased AI infrastructure spending, but the market rewarded one and punished the other based on a specific detail — whether that spending came with visible proof of future revenue (Amazon’s backlog) or relied on more complex financing arrangements without the same demand confirmation (Meta’s data center venture). This is exactly the kind of distinction we’ve emphasized throughout our coverage of AI stock volatility this year: headline spending numbers matter less than what’s actually backing them up.

The Broader Market Backdrop for August

A few macro factors are shaping how analysts approach stocks to watch August 2026:

  • The Federal Reserve left rates unchanged at 3.50%-3.75% in July, while noting inflation remains above its long-run target — a genuinely different tone than the rate-cut expectations that dominated earlier in the year
  • The S&P 500 gained nearly 8% in the first half of 2026, with companies broadly continuing to beat consensus earnings estimates
  • Valuations across several growth sectors reset during July’s selloff without any material change to long-term fundamentals, according to multiple analysts — which some read as a genuine opportunity rather than a warning sign

How to Actually Use This List

The same honest caveats apply as always:

  1. This reflects what analysts are discussing, not a personal recommendation. Even professional coverage can shift quickly as new data emerges.
  2. Match any decision to your own risk tolerance and timeline. A stock suited for a long-term retirement portfolio may not fit a shorter-term goal.
  3. Watch for concentration risk, especially across AI-infrastructure-linked names that may move together if sentiment shifts broadly, as we saw during July’s chip stock selloff.
  4. Read the actual earnings commentary, not just the headline analyst rating, before making any decision.

What You Should Actually Do This Week

  1. Compare Amazon’s backlog-backed spending against Meta’s financing-based approach if you’re researching either name — the distinction genuinely matters for risk assessment
  2. Check whether your existing portfolio already holds exposure to these names through broad index funds before considering individual positions
  3. Watch Micron’s upcoming fiscal year-end results (ending August 31) for confirmation of whether its exceptional EPS growth trend continues
  4. Don’t treat this list as a substitute for your own research or a financial advisor’s guidance

Bottom Line

Stocks to watch August 2026 reveal a market that’s become genuinely more discerning after July’s volatility — rewarding companies like Amazon that can show concrete demand behind their AI spending, while staying nervous about financing structures like Meta’s that ask investors to trust rather than verify. For your own research, the useful takeaway isn’t picking a side in the AI spending debate, but understanding which specific evidence separates the companies analysts trust from the ones they’re still watching carefully.


This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Stock market movements are unpredictable, and analyst opinions can change quickly; consult a licensed financial advisor before making investment decisions.

Recession 2026 Warning Signs: 7 Red Flags Economists Are Watching Right Now

0

Recession 2026 Warning Signs: 7 Red Flags Economists Are Watching Right Now

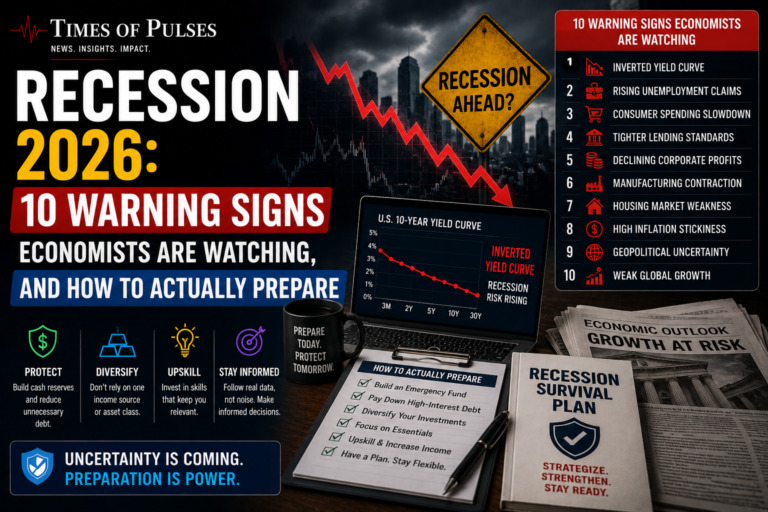
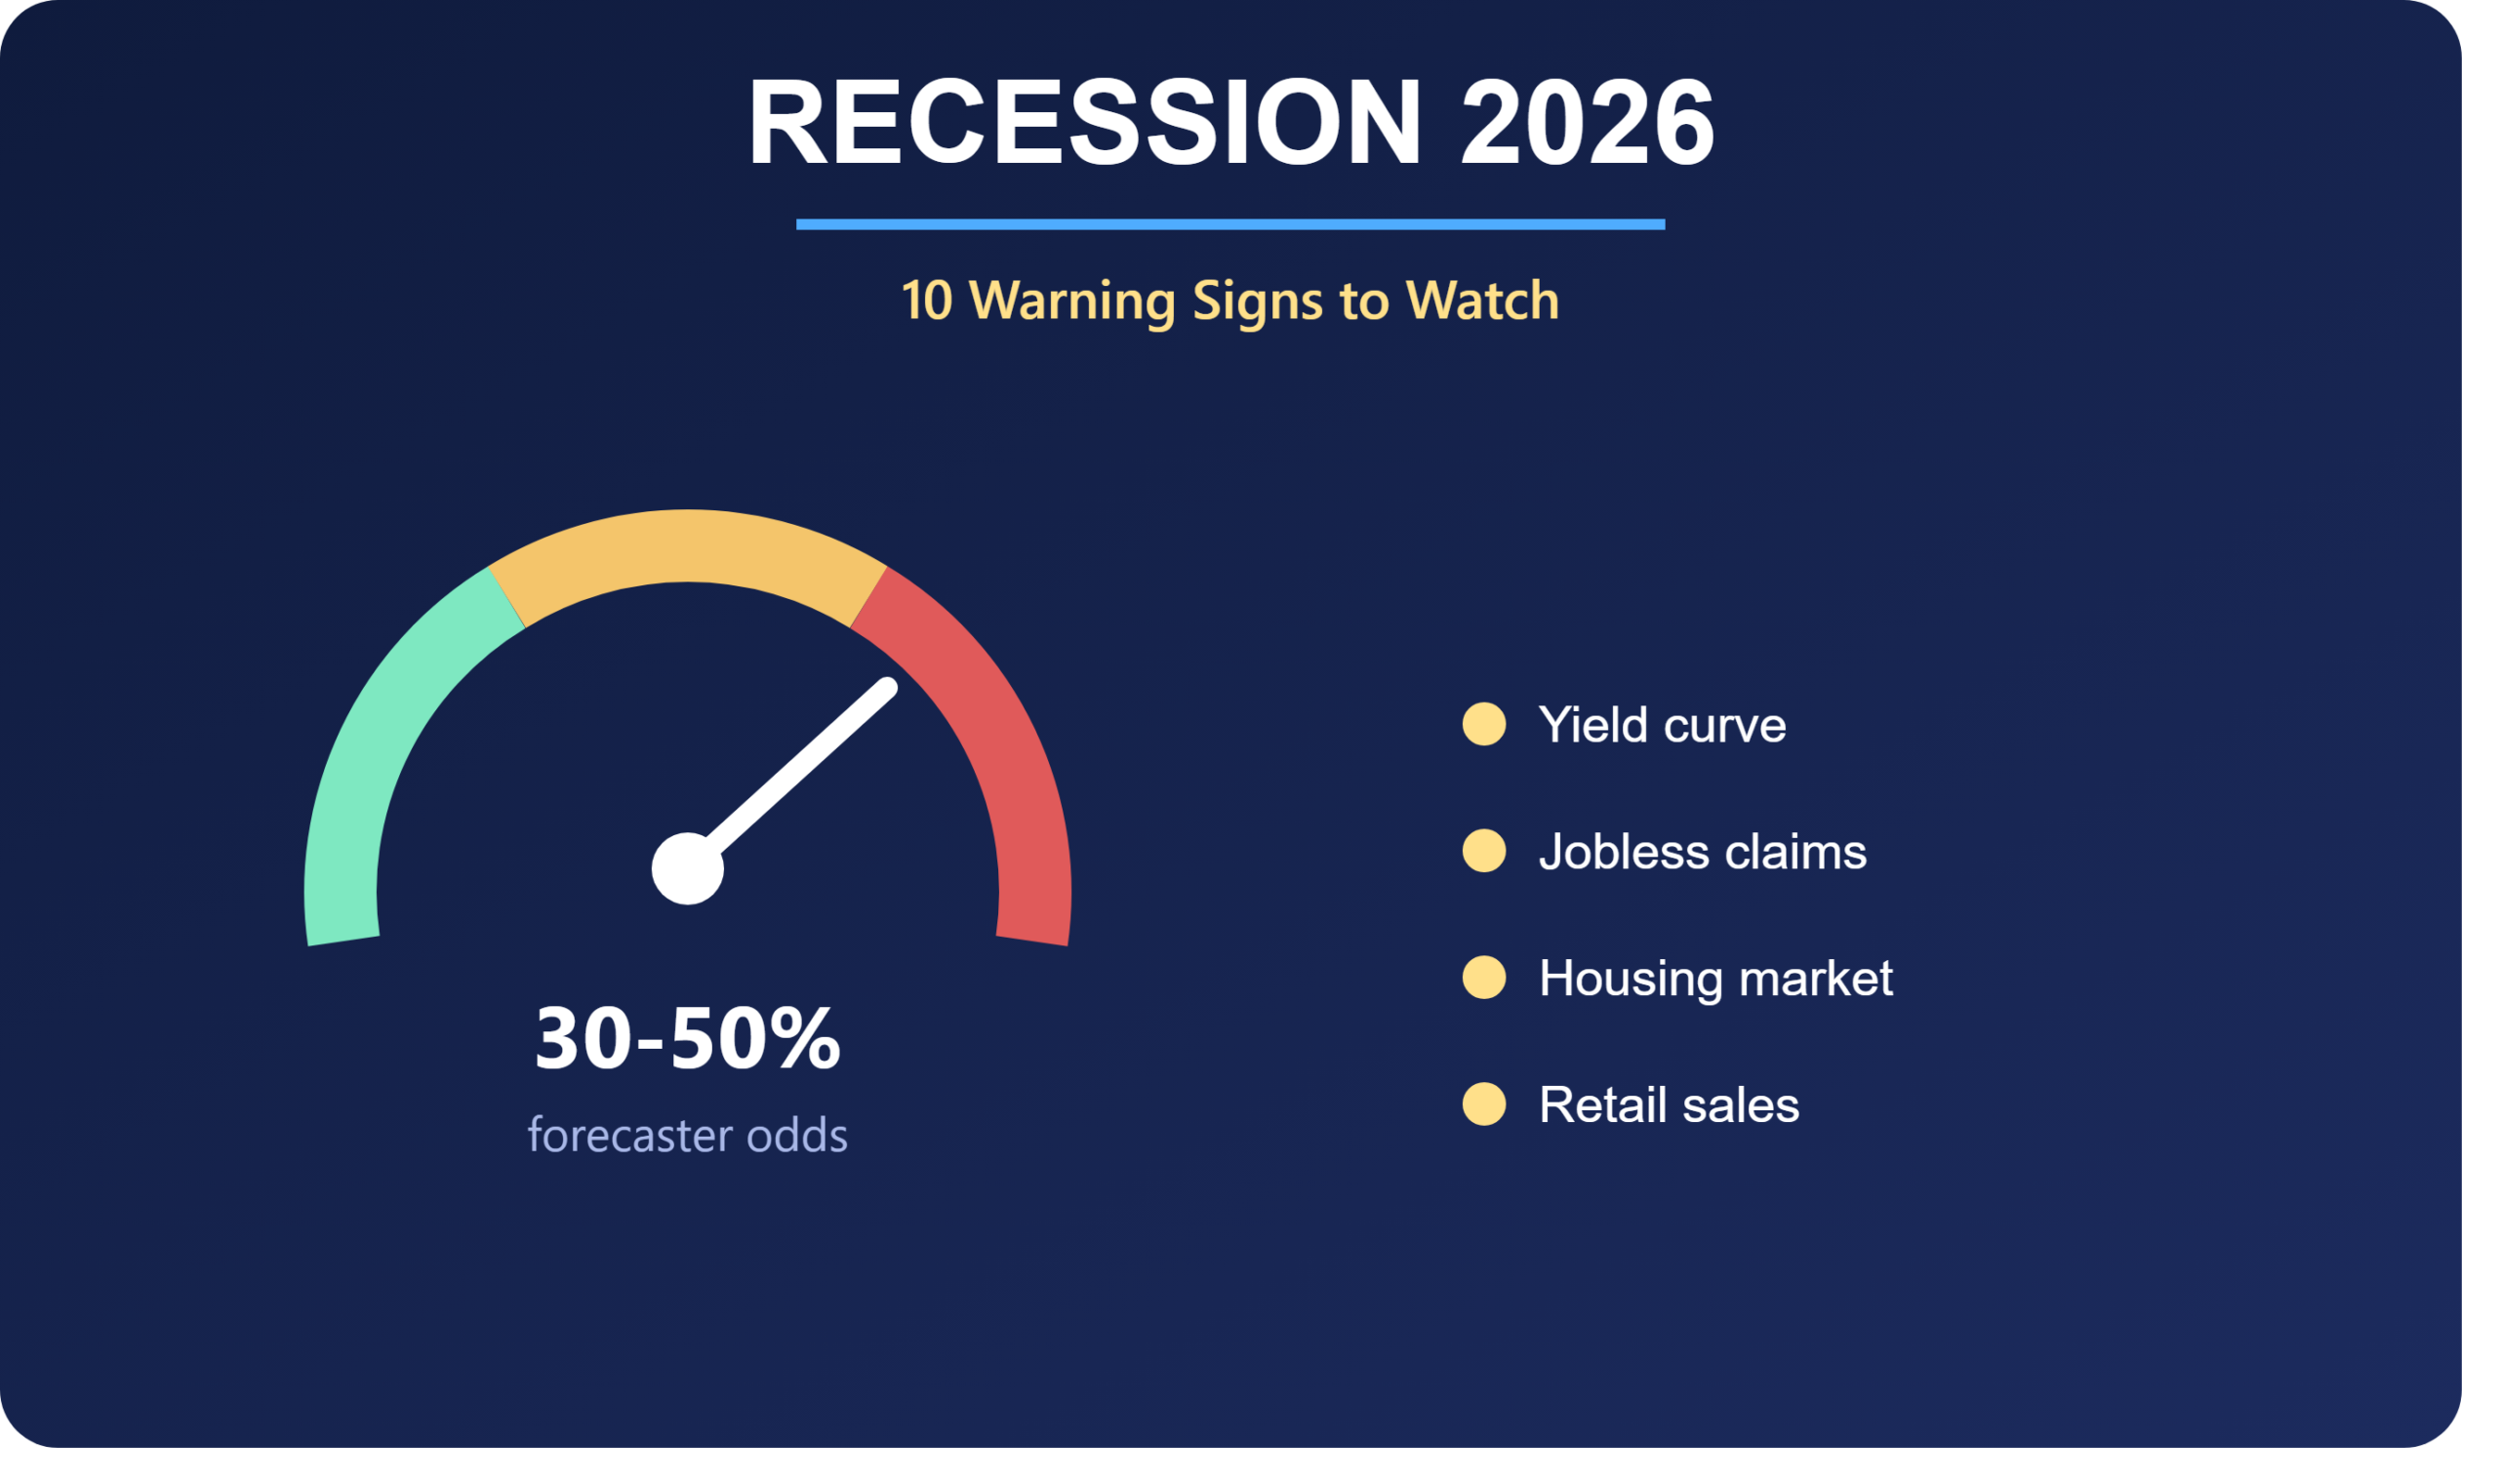
Recession 2026 has gone from a fringe worry to a genuine, widely-discussed possibility among major financial institutions. JPMorgan, Goldman Sachs, Moody’s, and the IMF now put recession odds somewhere between 30% and 50% — not a certainty, but no longer a tail risk you can safely ignore either. If you’ve felt like the economy sends mixed signals depending on who you ask, that’s because it genuinely does right now. Here’s a clear walk through the actual indicators economists track, where each one currently stands, and a realistic plan for preparing your finances regardless of which way this goes.

Why Recession 2026 Predictions Vary So Widely

recession 2026

Before diving into the indicators, it’s worth understanding why estimates range so much. Recession 2026 probability estimates differ because forecasters weigh different data differently — some lean heavily on market valuations, others on labor market softness, others on consumer spending trends. According to recent economic analysis, Wall Street and “Main Street” also seem to be experiencing genuinely different economies right now: stock markets have hit fresh highs and corporate profits remain healthy in many sectors, while ordinary households navigating grocery aisles and gas stations report elevated prices and real financial strain. Both realities are true simultaneously, which is part of why the recession 2026 conversation feels so contradictory.

The 10 Real Indicators Economists Actually Track

1. The Yield Curve (and Its “Un-Inversion”)

Seven of the last seven U.S. recessions were preceded by an inverted yield curve, where short-term Treasury yields exceed long-term yields. The curve inverted back in 2022 and stayed inverted into 2024. Notably, it’s the “un-inversion” — when the curve steepens back to normal — that has historically preceded the actual onset of recession 2026-style downturns by three to six months, making this both a warning signal and a timing indicator worth watching closely right now.

2. Initial Unemployment Claims

This is one of the most timely labor market signals available, reported weekly with minimal revision. A sustained rise above 250,000-300,000 claims per week has preceded past recessions. As of recent data, claims sit in the 210,000-230,000 range — still in healthy territory, though this is exactly the kind of number worth checking regularly given how quickly it can shift.

3. ISM Manufacturing and Services PMI

These purchasing manager surveys measure new orders, production, and employment across the economy. A reading below 50 signals contraction, and readings below 45 for three or more consecutive months have preceded every recession since 1970. The manufacturing PMI has spent extended periods below 50 recently, though the larger services sector has mostly stayed in expansion — a genuine split that mirrors the broader mixed-signal economy.

4. Consumer Confidence

Sharp drops of 20 or more points over three months have historically preceded downturns, since consumers who feel pessimistic cut spending, which itself can help trigger the recession 2026 forecasters are worried about — a self-reinforcing cycle worth watching.

5. Rising Unemployment Rate Trend

A recession signal specifically triggers when the three-month moving average of unemployment rises 0.5 percentage points above its 12-month low — a more nuanced read than just watching the headline unemployment number alone.

6. Housing Market Weakness

Housing represents roughly 15% of GDP, and steep drops of 30% or more in housing activity often precede or coincide with recessions. As we’ve covered in our reporting on 2026 housing costs, affordability has already declined for months running — a sector economists are watching closely.

7. Corporate Earnings and Profit Margins

Two consecutive quarters of declining margins often signal broader economic weakness. Right now, this presents another split picture: AI-driven tech stocks have kept valuations elevated, but a broad swath of the economy — retail, manufacturing, small business — is reporting shrinking margins beneath the surface.

8. Credit Spreads

Widening spreads between corporate bonds and Treasury yields, particularly above 5%, signal stress in credit markets — a pattern that showed up before both the 2008 and 2020 downturns.

9. Declining Real Retail Sales

Three consecutive months of declining inflation-adjusted retail sales is considered a genuine warning sign, since it reflects actual household purchasing power shrinking, not just nominal spending shifts.

10. Labor Market “Pre-Signals”

Beyond the unemployment rate itself, economists watch job openings (down significantly from their 2022 peak), temporary employment (which tends to fall before permanent layoffs begin), hiring freezes spreading across tech, finance, and professional services, and average hours worked per week trending down — since companies typically cut hours before they cut headcount. The problem: the labor market is a lagging indicator, meaning by the time jobs data turns clearly negative, a recession has often already started.

Two Extra Warning Signs Specific to Recession 2026

Beyond the classic 10 indicators, two factors are uniquely elevated in the current recession 2026 conversation:

Stretched valuations. The Buffett Indicator, which measures total U.S. stock market value against GDP, currently sits around 213% — above even the 193% peak seen in 2021. Warren Buffett himself once said readings approaching 200% mean investors are “playing with fire.”

Geopolitical and energy risk. As we’ve tracked extensively this year, oil prices have swung dramatically amid Iran-related tensions, at one point topping $108 a barrel. Countries with heavy oil import dependence — Japan, South Korea, and Taiwan — have seen some of the sharpest equity declines tied to this risk, compounding the volatility we’ve also seen in chip stocks this year.

Why the 2026 vs. 2027 Debate Matters

Interestingly, some Wall Street analysis suggests recession risk may actually be higher for 2027 than for 2026 itself. Strong corporate earnings, resilient hiring, and hopes for diplomatic resolution on the Iran conflict have helped calm the sharpest fears for this year specifically. But rising debt costs — as companies that refinanced pandemic-era debt at 1-2% now face renewal at 5-6% — combined with elevated living expenses and the ongoing threat of an oil shock, could mean the pressures building now take longer to fully surface.

How to Actually Prepare Your Finances (Regardless of Timing)

The honest truth about recession 2026 forecasting: you don’t need to predict the exact year a downturn arrives. You just need to prepare for the possibility, using steps that make sense whether or not a recession actually materializes:

  1. Build or top up your emergency fund. As we’ve discussed in our guide to the best high-yield savings accounts, keeping 3-6 months of expenses in an accessible, interest-earning account gives you a genuine buffer if hiring slows or hours get cut.
  2. Pay down high-interest debt now, while you have income stability. Credit card debt becomes significantly harder to manage if your income drops unexpectedly — our guide on how to pay off credit card debt fast walks through the specific strategies that work fastest.
  3. Don’t panic-sell your investments based on recession headlines. Market timing is notoriously difficult even for professionals, and the same volatility we’ve tracked all year — from the chip stock selloff to Microsoft’s record rebound just days later — shows how quickly sentiment can reverse in either direction.
  4. Focus on quality over speculation in your portfolio. Companies with durable cash flow and real earnings tend to weather downturns better than speculative, story-driven stocks.
  5. Keep your job skills and network active, given that hiring freezes and reduced hours often show up before headline layoffs do.
  6. Watch your own personal “recession indicators.” Are your hours being cut? Is overtime disappearing? Are raises smaller than usual, something we’ve covered in our reporting on paychecks under pressure this year? Your own household data often tells you more than any national statistic.

What You Should Actually Do This Week

  1. Check your emergency fund against 3-6 months of actual expenses, not just a round number that feels comfortable
  2. List your highest-interest debts and prioritize paying them down while your income is stable
  3. Resist the urge to make dramatic portfolio changes based on recession headlines alone — read the underlying indicators, not just the probability percentage
  4. Track your own household’s early warning signs — reduced hours, hiring freezes at your employer, or smaller-than-expected raises — since these often arrive before official recession data confirms anything

Bottom Line

Recession 2026 sits in a genuinely uncertain zone — a 30-50% probability range according to major forecasters isn’t a prediction of doom, but it’s far too significant to ignore. The most useful approach isn’t trying to perfectly time when or whether a downturn arrives; it’s building the same financial resilience — an emergency fund, manageable debt, and a diversified, quality-focused portfolio — that serves you well whether the economy avoids a recession entirely or heads into one sooner than expected. Historically, some of the best buying opportunities have appeared long before headlines finally admit trouble has arrived, which is exactly why preparation beats prediction.


This article is for informational and educational purposes only and does not constitute financial or investment advice. Economic forecasts are inherently uncertain and vary significantly across institutions; consult a licensed financial advisor for guidance specific to your situation.