Home Blog Page 4

Ray Dalio Debt Crisis Warning: Why He’s Telling Investors to Dump Bonds for Gold and Bitcoin

Ray Dalio Debt Crisis Warning: Why He’s Telling Investors to Dump Bonds for Gold and Bitcoin

Billionaire investor Ray Dalio just made one of his boldest public calls in years, and it’s rattling more than just crypto Twitter. The Bridgewater Associates founder says the U.S. government’s finances have hit an “inflection point,” and his solution is blunt: get underweight bonds, and put real money into gold and bitcoin instead. Here’s exactly what the Ray Dalio debt crisis warning says, the numbers behind it, and what it might mean for your own portfolio.

What the Ray Dalio Debt Crisis Warning Actually Says

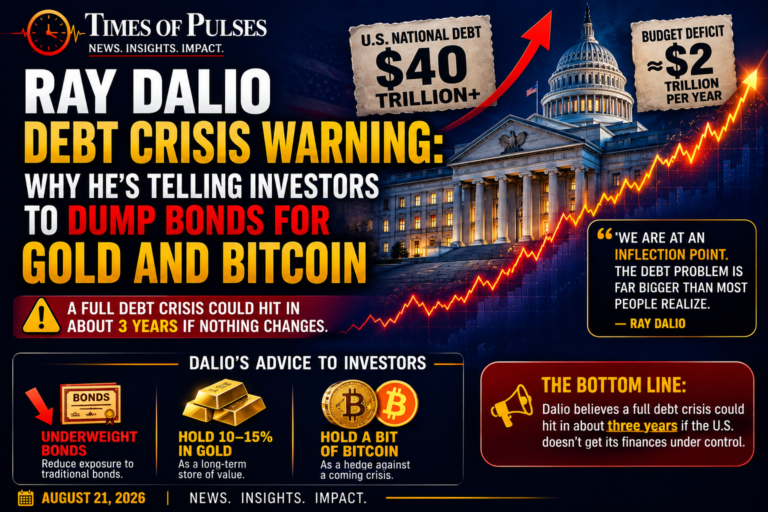
In a LinkedIn post published Friday, August 21, Dalio said investors should reduce their bond holdings and consider allocating 10% to 15% of their portfolio to gold, plus “a bit” of bitcoin. He didn’t offer a precise bitcoin target, but the direction of his advice was unmistakable. “I am confident that the government’s financial condition is at an inflection point,” Dalio wrote. “If this is not dealt with now, the debts will build up to levels where they can’t be managed without great trauma.”

This isn’t a new theme for Dalio, who has written extensively about sovereign debt cycles in his book How Countries Go Broke: The Big Cycle. What makes this specific Ray Dalio debt crisis warning notable is the timing and the trigger behind it.

The Trigger: Treasury Secretary Bessent’s Bond Buyback Move

Dalio’s warning was sparked by a specific event: Treasury Secretary Scott Bessent’s announcement that his team would sharply increase buybacks of long-dated government bonds, raising the maximum size of certain operations to at least $4 billion, double the previous $2 billion cap. According to CNBC’s report on Dalio’s comments, Bessent told the network his team was going to “make a market” and that the purchases would likely top $4 billion.

Dalio reads it differently. In his view, governments buy back their own debt when investor demand is thinning out, and he noted the Treasury has “only limited capacity” to keep doing it. Combined with Japan, historically America’s largest foreign creditor, selling U.S. bonds to support its own currency, Dalio sees a pattern he’s flagged before in countries approaching serious debt trouble.

The Numbers Fueling the Ray Dalio Debt Crisis Warning

The fiscal picture Dalio is pointing to is genuinely stark:

  • U.S. government debt crossed $40 trillion the same week
  • The U.S. is spending roughly 40% more than it collects, with expected revenue near $5.5 trillion against expenses near $7.5 trillion
  • July’s budget deficit alone topped $432 billion
  • If the federal government were a business, Dalio estimates debt-servicing payments would total around $11 trillion, roughly 200% of annual revenue
  • The 30-year Treasury yield touched its highest level since 2007, climbing above 5.3%

Dalio’s own estimate is that a full-blown debt crisis could hit “in three years, give or take two,” landing somewhere between one and five years if nothing changes on the current path.

Why Bonds Are the Problem in Dalio’s View

Rising long-term Treasury yields might sound like good news for savers, but for the government, higher yields mean it costs more to keep borrowing at the scale it currently needs. The Ray Dalio debt crisis warning centers on exactly this trap: as investors demand higher returns to keep lending to a government running large, persistent deficits, borrowing costs rise, which worsens the deficit further, which then requires even more borrowing.

He’s not alone in flagging the strain. Other major economies including the U.K., China, and Japan face similar pressures, according to Dalio, which is part of why he expects “non-government-produced monies like gold and bitcoin to do relatively well” if multiple currencies face devaluation pressure at once.

The Market Reaction Confirms the Ray Dalio Debt Crisis Warning Is Landing

Markets moved almost immediately. Bitcoin climbed from around $63,500 to above $78,000 within days, its strongest weekly performance since 2023, while gold jumped to its highest level since May. That combined rally, sometimes called the “debasement trade,” reflects investors positioning for a weaker dollar and more currency-related risk rather than reacting to any single company or sector.

Notably, Dalio was once one of crypto’s most prominent skeptics. His current stance, recommending “a bit” of bitcoin alongside a much larger gold allocation, is a meaningful shift from his 2022 recommendation of just 1% to 2% in bitcoin.

Dalio’s Proposed Fix (Not Just a Warning)

Dalio didn’t only warn, he also laid out what he thinks would actually solve the problem: cutting the budget deficit from around 6% of GDP down to 3%, through a combination of spending cuts, higher tax revenue, and lower interest rates, all done together rather than in isolation. He pointed to America’s own history as a template, noting the deficit was 4.6% of GDP in 1991 and had swung to a surplus by 1998 through exactly that kind of combined approach.

He also cautioned against a shortcut: forcing interest rates artificially lower through the Federal Reserve, which he said would be “very bad” and risks fueling the same currency debasement he’s warning investors to hedge against.

What This Means for Your Own Money

  1. Don’t treat this as investment advice to copy exactly. Dalio’s 10-15% gold allocation is a specific strategy for his own risk framework, not a universal rule for every portfolio size or age.
  2. Understand what you’re actually hedging against. Gold and bitcoin are being framed here as protection against currency devaluation and rising government borrowing costs, not as short-term trading plays. If you haven’t done a full portfolio and savings audit recently, a debt-crisis headline like this is exactly the kind of moment that makes it worth revisiting where your money actually sits.
  3. Watch the 30-year Treasury yield, not just headlines about the debt. As we covered when the 30-year yield hit a 19-year high, this number feeds directly into mortgage and loan costs well before any “crisis” label applies.
  4. A three-year, give-or-take-two forecast is still just a forecast. Dalio himself has acknowledged making similar warnings for years that appeared premature at the time.

Bottom Line

The Ray Dalio debt crisis warning isn’t a prediction of collapse next month, it’s a structural argument about where U.S. government finances are headed if the current path of $2 trillion annual deficits and $40 trillion in total debt continues unaddressed. Whether or not you agree with his specific gold-and-bitcoin allocation, the underlying numbers behind the warning, record debt, rising long-term yields, and a widening deficit, are real and worth understanding regardless of which assets you personally hold.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making changes to your investment portfolio.
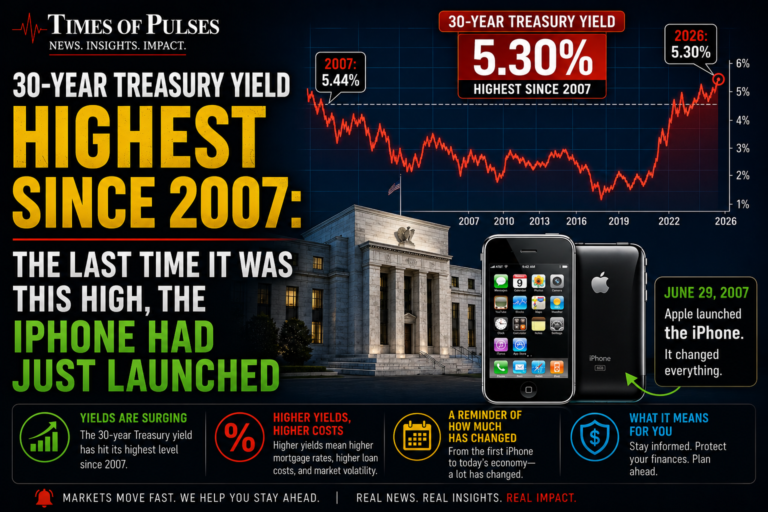
30-Year Treasury Yield Highest Since 2007: The Last Time It Was This High, the iPhone Had Just Launched

30-Year Treasury Yield Highest Since 2007: The Last Time It Was This High, the iPhone Had Just Launched

The 30-year Treasury yield highest since 2007 milestone just hit, and the comparison analysts keep reaching for says everything: the last time long-term borrowing costs sat at this level, the first iPhone had just gone on sale and the word “subprime” was only beginning to enter everyday conversation. The benchmark long bond touched roughly 5.3% this week, a level unseen since the summer of 2007 — and unlike a lot of financial headlines, this one has a direct line to your mortgage, your car payment, and your credit card bill.

What Actually Happened

The yield on the 30-year U.S. Treasury bond climbed above 5.3% this week, its highest level since April 2007, when yields touched 5.44%. For most of the decade following the 2008 financial crisis, this same yield sat comfortably below 3% — meaning the jump to 5.3% isn’t a minor wiggle, it’s what one deVere Group executive called a warning “about the true cost of government borrowing,” not just a footnote to whatever the stock market is doing that day.

The move has been building for months. After dipping slightly early in the year, the 30-year yield has climbed steadily since late February, pushed higher by a combination of persistent inflation, mounting concerns over the federal deficit, and an unusually large wave of new government bond issuance competing for investor demand.

Why 30-Year Treasury Yield Highest Since 2007 Matters to You Directly

Treasury yields act as a benchmark that ripples through nearly every other borrowing rate in the economy. Here’s what’s already moving because of it:

  • Mortgage rates: the average 30-year fixed mortgage has been hovering around 6.65-6.67%, and Zillow’s senior economist noted this week that even though the Treasury stepped in to calm bond markets, the underlying forces pushing rates up — the deficit, the oil shock, and AI-related corporate debt — “haven’t faded and will likely put a floor under how far mortgage rates can fall.”
  • Auto loans: buyers financing a new vehicle are currently facing APRs around 7%, while used-car buyers are contending with rates closer to 10.6%.
  • Credit cards: variable-rate cards, which track closely with the prime rate, face similar upward pressure as the broader rate environment stays elevated.
  • Home equity borrowing: anyone considering a HELOC or home equity loan is facing the same higher-for-longer backdrop.

The Part That Should Actually Concern You

A Bank of America survey of global hedge fund managers found 62% believe 30-year yields could climb all the way to 6%, potentially approaching their 2007 peak, with 40% of managers still anticipating further inflation surges. That’s a meaningful signal — professional money managers aren’t betting on quick relief.

The U.S. Treasury did respond this week by doubling the size of its long-term bond buyback program specifically to support prices and pull yields back down, and yields did fall sharply in immediate response — before climbing right back up the very next day. That whiplash is worth sitting with: even a direct government intervention only bought a brief pause, not a reversal.

What This Means for Your Mortgage or Car Purchase

If you’re house-hunting or shopping for a car right now, the 30-year Treasury yield highest since 2007 headline isn’t background noise — it’s the mechanism setting the rate you’ll actually be quoted. Mortgage rates have already climbed from 6.66% in late July on the back of this same pressure. As we covered in our breakdown of why the Fed can’t agree on rates, policymakers themselves are genuinely split on the path forward, which adds another layer of uncertainty on top of what the bond market is already pricing in.

Practical takeaway: if you’ve been waiting for mortgage or auto loan rates to drop meaningfully before making a purchase, this week’s data doesn’t offer much encouragement for a quick reversal. A modest, temporary dip (like the one triggered by the Treasury’s buyback announcement) is not the same as a sustained trend down.

What You Should Actually Do Right Now

  1. Don’t assume today’s mortgage quote is temporary. With 62% of surveyed fund managers expecting yields to climb further, not fall, locking in a rate you can genuinely afford now may be more useful than waiting for a drop that isn’t clearly coming.
  2. If you’re carrying variable-rate credit card debt, treat this as added urgency to pay it down — rates tracking the prime rate aren’t likely to ease alongside these Treasury moves.
  3. Reconsider stretching an auto loan term to lower the monthly payment. With APRs already elevated, a longer loan term compounds the total interest paid even more than usual right now.
  4. If a large purchase can wait, build your emergency fund in the meantime rather than rushing into a loan at today’s elevated rates purely out of fear they’ll rise further — a stronger financial cushion gives you more flexibility either way.

Bottom Line

30-year Treasury yield highest since 2007 is one of those headlines that sounds abstract until you connect the dots: it’s the reason mortgage rates haven’t meaningfully dropped, why auto loans feel more expensive than they used to, and why credit card debt is getting harder to shake. The government’s own attempt to calm the bond market only bought a day of relief before yields climbed back. Until the deficit concerns, inflation pressure, and heavy bond issuance driving this move genuinely ease, the smartest response is the practical one: don’t bank on rates dropping soon, and make borrowing decisions based on what you can afford today, not what you’re hoping will be available next year.


This article is for informational and educational purposes only and does not constitute financial or investment advice. Bond markets and interest rates are unpredictable and can change rapidly; consult a licensed financial advisor for guidance specific to your situation.

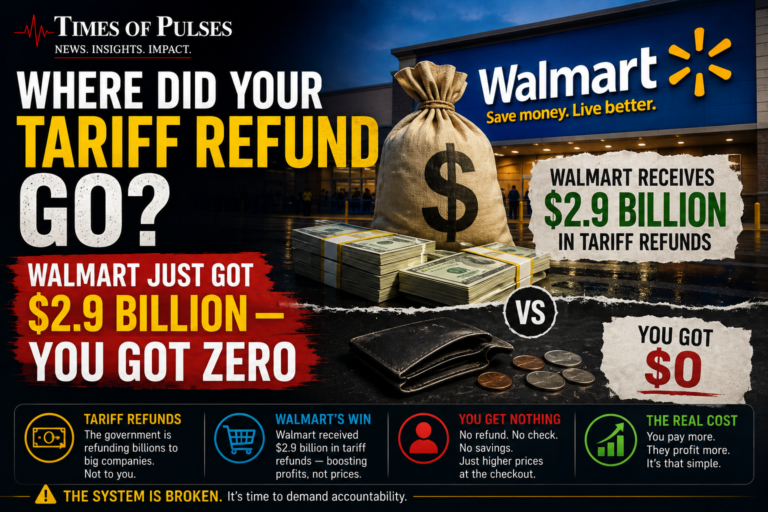
Where Did Your Tariff Refunds Go? Walmart Just Got $2.9 Billion — You Got Zero

Where Did Your Tariff Refund Go? Walmart Just Got $2.9 Billion — You Got Zero

Remember paying more at the register over the past year because of tariffs? The companies that collected that money are now getting massive tariff refunds — Walmart alone just received $2.9 billion, the largest single tariff refund reported yet. If you’re wondering when your share is coming, the honest answer is uncomfortable: for most people, it isn’t. Here’s what’s actually happening with tariff refunds, and why the money is flowing one direction only.

The Scale of the Tariff Refunds Going Out Right Now

Following the Supreme Court’s February 2026 ruling that struck down the Trump administration’s sweeping IEEPA tariffs as illegal, the government has been processing refunds on the roughly $166 billion collected from over 330,000 importers. As of late July, approximately $100 billion had already been sent out, according to a Customs and Border Protection court filing.

The individual numbers are striking:

  • Walmart: $2.9 billion — the largest refund reported to date
  • Target: $994 million, which helped push net earnings to nearly $1.9 billion for the quarter
  • Apple: an estimated $2.2 billion
  • Amazon: approximately $640 million
  • Ford: $1.3 billion
  • General Motors: $500 million
  • Home Depot: $730 million, with Lowe’s receiving $80 million
  • TJX (parent of TJ Maxx, Marshalls, HomeGoods): $331 million
  • Nike: approximately $300 million
  • Stellantis (Jeep, Ram): roughly $467 million

These aren’t hypothetical figures — they’re showing up directly in corporate earnings reports this quarter, meaningfully boosting profits at exactly the companies that passed tariff costs onto shoppers in the first place.

Why Tariff Refunds Are Going to Companies, Not You

This is the core issue worth understanding clearly: tariffs are technically paid by the importer of record — the company bringing goods into the country — not directly by the end consumer. Even though the cost of those tariffs was largely passed through to shoppers via higher prices, the legal refund only goes back to whoever originally paid it at the border. As one CNN Business analysis put it, “in many cases, it’s nearly impossible to figure out how much of a company’s tariff refund came out of consumers’ pockets.”

Making this even messier, companies layered multiple rounds of tariffs on top of each other throughout 2025 and 2026 — some struck down by the Supreme Court, others still legally in effect. Even when a company raised prices, tracing exactly which tariff caused which price increase, and whether a given refund corresponds to money you personally paid, is genuinely close to impossible from the outside.

What Companies Are Actually Doing With Their Tariff Refund Money

Corporate responses to the refund windfall vary, and most aren’t putting cash directly back in your pocket:

Target has been explicit: CFO Jim Lee confirmed the company will not issue direct refunds to customers, instead using the money toward “bringing lower prices” across the store — including reductions on more than 10,000 items over the past year, according to the company.

Walmart and Costco have made similar commitments to use refund money to support pricing rather than issue direct payouts, with Costco CEO Ron Vachris saying the company would return value “in some form,” though specifics remain vague.

Amazon stands out as a genuine exception. The company said it has “identified a limited set of circumstances where we can trace that we passed specific import charges on to customers,” and committed to proactively refunding those specific customers directly — a narrower, more targeted approach than most retailers are taking.

Many companies have said little at all about how refund money will flow through to shoppers, simply reporting the earnings boost without committing to any pricing or refund action.

The Political Fight Brewing Over Tariff Refunds

This gap between corporate refunds and consumer relief has become a genuine midterm election issue. Senate Democrats introduced the Tariff Refund Act of 2026, which would require full refunds with interest directly to affected parties within 180 days, prioritizing small businesses. To date, that legislation hasn’t advanced, and experts caution Americans are “unlikely to see any cash” through this specific path, given the complexity of tracing individual harm.

Trump himself has floated the idea of a tariff “dividend” check funded by tariff revenue at various points, but there’s been no formal follow-through on that proposal.

What the Tariff Refund Gap Means for You Right Now

  1. Don’t expect a direct tariff refund check. Unless you specifically shopped through a retailer using a customs-broker shipping service (like some overseas purchases through FedEx or UPS, which have started passing along tariff refunds in narrow cases), a direct payment to you personally is unlikely.
  2. Watch for gradual price adjustments instead. If tariff refund money is genuinely funding “lower prices” as several major retailers claim, the more realistic benefit shows up as smaller price increases or modest cuts over time, not a lump-sum payment.
  3. Don’t assume tariff costs are fully gone. As we’ve covered in our reporting on the August 1 tariffs, the administration has already replaced the struck-down IEEPA tariffs with new ones under different legal authority (Sections 122 and 301), meaning the underlying cost pressure on many goods hasn’t actually disappeared.
  4. If you made a specific overseas purchase and used a shipping/customs broker, check your account. This is genuinely the one pathway where individual consumers have started seeing direct refund credits.

Bottom Line

The tariff refund story reveals an uncomfortable but predictable pattern: money moves easily between governments and large corporations with the legal standing and infrastructure to claim it, while the households who actually absorbed higher prices at checkout have no clear mechanism to get their share back. With companies like Walmart, Target, and Apple collectively pocketing billions in refunds this quarter, and most committing that money to future pricing strategy rather than direct consumer payouts, the most realistic outcome for most people is gradual, hard-to-trace relief at the register rather than any kind of refund check. Given how tangled the broader tariff picture remains heading into the rest of 2026, the smartest move is watching your actual receipts over time rather than waiting for a payment that, for most households, likely isn’t coming.


This article is for informational purposes only and does not constitute financial or legal advice. Tariff refund policy continues to evolve and is subject to ongoing litigation; consult official government sources for guidance specific to your situation.

Trump Pauses Canada Tariffs Two Hours Before Deadline — Here’s the Last-Minute Deal That Just Saved $20 Billion in Trade

Trump Pauses Canada Tariffs Two Hours Before Deadline — Here’s the Last-Minute Deal That Just Saved $20 Billion in Trade

Trump pauses Canada tariffs. Five words that dropped late Tuesday night and instantly changed the outlook for one of America’s biggest trading relationships. With 50% tariffs on roughly $20 billion worth of Canadian goods set to take effect at midnight, President Trump announced a three-day delay less than two hours before the deadline hit — citing a tentative deal that, in his words, both sides are still “finalizing.” If you’ve been following our earlier coverage of the August 1 tariffs and what they meant for your wallet, this is the next chapter in that same story, and it’s arguably even more dramatic.

How Close This Actually Came to Taking Effect

This wasn’t a routine policy delay announced weeks in advance. Trump posted the news on Truth Social late Tuesday night, writing that he had paused the 50% tariffs “based on the fact that Canada and the U.S.A., subject to the finalization of documents, have a DEAL!” The tariffs, announced back on July 20 under Section 338, were scheduled to hit a wide range of Canadian goods — agriculture, dairy, furniture, and alcoholic beverages — starting August 19.

Negotiators reached the agreement less than two hours before the tariffs were due to take effect, an unusually tight window even by the standards of a trade relationship that’s been tense for months. Canadian Prime Minister Mark Carney confirmed the tariffs had been postponed until the end of day, August 21, giving both sides a short but critical window to finalize the actual paperwork.

Why Trump Pauses Canada Tariffs Is Bigger News Than It Sounds

Trump pauses Canada tariffs might read like a simple headline, but the details underneath it reveal a genuinely significant shift. Canada was one of only two countries — alongside China — that chose to retaliate against Trump’s earlier tariffs rather than negotiate quietly, which makes this de-escalation notable on its own. U.S. Trade Representative Jamieson Greer said the two sides “have eliminated some of the irritants that we’ve had in the past year,” and Trump himself hinted the deal could touch several major sticking points at once: potential changes to auto tariffs, a possible reduction in steel and aluminum duties, and even a mention of reviving the long-dormant Keystone XL Pipeline.

Talks reportedly also covered Canadian retaliatory tariffs, dairy market access, critical minerals, and defense purchases — a genuinely broad basket of issues for a deal negotiated under this much time pressure.

What’s Still Unresolved

Not everything is settled. Carney has publicly maintained his own “red line, not to be crossed” — protecting Canada’s supply management system for dairy, along with cultural and language protections. Quebec’s government has also signaled openness on dairy quotas specifically, but the two countries, along with Mexico, still face a separate, larger negotiation over the future of the USMCA trade agreement that governs North American trade more broadly.

In other words, this pause buys time and goodwill, but it doesn’t resolve the underlying tension — it just moves the deadline from “tonight” to a few days out while lawyers finalize documents.

What This Means for Your Wallet

Tariffs on Canadian goods flow directly into prices Americans pay every day — lumber and building materials, dairy products, furniture, and alcohol are all directly affected by whatever final deal emerges. As we noted in our coverage of the broader 2026 tariff landscape, the average American household is already absorbing roughly $900 a year in added costs from this year’s tariff actions across all trading partners combined.

Practical takeaway: if a 50% tariff on Canadian goods had actually taken effect, categories like lumber, furniture, and dairy products would likely have seen price increases within weeks, not months, given how tightly integrated U.S.-Canada supply chains are. This pause is genuinely good news for your grocery and home-improvement budget in the short term — but it’s worth watching whether the “finalized” deal holds, since a similar pattern of last-minute reversals has played out with other trading partners this year.

What You Should Actually Do This Week

  1. Don’t expect immediate price drops. Even with tariffs paused, retailers don’t typically reprice goods overnight — pricing tends to lag policy changes by weeks in either direction.
  2. Watch for the August 21 deadline. That’s when this specific pause expires, and it’s worth checking whether an actual signed agreement follows or whether this becomes another extended standoff.
  3. If you’re planning a big lumber, furniture, or appliance purchase, this is a reasonable window to move forward rather than wait, given the near-term tariff risk has genuinely eased.
  4. Keep an eye on dairy and alcohol prices specifically, since these were named directly in the disputed categories and are the most likely to move first if a final deal changes access terms.

Bottom Line

Trump pauses Canada tariffs is one of those headlines that undersells just how close this came to going a very different way — a deal reached with less than two hours to spare, covering everything from auto tariffs to a potential pipeline revival. Whether this becomes a durable trade agreement or another temporary reprieve in a year full of them remains to be seen, especially with the broader USMCA renegotiation still looming. For now, it’s genuinely good news for anyone who buys Canadian lumber, dairy, furniture, or alcohol — just don’t assume the story is fully over until the documents are actually signed.


This article is for informational and educational purposes only and does not constitute financial or investment advice. Trade policy is unpredictable and can change rapidly; consult a licensed financial advisor for guidance specific to your situation.

Moderna Stock Surged 177% in a Single Day — Here’s What Actually Happened

Moderna Stock Surged 177% in a Single Day — Here’s What Actually Happened

A stock move this size almost never happens to a company this large. Moderna stock surged 177% in a single trading session this week, adding nearly $40 billion in market value and marking one of the most dramatic single-day rallies for any major company in recent memory. Here’s exactly what triggered it, why the reaction was so extreme, and what it reveals about betting on binary biotech events.

The Numbers Behind the Moderna Stock Surge

Moderna stock surged as much as 177% on Wednesday, touching an intraday high of $174.38 after opening the session near $63. Merck, Moderna’s partner in the announcement, climbed more than 12% the same day — a smaller percentage move, but still a substantial one for a company with a $333 billion market cap, roughly 13 times Moderna’s size heading into the news.

The catalyst was a Phase 3 clinical trial readout: Moderna and Merck announced their personalized mRNA cancer vaccine, called intismeran autogene, met its main goals in a study of more than 1,100 patients with high-risk melanoma. Combined with Merck’s immunotherapy drug Keytruda, the treatment significantly reduced the risk of the cancer returning after surgery compared with Keytruda alone, and also met a secondary goal of slowing the cancer’s spread to other parts of the body.

Why This Specific Trial Mattered So Much

This wasn’t just another drug trial update — it represents the first successful late-stage (Phase 3) readout for any mRNA-based cancer therapy. Moderna built its reputation during the COVID-19 pandemic as a vaccine maker, but the company has spent years searching for its “second act” as investors questioned whether its technology could work beyond infectious disease. This trial result is the strongest evidence yet that it can.

Moderna CEO Stéphane Bancel didn’t undersell the moment, telling CNN the results were “as big a day for humanity” as November 16, 2020 — the day Moderna first released the late-stage trial data showing its COVID-19 vaccine worked. That’s a genuinely significant comparison from the person who has lived both moments.

Why the Moderna Stock Surge Was So Extreme

A few factors explain why the market reaction was this dramatic rather than a more modest bump:

Moderna’s stock had crashed hard from its pandemic highs. Shares had fallen to a low near $29.81 earlier this year, meaning the company was trading at a fraction of its former value, with the market pricing in significant doubt about its post-COVID future. A genuine breakthrough had enormous room to reprice the stock upward.

This was a binary, make-or-break event. Unlike most earnings reports, which involve gradual beats or misses, a single Phase 3 trial readout is essentially a yes-or-no outcome. The market had been pricing in real uncertainty about whether the cancer vaccine approach would actually work at this late stage, and a clear “yes” removed that uncertainty almost instantly.

It validates Moderna’s entire platform, not just one drug. Analysts noted this result matters beyond melanoma specifically — Moderna and Merck are running nine additional trials across lung, bladder, and kidney cancers using the same underlying mRNA technology, meaning a single successful readout raises expectations across the company’s broader oncology pipeline.

Wall Street responded immediately with upgrades. William Blair analysts upgraded Moderna to “Outperform” from “Market Perform,” while Bank of America raised its price target. RBC Capital Markets called the timing “surprisingly positive,” having expected the readout later in the year.

The Ripple Effect Across the Sector

The rally extended well beyond Moderna and Merck. The Nasdaq Biotechnology Index climbed 5.2% to a record high the same day, and other vaccine developers, including BioNTech, rallied in sympathy. This is a pattern we’ve tracked repeatedly this year across different sectors — a major breakthrough or shock in one company tends to ripple through an entire industry group, whether it’s chip stocks reacting to a single competitive threat or biotech names reacting to a single trial result.

What This Means If You’re Considering the Stock Now

Here’s the honest, non-hype framing rather than a recommendation:

The case for caution: By the time a stock move is this widely covered, the known good news is already reflected in the price. The full trial data hasn’t even been released yet — it’s scheduled for presentation at an upcoming medical meeting, and the companies don’t yet have results on overall survival, a key secondary measure of whether patients actually live longer. Regulatory approval also isn’t guaranteed; only a minority of oncology therapies that reach Phase 3 testing ultimately win approval.

The case for genuine optimism: This isn’t speculative hype — it’s an actual successful late-stage trial with a clear primary endpoint met, tested on a real, meaningful population of patients. Analysts specifically pointed to a credible line of sight toward revenue diversification away from Moderna’s COVID-dependent business, which had been the central bear case on the stock for years.

The Bigger Lesson From This Kind of Move

A 177% single-day gain is a powerful, real-world reminder of why binary biotech events carry a fundamentally different risk profile than most stock investing. Unlike gradual earnings-driven moves, a single trial readout can transform a company’s valuation overnight in either direction — and the same mechanism that produced this historic gain could just as easily have wiped out a large share of the company’s value on a failed trial instead.

What You Should Actually Do

  1. Don’t chase a 177% move purely out of fear of missing out. The dramatic reaction already reflects the known information; the next major catalyst will be the full data release and eventual regulatory decision.
  2. Understand the difference between a strong trial result and a guaranteed approved product. Regulatory review still needs to happen, and full survival data isn’t in yet.
  3. If you’re drawn to biotech investing generally, recognize the binary risk involved. Single-company, single-trial bets carry a fundamentally different risk profile than broad index investing, something we’ve emphasized throughout our coverage of AI-driven stock volatility this year.
  4. Watch for the full data presentation and regulatory filing timeline, since those will be the next real tests of whether this rally holds.

Bottom Line

The Moderna stock surge is one of the most dramatic single-day moves any major company has posted in years, driven by a genuinely significant scientific and business milestone: the first successful late-stage trial for an mRNA cancer vaccine. Whether the stock’s new valuation holds depends on data still to come and a regulatory process that hasn’t started yet — but for a company written off by much of the market just months ago, this week’s results reset the entire conversation about what Moderna’s technology can actually do beyond the pandemic that made it famous.


This article is for informational and educational purposes only and does not constitute investment or medical advice. Stock market movements are unpredictable, especially around clinical trial announcements; consult a licensed financial advisor before making investment decisions.

The 30-Year Treasury Yield Just Hit a 19-Year High — Here’s Why Your Mortgage Just Got More Expensive

The 30-Year Treasury Yield Just Hit a 19-Year High — Here’s Why Your Mortgage Just Got More Expensive

While headlines chase the latest stock market swing, a quieter number just hit a level not seen since 2007 — and it’s about to cost you more on your next mortgage, car loan, or credit card bill than almost anything the Fed does directly. The 30-year Treasury yield hit 5.32% this week, a genuine 19-year high, and understanding why matters far more than it sounds.

What Actually Happened to Treasury Yields

The yield on the 30-year U.S. Treasury bond touched 5.323% on Tuesday before settling just under 5.3% — its highest level since April 2007. The 10-year Treasury yield, the benchmark that matters most for everyday borrowing, crossed above 4.7%, a sharp jump from below 4% before the Iran war escalated in late February. This wasn’t an isolated U.S. move either: the global bond selloff extended to Japan, where 10-year debt touched its highest yield in three decades, and to Germany and France, where long-term borrowing costs hit levels unseen since before the 2008 financial crisis.

Why the 30-Year Treasury Yield Matters More Than the Fed Right Now

Here’s the part most people misunderstand: your mortgage rate doesn’t directly track the Federal Reserve’s interest rate decisions. Fixed mortgage rates follow the 10-year Treasury yield far more closely, since lenders use it as their pricing benchmark. That means even if the Fed holds rates steady, as we’ve covered throughout its recent divided decisions, mortgage rates can still climb sharply if bond investors are demanding higher returns — which is exactly what’s happening now.

As Capital Economics economist Thomas Ryan put it, rising Treasury yields are “just another drag for households when you’ve got affordability hits elsewhere,” with little relief in sight on the borrowing cost side.

Three Forces Driving Yields to a 19-Year High

1. Persistent inflation concerns. July’s Consumer Price Index rose 3.4% year-over-year, well above the Fed’s 2% target and up sharply from 2.4% back in January before the war began. Energy prices alone climbed 14.7% year-over-year, as Iran’s restrictions on shipping through the Strait of Hormuz have disrupted global oil trade — a story we’ve tracked closely all year.

2. A rapidly growing national debt. The federal government is projected to run a roughly $2.1 trillion budget deficit this fiscal year, with total debt approaching $40 trillion. Investors are demanding higher compensation to keep lending to a government whose debt load keeps expanding, pushing yields higher across the board.

3. Record corporate bond issuance. U.S. companies have issued nearly $1.7 trillion in bonds so far this year, up 27% from the same period last year and already exceeding all of 2025 combined — much of it tied to AI infrastructure spending we’ve covered extensively. That flood of new corporate debt competes directly with Treasurys for investor money, adding further upward pressure on yields.

What This Means for Your Actual Borrowing Costs

The ripple effects are already showing up in real numbers:

  • Mortgage rates: The average 30-year fixed mortgage rate climbed to 6.75% this week, up from 6.69% just days earlier, and from 6.66% in late July
  • Auto loans: Borrowers financing a new vehicle now face APRs around 7%, while used car buyers are contending with rates near 10.6%
  • Credit cards and variable-rate debt: These track more closely to the Fed’s short-term rate, but continue facing pressure from the broader high-rate environment we’ve documented in our coverage of the credit card minimum payment trap

The One Silver Lining: Better Returns for Savers

Rising yields aren’t universally bad news. If you’re a saver rather than a borrower, higher Treasury yields typically translate into better returns on CDs and high-yield savings accounts, since banks compete for deposits against increasingly attractive government-backed alternatives. If you haven’t checked your savings account rate recently against current options, this is a reasonable moment to compare.

What You Should Actually Do About Rising Treasury Yields

  1. If you’re house hunting, don’t wait for rates to improve on their own. With yields at a 19-year high driven by structural forces (debt, inflation, corporate borrowing) rather than a temporary blip, there’s no strong signal rates will drop meaningfully soon.
  2. If you’re refinancing, run the actual math before committing. A rate that looked unattractive a year ago may still beat waiting given the current trajectory.
  3. Shop around aggressively for auto financing. With new car APRs near 7% and used car rates above 10%, even a one-point difference between lenders meaningfully changes your total cost.
  4. Take advantage of better savings rates if you have cash sitting idle. Higher yields mean this is genuinely a better environment for savers than borrowers.
  5. Watch the 10-year yield specifically, not just Fed announcements, since it has more direct influence on your mortgage than the Fed’s own rate decisions.

Why This Could Get Worse Before It Gets Better

Bond strategist Ian Lyngen of BMO Capital Markets noted that “the path of least resistance will likely favor higher long-end rates in the near-term” unless there’s a slowdown in new bond supply — something that isn’t showing signs of happening yet given the scale of both government deficits and corporate issuance. That’s a genuinely important signal: this isn’t a one-week story that resolves itself, but a structural trend worth monitoring over the coming months.

Bottom Line

The 30-year Treasury yield hitting its highest level since 2007 might sound like an abstract bond market story, but it’s already translating into real, higher costs for anyone financing a home, car, or major purchase right now. Unlike Fed rate decisions, which get extensive headline coverage, this Treasury yield story has moved with far less attention — even though it’s arguably influencing your monthly payments more directly. Understanding the connection between Treasury yields and your own borrowing costs is the difference between being caught off guard by a higher mortgage quote and actually planning around it.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor or mortgage professional for guidance specific to your borrowing decisions.

Nobody Was Watching This Stock — Now SanDisk Stock Is Up 700% and Beating Every Company in the S&P 500

Nobody Was Watching This Stock — Now SanDisk Stock Is Up 700% and Beating Every Company in the S&P 500

While most investors have their eyes on Nvidia, Microsoft, and the usual AI headliners, one company most casual investors barely recognized a year ago has quietly become the best-performing stock in the entire S&P 500. SanDisk is up more than 700% in 2026, and this week’s investor day sent shares surging even further. Here’s the real story behind one of the most dramatic stock rallies of the year, and what it reveals about where AI spending is actually flowing.

The Numbers Behind SanDisk’s Rally

SanDisk shares surged 726% in the first half of 2026 alone, making it the top-performing stock in the S&P 500 — more than double the gain of the index’s second-best performer, Micron, which rose 266% over the same stretch. The momentum hasn’t slowed since. This week, shares jumped as much as 16% after the company’s investor day, where management laid out new long-term growth targets, before extending gains further on JPMorgan’s upgrade and Bank of America raising its price target to $2,500 from $2,100.

For context on just how unusual this move is: SanDisk stock climbed from around $1,214 on July 31 to above $1,528 by mid-August — a genuinely extraordinary run for a company that spun off from Western Digital as recently as February 2025.

What SanDisk Actually Does (And Why It’s Suddenly So Valuable)

SanDisk makes NAND flash memory and enterprise solid-state drives (SSDs) — the storage technology that holds the massive datasets AI systems need to function. As AI infrastructure has exploded in scale throughout 2026, demand for high-capacity, high-performance storage has surged right alongside demand for the processors getting most of the headlines.

JPMorgan analyst Harlan Sur summed up the core thesis clearly, noting SanDisk is uniquely positioned to capture what he called a “structural inflection in NAND demand driven by rapid growth in AI inference.” In plainer terms: as AI shifts from being trained to actually being used at scale, the storage requirements are proving just as critical a bottleneck as computing power itself.

The Investor Day That Reignited the Rally

This week’s surge specifically followed SanDisk’s investor day, where management unveiled a new business model built around multi-year customer agreements, continued technology innovation, and AI-driven data center growth. The company targets mid-to-high-teens revenue growth with 80% gross margins, alongside a substantially expanded share buyback program.

Perhaps most notably, management is explicitly trying to reposition what has historically been a highly cyclical, boom-and-bust business into something steadier and more predictable — a pitch that clearly resonated, given the stock’s reaction. SanDisk’s Q3 non-GAAP gross margin already hit 78.4%, and the company has guided for 79% to 81% in Q4, driven by rising prices and disciplined supply management rather than simply selling more units.

Why This Ripples Beyond SanDisk Itself

The reaction to SanDisk’s investor day extended well beyond its own stock. SanDisk’s partner Kioxia rallied in Tokyo, while SK Hynix posted strong gains in Seoul, as investors broadened their exposure to companies positioned to benefit from growing AI storage demand. This matters because it echoes a pattern we’ve tracked closely all year in the semiconductor and memory sector — from the earlier chip stock bear market to the dramatic swings tied to global memory supply chains.

The S&P 500 closed at a record high the same week, with the Nasdaq also advancing, suggesting SanDisk’s story is feeding into broader confidence about AI infrastructure spending rather than existing in isolation.

Should You Actually Buy SanDisk Stock?

As always, here’s the honest, non-hype answer rather than a recommendation:

The bull case: SanDisk has a debt-free balance sheet, high margins, strong cash generation, and a specific, well-articulated multi-year growth plan backed by real revenue results — its most recent quarter posted revenue of $5.95 billion, up 251% year-over-year, dramatically beating guidance of $4.4 to $4.8 billion.

The genuine risk: A stock up over 700% in roughly seven months has priced in enormous future expectations. Historically cyclical businesses like NAND memory have disappointed investors before when demand cycles turned, even when the underlying technology story remained intact. A stock trading at this kind of momentum can also see sharp, fast pullbacks if any single earnings report or guidance update disappoints, even slightly — a pattern we’ve seen repeatedly with other AI-linked names this year.

What This Means for Your Portfolio

  1. Don’t chase a 700% rally purely out of fear of missing out. By the time a stock’s momentum is this widely covered, professional investors have typically already priced in much of the known good news.
  2. Understand the difference between a strong company and a strong stock price. SanDisk’s fundamentals are genuinely impressive, but that doesn’t automatically mean the current valuation offers a good entry point — those are two separate questions.
  3. Watch for confirmation in the next earnings cycle. SanDisk’s next report will be the real test of whether this growth trajectory holds, similar to how we’ve watched other AI-infrastructure names prove or fail to prove their spending was translating into real revenue.
  4. If you already hold broad market or tech-sector index funds, you likely have some indirect exposure already given SanDisk’s now-significant weight in the S&P 500.

Bottom Line

SanDisk’s rise from a relatively obscure spinoff to the best-performing stock in the S&P 500 is a genuinely remarkable story, and it offers a clear real-world lesson: the AI infrastructure boom isn’t only rewarding the companies making headlines — it’s flowing into the less glamorous layers of the supply chain, like memory and storage, that turn out to be just as critical. Whether SanDisk can sustain this momentum depends on execution against genuinely ambitious targets, but for now, it stands as one of 2026’s clearest examples of how quickly market leadership can shift toward companies most investors weren’t watching closely a year ago.


This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Stock market movements are unpredictable, and past performance does not guarantee future results; consult a licensed financial advisor before making investment decisions.

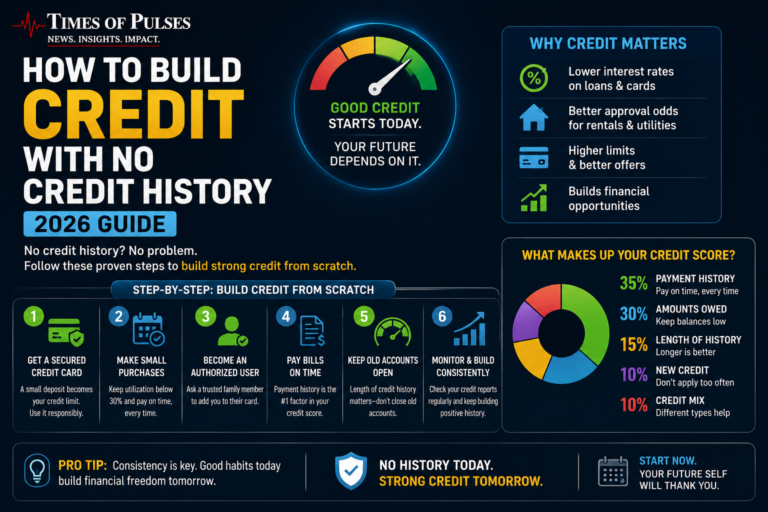
This guide shows you exactly how to build credit with no credit history in 2026, starting with tools that cost almost nothing.

0

This guide shows you exactly how to build credit with no credit history in 2026, starting with tools that cost almost nothing.

If you’ve never borrowed a dollar in your life, you don’t have a credit history — and without one, lenders can’t see whether you’re trustworthy. It’s a frustrating catch-22: you need credit to get credit. The good news is that this exact situation is more common than you think, and there’s a proven, step-by-step way out of it. This guide shows you exactly how to build credit with no credit history, starting with tools that cost almost nothing.

Why No Credit History Is a Real Problem (Not Just Inconvenient)

In the United States, your credit history is the record lenders, landlords, and sometimes even employers use to judge your financial reliability. The most common scoring model, the FICO Score, ranges from 300 to 850, and your score is built almost entirely from how you’ve handled borrowed money in the past.
Here’s what the latest data shows: the average American’s FICO Score was 713 at the end of 2025, and 70% of consumers now hold a “good” score of 670 or higher .That means roughly 30% of Americans — nearly 100 million people — have fair or poor credit, and a significant share of those are stuck with no history at all: young adults, recent immigrants, and people who have simply never used credit.
The cost of having no history (or a thin file) is real. People without established credit often face higher interest rates, larger security deposits on apartments, and sometimes outright rejection. As we covered in our , credit applications in 2025 saw the highest rejection rates in years — and being invisible to lenders is often worse than having a mediocre score.

How Credit Scores Actually Work: The 5 Ingredients

Before building credit, you need to know what you’re building. A FICO Score has five components, and their weightings matter more than most people realize:
Factor
Weight
What It Means for You
Payment history
35%
Pay every bill on time. Always. This is the single biggest lever.
Amounts owed (utilization)
30%
Keep balances below 30% of your limit — under 10% is even better
Length of credit history
15%
Older accounts help; this is why starting early wins big
Credit mix
10%
A mix of card + installment loan scores slightly higher
New credit
10%
Too many applications in a short time hurt your score
Notice that payment history and utilization together make up 65% of your score. That’s the good news: you don’t need to be rich to build credit. You need to be consistent.

The 6-Step Plan to Build Credit with no credit history From Scratch

Step 1: Check Your Credit Report First (It’s Free)

Before building anything, confirm you actually have no history — and no errors. Under federal law, you’re entitled to a free credit report from all three bureaus (Experian, Equifax, and TransUnion) every week at , the official site run under CFPB authorization .
Why does this matter before you start? Because roughly 1 in 4 consumers have found an error on their credit report at some point, and errors on a thin file are devastating — a single false late payment on a three-account file does far more damage proportionally than on a thirty-account file. Disputing errors early is the cheapest credit repair you’ll ever do. (For a deeper look at fixing errors, see our .)

Step 2: Become an Authorized User (The Fastest Start)

If a parent, spouse, or trusted family member has a credit card with a long, clean history, ask them to add you as an authorized user. Their account’s positive history appears on your report, effectively letting you “inherit” years of good payment behavior overnight .
Two rules for this to work: the card issuer must report authorized users to the credit bureaus (most major issuers do — call and confirm), and the primary cardholder must keep paying on time, because their late payments would now hurt your score too.

Step 3: Get Your First Card — and Pick the Right Type

If no family option exists, apply for a student credit card (if you’re in school) or a secured credit card. A secured card requires a refundable deposit — typically $200 to $500 — which becomes your credit limit. It looks and works like a normal card, and after 12–18 months of good behavior, most issuers return your deposit and convert it to an unsecured card .
When choosing, check three things: no annual fee (or a very low one), that it reports to all three bureaus, and that it offers a path to graduation into an unsecured card. The CFPB’s guidance on secured cards is a good starting point for comparing your options .

Step 4: Use the Card Like It’s a Debit Card

This is where most people fail. The formula is embarrassingly simple, yet millions blow it every month:
1.Charge one small recurring bill (Netflix, phone plan) — around $20–30
2.Set up autopay for the full statement balance
3.Never let utilization cross 30% — with a $300 limit, that means never owing more than $90 at statement time
A quick calculation shows why the 30% rule matters. On a $500 secured card, carrying a $450 balance (90% utilization) signals distress to scoring models and can hold your score down by 50+ points. Keep it at $50–100 and the same payment history builds your score roughly twice as fast. As we detailed in our , paying only the minimum on a revolving balance is how solid credit habits quietly turn into a years-long debt cycle.

Step 5: Add a Credit-Builder Loan (Optional but Powerful)

Once your card is 6+ months old, consider a credit-builder loan — small loans ($500–$1,500) where the money sits in a savings account while you make payments, and those payments get reported to the bureaus. Credit unions and fintech lenders like Self offer these specifically for people building credit from scratch .
This adds the installment-loan component to your credit mix (that 10% factor) and reinforces the payment-history component at the same time. Interest is usually modest, and some products even return most of it as savings.

Step 6: Monitor and Protect What You’ve Built

Set a calendar reminder to pull your three reports at every few months during your first two years. Watch for: accounts you didn’t open (identity theft), balances you already paid, and late payments you made on time. Each dispute takes minutes online and can protect months of your building work.
Also remember that checking your own credit never hurts your score — only lender inquiries do. You can monitor freely through your bank’s app or free services like Experian’s free tier.

Realistic Timeline: What to Expect

Managing expectations matters, so here’s an honest roadmap based on how scoring models actually behave:
Milestone
Realistic Timeframe
What’s Happening
First score appears
3–6 months
Models need ~6 months of reported history to generate a score
First “fair” score (580–669)
6–12 months
Consistent on-time payments accumulating
First “good” score (670+)
12–24 months
Low utilization + clean history compound together
The single biggest mistake people make is quitting at month 4 because “nothing is happening.” Credit history is a length-of-time game — which is exactly why starting now beats starting “someday.”

How This Fits Into Your Bigger Money Picture

Building credit isn’t a standalone project — it locks in with the rest of your financial foundation. A good score eventually unlocks cheaper auto loans and mortgages, which directly lowers the squeezing American households right now. And while you’re building credit, don’t neglect the other side of the ledger: the shows how even $5 a week compounds into a real safety net — because the fastest way to wreck new credit is an emergency that forces you back onto a card.

Frequently Asked Questions

Can I build credit without a credit card?

Yes. Credit-builder loans, rent-reporting services (like Experian RentBureau, which adds rent payments to your report), and being an authorized user all build history without you ever carrying a card balance.

How long does it take to go from no credit to a 700 score?

Typically 18–24 months with one well-managed card. There are no shortcuts — anyone promising a “700 in 30 days” fix is selling something.

Does my income affect my credit score?

No. Income isn’t part of the FICO formula at all. Lenders check income separately when you apply, but your score only reflects how you’ve handled credit.

Will applying for a card hurt my score?

A single application causes a small, temporary dip (usually under 5 points). The damage comes from many applications in a short window — so pick one good card and apply once.

Can bad credit be fixed, or is it permanent?

Negative marks fade. Late payments drop off after 7 years, and newer positive history pushes them down in influence far sooner. Our covers the full recovery process.

Disclaimer
This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor for guidance specific to your debt situation.

America’s “K-Shaped” Economy Is Real — Here’s What the New Credit Card Data Proves

0

America’s “K-Shaped” Economy Is Real — Here’s What the New Credit Card Data Proves

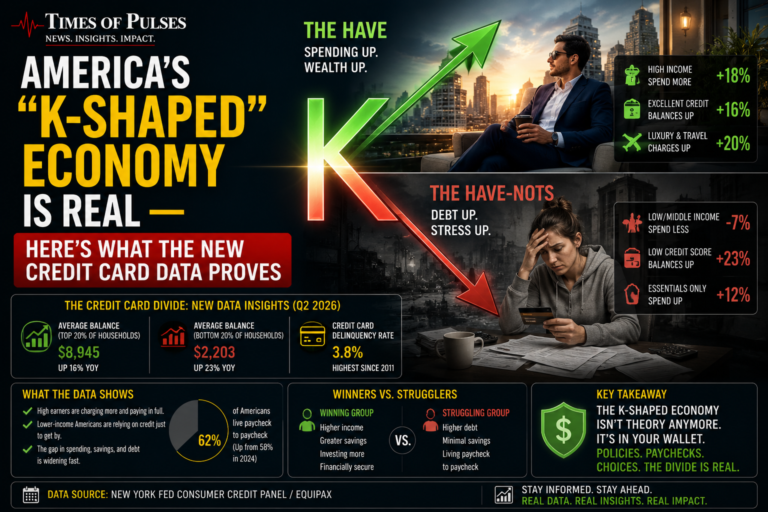
Some households are thriving right now. Others are falling apart financially. New data released this week from the Federal Reserve Bank of New York confirms both are true at the same time — and the credit card numbers behind it are genuinely stark. Here’s what the K-shaped economy actually means, why credit card debt just hit $1.26 trillion, and where you might fall on that split.

What “K-Shaped Economy” Actually Means

A K-shaped economy describes exactly what it sounds like: picture the letter K, where one line trends upward and the other trends downward from the same starting point. Applied to households, it means higher-income Americans are generally maintaining stability or even improving their financial position, while lower-income households are falling further behind — both happening simultaneously, within the same overall economy.

The New York Fed’s own researchers used this exact framing this week, saying the new credit card data “reflects this K-shaped economy” directly, even as the current U.S. Treasury Secretary has publicly downplayed the idea that this divide still exists.

The Numbers Behind the K-Shaped Economy Right Now

The Federal Reserve Bank of New York’s Quarterly Report on Household Debt and Credit, released this week, shows credit card balances climbed $21 billion in the second quarter to reach $1.26 trillion — reversing a seasonal decline from earlier in the year and nearing last year’s all-time high of $1.28 trillion.

The more revealing number sits inside the delinquency data. The share of credit card balances in “late-stage delinquency” — meaning over 90 days past due — jumped to 12.8% from 7.6% in the second quarter, a level the New York Fed says hasn’t been seen since the Great Recession. Researchers did note this specific figure is a lagging indicator, reflecting past charge-offs still showing up on credit reports, rather than a real-time snapshot.

Why the K-Shaped Economy Shows Up Differently Across Income Levels

This isn’t just credit cards. The New York Fed researchers pointed out that elevated delinquency rates are “more pronounced in the lowest-income areas” across multiple debt types — not just credit cards, but auto loans, home equity lines of credit, and even rising mortgage delinquency rates among homeowners falling behind on payments.

Meanwhile, roughly 60% of the 175 million Americans who have credit cards carry a balance from month to month, according to the New York Fed — a group directly exposed to today’s average credit card rate of around 20%, one of the most expensive ways to borrow money available. That combination — rising balances, elevated rates, and worsening delinquency concentrated among lower-income borrowers — is precisely what defines the downward arm of the K-shaped economy.

The Upward Arm: Why Some Households Are Doing Fine

The other side of the K-shaped economy looks genuinely different. Higher-income households, which skew older and are more likely to own homes, have generally maintained spending levels and stability, benefiting from home equity built up over years and less reliance on high-interest revolving debt to cover everyday expenses. This isn’t a coincidence — it reflects a household’s cumulative financial buffer built before the current stretch of persistent inflation, not just their current income alone.

Why This Divide Matters Beyond Individual Households

Andrew Housser, co-founder of financial services firm Achieve, offered a genuinely important warning about this trend: “the longer this persists, the more the gap widens.” This isn’t a self-correcting pattern — households already falling behind face compounding interest costs that make catching up progressively harder, while households with a financial cushion continue benefiting from stability that reinforces itself.

The New York Fed’s separate Survey of Consumer Expectations, released alongside this report, found fewer consumers now expect their household finances to improve over the next year, with a growing share expecting things to get worse — a sentiment shift that spans the K-shaped divide even if it hits harder on one side.

Where You Might Fall on the K-Shaped Divide

A few honest questions can help you understand your own position:

  1. Are you carrying a credit card balance month to month? If so, you’re part of the roughly 60% of cardholders directly exposed to today’s elevated interest rates — and as we’ve covered in our reporting on the credit card minimum payment trap, this is exactly the pattern that compounds fastest.
  2. How does your delinquency status compare to a year ago? If you’re falling further behind rather than catching up, that mirrors the exact pattern New York Fed researchers are flagging as most concerning.
  3. Do you have a financial buffer — home equity, savings, or an emergency fund — that insulates you from needing to rely on credit cards for everyday expenses? This buffer is largely what separates the two arms of the K.

What You Should Actually Do If You’re on the Downward Side

  1. Prioritize paying more than the minimum on your highest-interest card first, since 20% average rates mean minimum-only payments barely touch your actual balance
  2. Build even a small emergency fund alongside debt payoff, so the next unexpected expense doesn’t add directly to your credit card balance — we’ve covered specific strategies in our guide to closing the emergency fund gap
  3. Contact your card issuer proactively if you’re at risk of falling into late-stage delinquency, since many offer hardship programs that are meaningfully better than letting an account go 90+ days past due
  4. Track your own numbers against this data, not to compare yourself to others, but to catch a worsening trend before it compounds further

Bottom Line

The K-shaped economy isn’t an abstract economic theory — this week’s New York Fed data shows it playing out in real numbers: $1.26 trillion in collective credit card debt, delinquency rates at levels not seen since the Great Recession, and a divide that researchers say is concentrated specifically among lower-income households. Whether policymakers acknowledge the term or not, the underlying pattern is measurable and, per the Fed’s own researchers, likely to keep widening the longer it goes unaddressed. Understanding which side of that K your own household sits on is the first step toward either protecting your position or actively working to change it.


This article is for informational purposes only and does not constitute financial advice. Consult a licensed financial advisor for guidance specific to your debt situation.

Oil Prices Hormuz Deadlock: Why Crude Keeps Swinging as the Iran Deal Stalls


Oil Prices Hormuz Deadlock: Why Crude Keeps Swinging as the Iran Deal Stalls

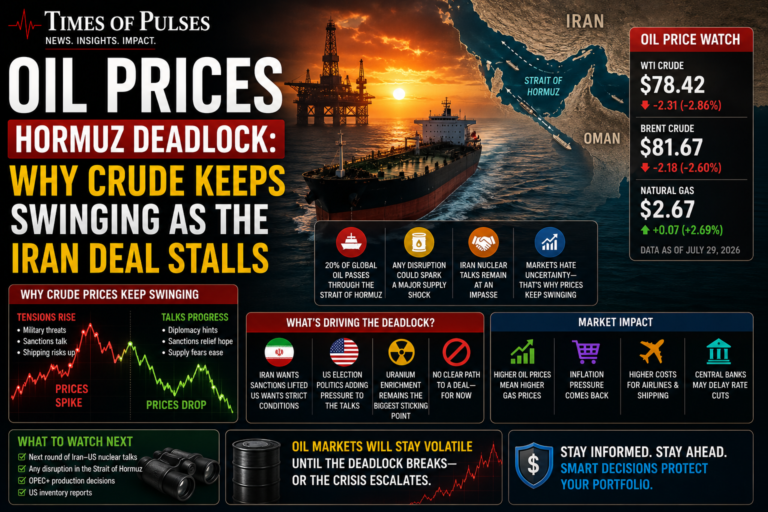
If you feel like oil prices have been doing the opposite of whatever you expected all week, you’re reading the situation correctly. The oil prices Hormuz deadlock story has become one of the more genuinely confusing energy narratives of 2026 — a rapid plunge on deal hopes, followed just days later by a climb back as prospects for an imminent deal fade rather than firm up. This isn’t ordinary market noise. It’s a real-time diplomatic standoff playing out in barrel prices, and it’s worth understanding before you fill up your tank again.

How We Got Here: A Genuine Rollercoaster Week

Just under a week ago, oil prices Hormuz deadlock headlines were actually optimistic. A senior Trump administration official said a deal to reopen the Strait of Hormuz could be reached “today or tomorrow,” and Treasury Secretary Scott Bessent told CNBC there was a real chance of an agreement within hours. Markets reacted immediately: Brent crude tumbled more than 6% to below $79 a barrel on the rekindled hope alone. Qatar, acting as mediator between Washington and Tehran, confirmed talks were ongoing even as Iran publicly denied direct negotiations with the US.

That optimism didn’t last. Iran has since laid out its own conditions for reopening the waterway, insisting it won’t restore normal shipping without major concessions from the United States. Brent crude has climbed back more than 1% as those demands cloud the outlook, and as of this week, prospects for an imminent deal are fading rather than firming up.

Why the Oil Prices Hormuz Deadlock Situation Matters More Than a Typical Price Swing

The Strait of Hormuz carries roughly a fifth of the world’s oil supply, so any real uncertainty about its status tends to move markets more than most single geopolitical headlines. What makes this particular stretch of the oil prices Hormuz deadlock story unusual is the speed of the reversal — a 6% one-day plunge on hope, followed by a steady climb back as that same hope faded, all within about a week.

One commodities economist put it plainly: market moves won’t stay this “benign” if the deadlock drags into next week. That’s a meaningful warning, because a few other pressures are quietly building in the background that could make the next move sharper than the last one:

  • China’s crude imports are rising, adding demand pressure at exactly the wrong moment for a market already nervous about supply
  • Houthi attacks on Saudi infrastructure remain an active risk that could disrupt output independent of anything happening in the strait itself
  • Residual risk of reversal. Even analysts who expect a diplomatic breakthrough eventually note that any deal could just as easily unravel again, which limits how far prices are likely to fall even on genuinely good news

What This Means for Your Gas Budget

If this is starting to sound familiar, it’s because it echoes a pattern we’ve covered before with gas prices reacting to the broader Iran conflict earlier this year — prices spike fast on bad news and come down much more slowly, even when the underlying tension eases. The current back-and-forth makes budgeting around gas prices unusually difficult right now, because a single diplomatic phone call can move prices several percentage points in either direction within a day.

Practical takeaway: don’t assume this week’s price is a reliable baseline for next month. With talks this fluid, building a small buffer into your fuel budget is more useful right now than trying to time a “good week” to fill up — the same emergency fund logic that helps with any unpredictable expense applies just as well here.

What This Means for Your Portfolio

  1. Energy stocks are likely to stay volatile alongside the headlines — don’t read any single day’s move as a lasting trend until the deadlock actually resolves one way or the other.
  2. Watch for the deal breaking through vs. the deadlock extending past this week — both economists quoted in current coverage flag next week as a meaningful threshold for whether this stays “benign” or turns into a sharper move.
  3. If you hold broad index funds, this is a story to watch rather than react to. Energy sector weighting in most diversified funds is modest enough that a single geopolitical story rarely justifies a portfolio change on its own.

Bottom Line

The oil prices Hormuz deadlock saga is a genuine reminder of how fast sentiment-driven markets can swing when a deal feels close one day and stalled the next. Prices plunged on hope, climbed back on disappointment, and now sit in a genuinely uncertain spot with real pressures (China’s demand, Houthi risk) building underneath the headlines. If you’re budgeting for gas or watching energy stocks, the smartest move is the same one that’s worked through every other stretch of this conflict: avoid reacting to any single day’s headline, build in a buffer, and wait for the deadlock to actually break — in either direction — before assuming you know where prices go next.


This article is for informational and educational purposes only and does not constitute financial or investment advice. Geopolitical events and energy markets are unpredictable and can change rapidly; consult a licensed financial advisor before making investment decisions.