VantageScore FICO Mortgage Shakeup: The 20-Year Monopoly Just Ended, and It Could Get You Approved
For more than two decades, if you wanted a mortgage backed by Fannie Mae or Freddie Mac, one company decided whether your credit was good enough: FICO. That’s no longer true. This VantageScore FICO mortgage shakeup just gave every approved lender in America the option to use a different credit score model, one that could qualify millions of people who couldn’t get approved before.
What Actually Changed
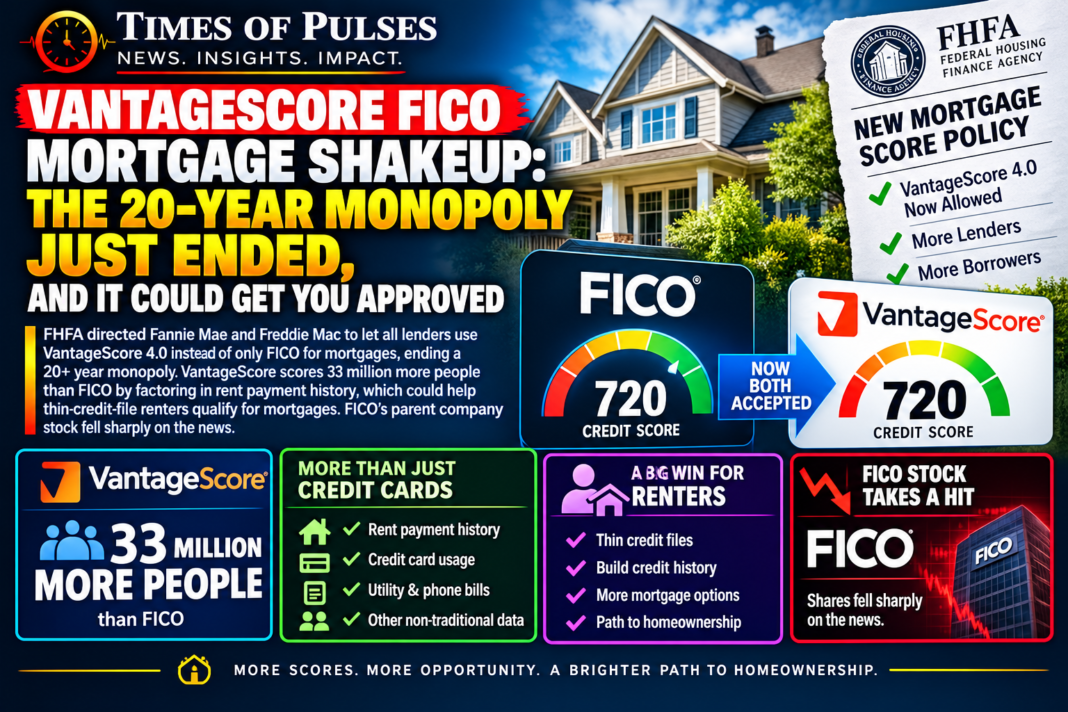
On September 4, 2026, FHFA Director Bill Pulte instructed Fannie Mae and Freddie Mac to immediately approve all lenders to use VantageScore 4.0, expanding a limited rollout that had included around 50 lenders since April. By September 9, the change was formalized across both government-sponsored enterprises through official lender guidance. This VantageScore FICO mortgage decision means lenders can now choose between Classic FICO and VantageScore 4.0 when originating a mortgage sold to Fannie or Freddie, which together back the majority of US home loans.
Pulte announced the move directly on social media, writing that the initial VantageScore rollout had been “incredibly successful” with 50 lenders already delivering loans under it, and moved to open it up to everyone immediately.
Why This VantageScore FICO Mortgage Change Matters So Much
Here’s the detail that makes this genuinely significant rather than just a technical update: VantageScore 4.0 scores 33 million more people than traditional FICO models, largely because it factors in data points Classic FICO doesn’t consider, including rent payment history. If you’ve been paying rent on time for years but have a thin credit file otherwise, this VantageScore FICO mortgage shift could be the difference between qualifying for a home loan and getting rejected.
This isn’t a small or experimental change either. As of August 31, 2026, VantageScore 4.0 had already become the sole credit score used for more than 9% of all mortgages securitized by Fannie Mae and Freddie Mac since May 1. Major lenders including Rocket Mortgage, the FHA, the Federal Home Loan Banks, and the VA have already adopted VantageScore 4.0 for their own mortgage products, well ahead of this broader expansion.
The Market Noticed Immediately
This VantageScore FICO mortgage story wasn’t just a policy footnote, markets reacted to it directly. Shares of Fair Isaac Corporation, the company behind FICO, fell sharply following the September 4 announcement, reflecting real investor concern about what genuine competition in mortgage credit scoring means for a company that’s effectively had no rival in this specific market for decades.
Adding to the pressure, an independent study by Deep Future Analytics estimated the shift to VantageScore 4.0 could save the mortgage market more than $930 million in its first year alone, savings that come from increased competition and reduced credit-pulling costs across the industry.
What This Doesn’t Mean
It’s worth being clear about the limits of this VantageScore FICO mortgage change. Lenders are not required to switch, Classic FICO remains fully valid and widely used, this simply gives lenders a choice they didn’t have before. There’s also an important technical rule: lenders must use the same credit score model for every borrower on a given loan, they can’t mix FICO and VantageScore scores for co-borrowers on the same mortgage. This isn’t an automatic approval button for anyone with bad credit either, VantageScore 4.0 still evaluates creditworthiness, it simply weighs a broader set of financial behavior than FICO’s traditional model does.
What This Means for Your Own Mortgage Plans
- If you have a thin credit file, this VantageScore FICO mortgage change could genuinely help you. If you’ve been paying rent consistently but have limited traditional credit history, ask your lender directly whether they use VantageScore 4.0, it factors in exactly that kind of payment history.
- This connects directly to building credit from scratch. If you’re working on establishing credit with no credit history, rent payment history mattering under VantageScore is a meaningful new avenue worth understanding.
- Not every lender has adopted this yet, so ask. Since the choice between FICO and VantageScore sits with individual lenders, shopping around for a mortgage lender that uses VantageScore 4.0 could be worth the extra research if your credit profile fits that model better.
- Your existing credit habits still matter under either model. Whether you’re scored under Classic FICO or VantageScore, keeping your credit utilization low remains one of the most reliable ways to improve your score under any scoring system.
- This doesn’t remove the impact of rates on affordability. Even with more people qualifying for mortgages, the actual cost of that mortgage still depends heavily on current interest rates, a broader qualification pool doesn’t mean a cheaper loan on its own.
Bottom Line
CNBC’s coverage of the shift put it plainly: mortgage credit scores are evolving, and homebuyers need to understand what that means for them specifically. This VantageScore FICO mortgage change ends a genuine multi-decade monopoly in how the majority of US mortgages are evaluated, and for millions of Americans with thin credit files but solid rent-paying histories, it could be the detail that finally gets a mortgage application approved. Whether your own lender has made the switch is worth a direct question the next time you’re mortgage shopping, this is one of those quiet policy changes that can have an outsized, very personal impact.
This article is for informational purposes only and does not constitute financial advice. Consult a licensed mortgage professional or financial advisor for guidance specific to your situation.