FICO Score 10T Explained: The New Mortgage Model That Grades Your Credit Trend, Not Just Your Score
Just weeks after we covered VantageScore breaking FICO’s mortgage monopoly, FICO itself is rolling out a genuinely different kind of credit score. FICO Score 10T isn’t just an updated version of the same old formula, it changes what lenders are actually measuring, and the FHA just set a firm date for when it takes full effect.
What Is FICO Score 10T, Exactly?
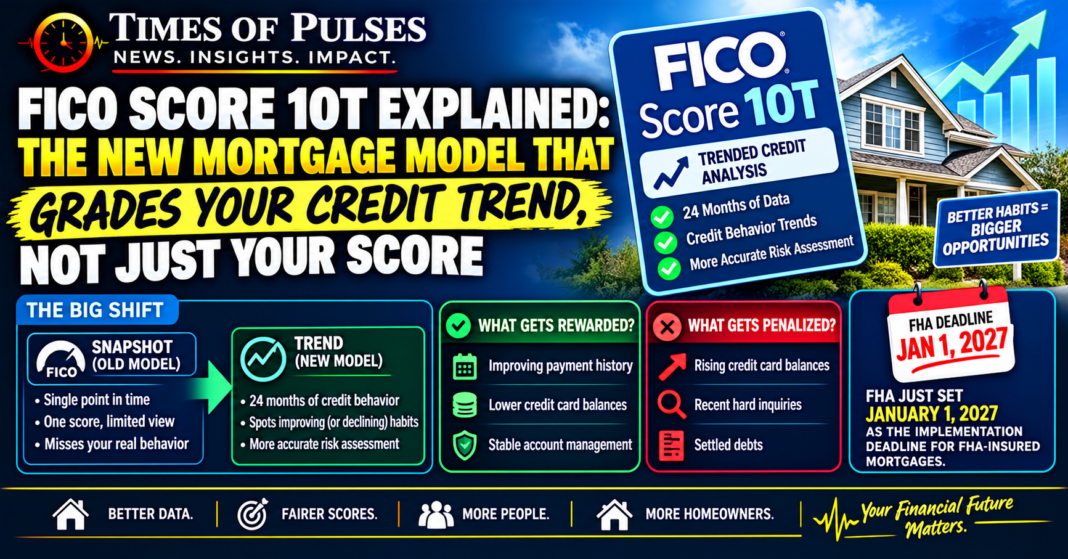
The “T” in FICO Score 10T stands for trended data, and that single word represents the biggest change to mortgage credit scoring in over two decades. Classic FICO evaluates your credit at a single point in time, a snapshot of where your balances and payment history stand the moment your score is pulled. FICO Score 10T instead analyzes your credit behavior over the past 24 months, looking for patterns rather than just a current number.
That means a borrower who carried high balances 18 months ago but has been steadily paying them down will score differently under FICO Score 10T than they would under Classic FICO, typically higher, because the model recognizes the improving trend rather than just where the balance happens to sit today.
Who FICO Score 10T Actually Helps
If you’ve been genuinely improving your financial habits, this is good news. FICO Score 10T rewards consistent, positive behavior over time: steadily declining balances, a track record of on-time payments, and generally improving credit management. People who’ve been quietly doing the right things for the past year or two, without necessarily seeing their Classic FICO score reflect that progress yet, stand to benefit the most from this shift.
Who FICO Score 10T Could Hurt
The flip side matters just as much. FICO Score 10T is notably stricter in several areas than Classic FICO:
- Chronic minimum payments are read as a sign of financial strain and scored more harshly, even if you’re technically never late.
- Rising balances over time, even with on-time payments, get flagged as a stress signal since the model can see the trend Classic FICO couldn’t.
- Recent hard inquiries and newly opened accounts carry more weight, so anyone who’s applied for multiple credit cards or loans in the past 6-12 months will feel that more under this model.
- Settled debts or recent delinquencies are judged more harshly and don’t fade from consideration as quickly as they did under older scoring approaches.
The Timeline: When This Actually Takes Effect
Here’s the news that makes this worth covering right now: the FHA has officially set January 1, 2027, as the implementation date for adding both VantageScore 4.0 and FICO Score 10T as eligible credit score models for FHA-insured mortgage underwriting, following an FHA announcement from earlier this year. On the Fannie Mae and Freddie Mac side, FICO Score 10T historical data was already published July 1, 2026, with the FHFA having validated the model back in April 2026, meaning the rollout has been happening gradually rather than all at once, and is now approaching a hard deadline for FHA loans specifically.
How FICO Score 10T Differs From VantageScore 4.0
It’s worth being clear about the distinction between these two new models, since they’re often mentioned together but work differently. VantageScore 4.0’s headline feature is including alternative data like rent, utility, and telecom payments, which is why it can score millions of people with thin credit files who were previously invisible to the system. FICO Score 10T’s headline feature is trended data, analyzing your behavior pattern over 24 months rather than including new data sources. Both push mortgage lending toward a more complete financial picture, but they get there through different mechanisms, and depending on your specific credit history, one could genuinely score you better than the other.
What This Means for Your Own Credit
- If you’re planning to buy a home in the next year, your recent credit behavior matters more than ever. New credit applications, rising balances, or a pattern of minimum payments over the past 24 months could weigh against you more under FICO Score 10T than they would have under the current system.
- Consistency now pays off later. If you’ve been managing your credit utilization carefully, that sustained good habit is exactly what FICO Score 10T is designed to reward, more so than a single strong score at one moment.
- Watch how any BNPL or split pay activity fits into this picture. As split pay credit reporting continues evolving, keep in mind that trended-data models like FICO Score 10T are built to catch exactly the kind of overlapping payment patterns that split pay users sometimes lose track of.
- Ask your lender which model they’re using, and when. With the January 1, 2027 FHA deadline approaching and Fannie/Freddie already accepting FICO Score 10T data, the model your mortgage gets evaluated under may depend on exact timing as much as which lender you choose.
Bottom Line
The FHA’s own announcement confirms this isn’t a distant, hypothetical change, it’s a scoring model with a real deadline now attached to it. FICO Score 10T represents a genuine philosophical shift in how mortgage lenders read your credit: not just where you stand today, but where you’ve been heading for the past two years. Combined with VantageScore’s expanded reach into rent and alternative data, mortgage credit scoring is undergoing its biggest transformation in decades, and understanding both models now, well before you actually apply, is worth the time.
This article is for informational purposes only and does not constitute financial advice. Consult a licensed mortgage professional or financial advisor for guidance specific to your situation.