New Tax Deductions 2026: The 6 Breaks Most People Don’t Know About Yet
Tax season feels far away right now, but the deductions you’ll actually be able to claim depend on decisions you make throughout the year, and 2026 brought some genuinely new options to the table. These new tax deductions 2026 come courtesy of the One Big Beautiful Bill Act, and several of them apply to income categories that had zero special tax treatment just a year ago.
New Tax Deductions 2026: No Tax on Tips
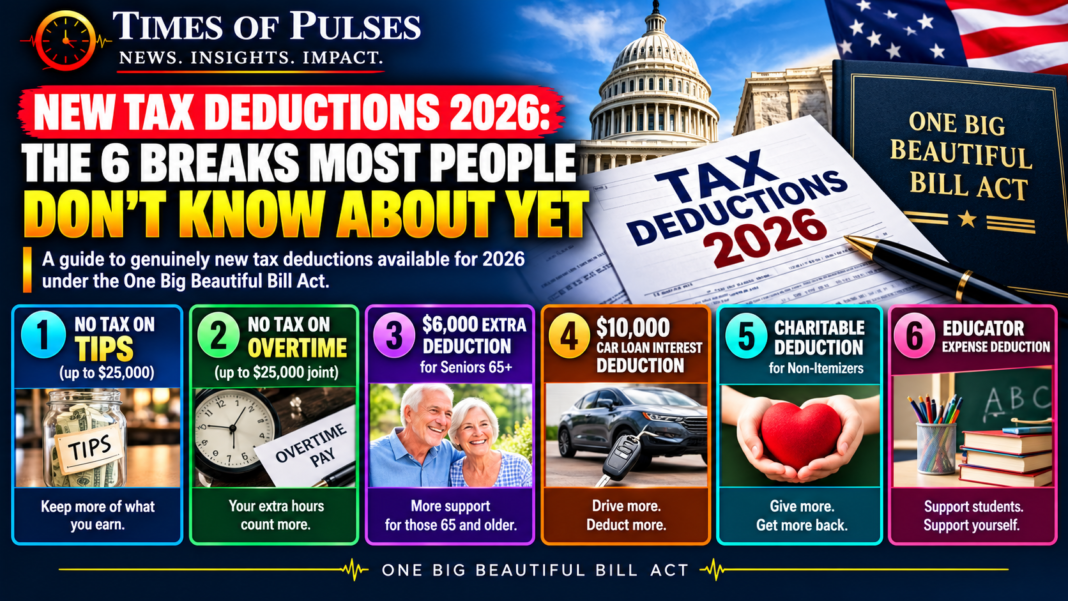
For the first time, tipped workers can deduct up to $25,000 in qualified tips from their taxable income. This is one of the more talked-about new tax deductions 2026 introduced, and it applies whether you take the standard deduction or itemize. If you work in a tipped role, restaurant service, bartending, salon work, or similar, this deduction can meaningfully lower your taxable income without requiring any change to how you already report tip income.
New Tax Deductions 2026: No Tax on Overtime
Workers who put in overtime hours got a break too. Individuals can now deduct up to $12,500 in qualified overtime pay, and married couples filing jointly can deduct up to $25,000. Like the tips deduction, this is available regardless of whether you itemize, making it one of the more broadly accessible new tax deductions 2026 for hourly workers specifically.
New Tax Deductions 2026: A $6,000 Break for Seniors
Taxpayers 65 and older can claim an additional $6,000 deduction, on top of the existing additional standard deduction seniors already receive. Married couples where both spouses qualify can claim up to $12,000 combined. This benefit phases out for higher earners, starting at $75,000 in modified adjusted gross income for single filers and $150,000 for married couples filing jointly, so it’s worth checking where your income falls before assuming you’ll get the full amount. The IRS has confirmed this deduction runs through the 2028 tax year, not just 2026, so it’s a multi-year benefit rather than a one-time change.
New Tax Deductions 2026: Car Loan Interest Deduction
Here’s one of the more surprising additions among the new tax deductions 2026: individuals can now deduct up to $10,000 in qualified passenger vehicle loan interest. This is a genuinely new category of deduction, car loan interest previously offered no special tax treatment at all for personal vehicles. If you financed a car this year, it’s worth keeping documentation of your loan interest paid, since this deduction is also available whether or not you itemize.
New Tax Deductions 2026: Two Small Additions for Non-Itemizers
Two smaller but useful changes round out this year’s new tax deductions 2026 list. A new charitable deduction for non-itemizers lets you deduct charitable donations even if you’re taking the standard deduction, something previously reserved almost entirely for itemizers. Separately, an itemized deduction for educator expenses gives teachers a way to deduct classroom supply costs, a long-requested change for a group that frequently pays out of pocket for materials.
The Standard Deduction Also Went Up
Beyond the new categories, the IRS’s annual inflation adjustment pushed the standard deduction higher for 2026: $16,100 for single filers and married individuals filing separately, $32,200 for married couples filing jointly, and $24,150 for heads of household. According to the IRS’s official announcement, most taxpayers will continue claiming the standard deduction rather than itemizing, even with all these new tax deductions 2026 available, since many of the new breaks (tips, overtime, seniors, car loans) apply on top of the standard deduction rather than requiring you to itemize at all.
What This Means for Your Own Taxes
- Start tracking now, not in April. If any of these new tax deductions 2026 apply to you, tips, overtime, a car loan, or age 65+, keep records throughout the year rather than trying to reconstruct them at tax time.
- Small business owners have a related change worth checking. The Qualified Business Income deduction now guarantees a $400 minimum for anyone with at least $1,000 in qualified business income, relevant if you’re weighing financing options for your small business this year.
- The car loan interest deduction changes the math on financing a vehicle. If you’re deciding whether to pay off debt or keep cash in savings, a deductible car loan is a slightly different calculation than non-deductible debt was before this year.
- Don’t assume you need to itemize to benefit. Most of these new tax deductions 2026 are structured as above-the-line or standalone deductions, meaning they stack on top of your standard deduction rather than requiring you to give it up.
Bottom Line
New tax deductions 2026 genuinely expand who gets a break, tipped and overtime workers, seniors, car buyers, teachers, and casual charitable donors all have new or bigger deductions than they did a year ago. None of these require complicated tax strategy to claim, but they do require knowing they exist and keeping the right records throughout the year. Reviewing this list now, months before filing season, is exactly the kind of planning that separates a smooth tax season from a scramble in April, a theme worth revisiting alongside your broader year-round financial planning rather than treating taxes as a once-a-year afterthought.
This article is for informational purposes only and does not constitute tax or financial advice. Consult a licensed tax professional or CPA for guidance specific to your situation.